










Vallabh Steels reviewer cannot assess going concern position
Key highlights
- Vallabh Steels reported Rs 1.72 crore of current trade receivables at 30 September 2026, down from Rs 1.85 crore at 31 March 2026.
- The reviewer could not verify valuation, ageing, obsolescence or impairment of Rs 49.75 lakh of reported inventory.
- Vallabh Steels reported current borrowings of Rs 40.61 crore at 30 September 2026, up Rs 10 crore from 31 March 2026.
- Vallabh Steels said on 14 November 2026 that the impact of the review qualifications had not been quantified.
powered by IRIS
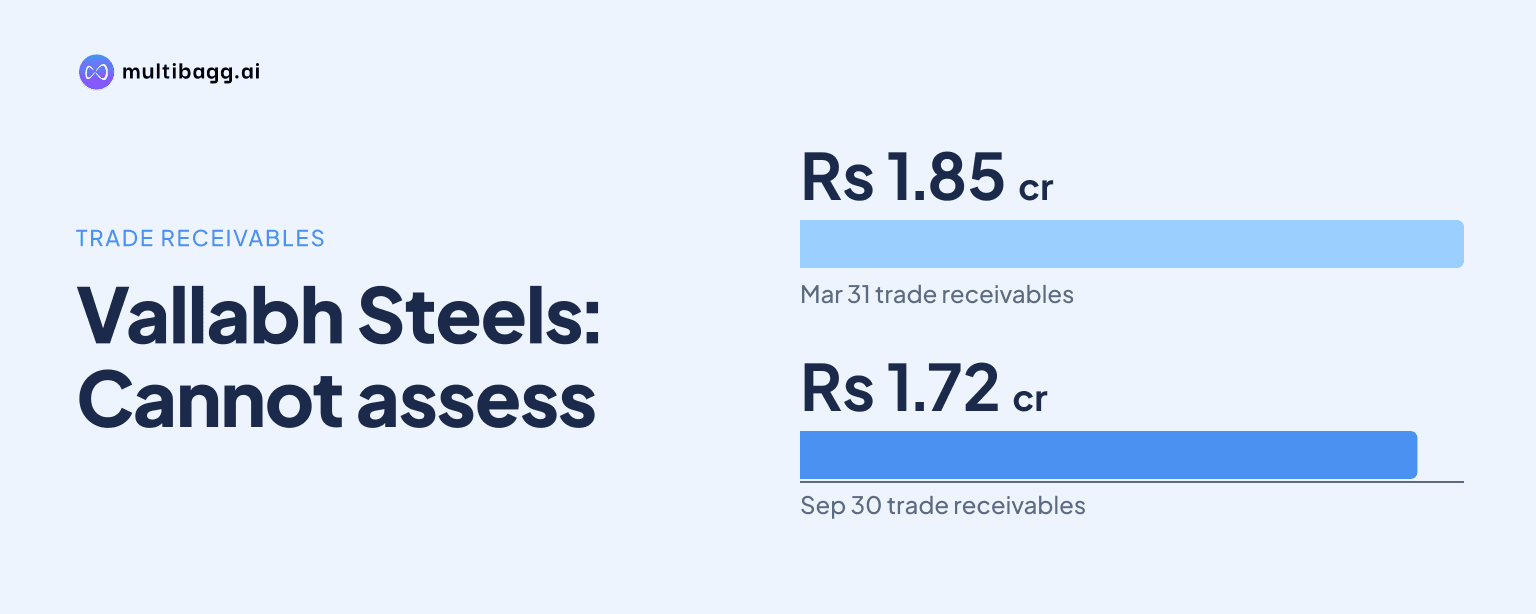
Vallabh Steels Limited received a qualified limited-review conclusion for the quarter and half year ended 30 September 2026 after its reviewer could not comment on going concern, inventory or certain receivables; the company reported Rs 1.72 crore of current trade receivables and said the qualifications’ financial impact was unquantified on 14 November 2026.
Know Vallabh Steels inside out
Results, valuation, peers and who's buying, in one view.
What did the Vallabh Steels reviewer conclude?
Vallabh Steels received a qualified conclusion from KR Aggarwal & Associates on its unaudited standalone financial results for the quarter and half year ended 30 September 2026. The reviewer said that, except for the matters in its basis for qualified conclusion, nothing had come to its attention to indicate that the statement did not meet the disclosure requirements of Regulation 33 of the Securities and Exchange Board of India, or SEBI, Listing Obligations and Disclosure Requirements Regulations, 2015.
The 14 November 2026 conclusion was based on a limited review under Standard on Review Engagements 2410. The reviewer said such work consists primarily of inquiries and analytical procedures and is substantially narrower than an audit under the Companies Act, 2013; it therefore does not provide assurance that all significant matters identifiable in an audit would be detected.
Vallabh Steels’ company secretary, Charanjit Kaur, stated in a 14 November 2026 declaration that the financial impact of the qualifications had not been quantified. As a result, the filing does not specify potential adjustments to the reported Rs 22.81 crore of total assets, negative other equity of Rs 28.72 crore, or the half-year pre-tax loss of Rs 52.64 lakh.
Why did Vallabh Steels’ receivables and inventory draw qualifications?
Vallabh Steels’ reviewer said that certain trade debtors had no provision under Indian Accounting Standard 109, or Ind AS 109, Financial Instruments, through the expected-credit-loss method on receivables. The filing reports total current trade receivables of Rs 1.72 crore at 30 September 2026, down Rs 13.75 lakh from Rs 1.85 crore at 31 March 2026, but it does not identify the portion represented by the debtors cited in the qualification.
The reviewer also said appropriate stock records were unavailable, preventing it from commenting on inventory valuation, ageing, obsolescence and impairment. Management certified the inventory balance of Rs 49.75 lakh at 30 September 2026, unchanged from 31 March 2026, but the reviewer could not independently verify compliance with Ind AS 2, Inventories, which requires valuation at the lower of cost and net realisable value.
The report further said that short-term trade payables and other current liabilities, including customer advances and other payables, were subject to confirmation. Trade receivables, loans and advances, and other current assets, including advances and statutory receivables, were also subject to confirmation at 30 September 2026, while the 14 November filing gave no completion date for those confirmations.
Got a follow-up? Ask IRIS
Why could the reviewer not comment on Vallabh Steels’ going concern?
Vallabh Steels did not give the reviewer an assessment of whether events or conditions created a material uncertainty that could cast significant doubt on its ability to continue as a going concern. The reviewer therefore said it was unable to comment on going concern in its report dated 14 November 2026; the filing contains no management forecast, refinancing arrangement, lender-support disclosure or operating plan addressing that missing assessment.
The reported balance sheet includes several figures relevant to the unassessed position. Vallabh Steels reported negative other equity of Rs 28.72 crore at 30 September 2026, compared with negative other equity of Rs 28.19 crore at 31 March 2026, while total assets declined by Rs 50.90 lakh to Rs 22.81 crore over the same period.
Current borrowings were Rs 40.61 crore at 30 September 2026, an increase of Rs 10 crore from Rs 30.61 crore at 31 March 2026. Non-current borrowings were Rs 5.72 crore at both dates, and the cash-flow statement reported cash and cash equivalents of Rs 2.47 lakh at 30 September 2026, compared with Rs 2.29 lakh at the start of the half year.
What other accounting matters did the Vallabh Steels reviewer identify?
Vallabh Steels did not provide actuarial valuation reports required for employee-benefit accounting under Ind AS 19, Employee Benefits, according to the reviewer. It said it could not ascertain the resulting impact on the financial statements; non-current provisions were reported at Rs 7.83 lakh at both 30 September 2026 and 31 March 2026, without a break-up of any actuarially measured obligation.
Management had also not conducted the impairment assessment for property, plant and equipment described in Ind AS 36, Impairment of Assets. The reviewer said it was therefore unable to comment on the fair value of those assets, which Vallabh Steels reported at Rs 6.72 crore at 30 September 2026, down Rs 35.87 lakh from Rs 7.08 crore at 31 March 2026.
The reviewer said the company’s accounts had been categorised as non-performing assets, or NPA, and that all bank balances were consequently subject to confirmation. Vallabh Steels reported only one operating segment, manufacturing steel products, for the half year ended 30 September 2026, so the filing does not provide segment-level detail on the affected receivables, inventory or property, plant and equipment.
Conclusion
The 30 September 2026 limited review leaves several reported Vallabh Steels balances subject to unresolved review matters. These include certain debtors within Rs 1.72 crore of current trade receivables, inventory of Rs 49.75 lakh without appropriate stock records, and property, plant and equipment of Rs 6.72 crore without the disclosed impairment assessment; the reviewer also could not comment on going concern.
The next disclosure to watch is whether Vallabh Steels provides the missing going-concern assessment, actuarial valuation reports, impairment review and confirmations for bank, receivable and payable balances. As of 14 November 2026, management had not quantified the qualifications’ impact or disclosed a timetable for resolving them, making a subsequent results filing or reviewer communication the relevant update.