










Vikas WSP auditors flag unverified assets and liabilities
Key highlights
- Vikas WSP received a qualified limited-review conclusion for the quarter and half year ended 30 September 2026.
- Vikas WSP reported total assets of Rs 1,377.04 crore at 30 September 2026, including Rs 462.64 crore of property, plant and equipment.
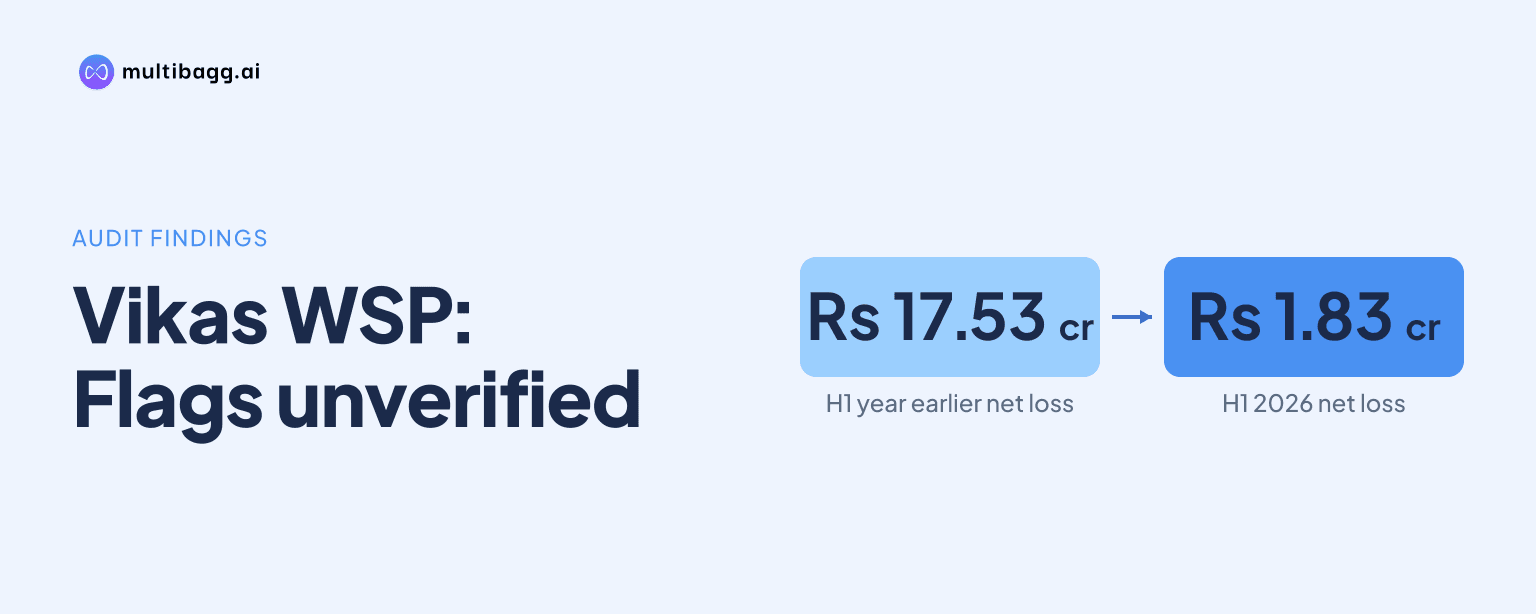
- Vikas WSP’s half-year net loss narrowed to Rs 1.83 crore from Rs 17.53 crore a year earlier.
- The NCLT approved Vikas WSP’s resolution plan on 9 September 2026, with implementation overseen by a monitoring committee.
powered by IRIS
Vikas WSP Limited received a qualified limited-review conclusion for the quarter and half year ended 30 September 2026 because auditors could not assess potential adjustments to assets, liabilities, creditor claims and depreciation, while Vikas WSP reported total assets of Rs 1,377.04 crore and continued implementing its approved resolution plan.
Know Vikas Wsp inside out
Results, valuation, peers and who's buying, in one view.
Why did Vikas WSP receive a qualified conclusion?
Vikas WSP received a qualified conclusion because the auditors could not determine the possible effects of unresolved impairment, unconfirmed balance-sheet balances, unreconciled creditor claims and unavailable fixed-asset records as at 30 September 2026. The auditors said that, except for the possible effects of these matters, the standalone results complied with the applicable listing and accounting requirements.
The review was performed under Standard on Review Engagement 2410, which provides moderate assurance through inquiries and analytical procedures rather than an audit opinion. A K Chadda & Co stated that it had not performed an audit and therefore did not express an audit opinion on Vikas WSP’s standalone results, which were dated 12 November 2026.
The qualification is connected to records that were not fully handed over to the chairman of the monitoring committee. Management had informed the resolution professional on 15 February 2022 that a ransomware attack had made Tally data, the fixed-assets register and other relevant records before 1 April 2021 unavailable; an application under Section 19(2) of the Insolvency and Bankruptcy Code, 2016 was submitted to the National Company Law Tribunal, or NCLT.
Which Vikas WSP balances could require adjustment?
Vikas WSP’s property, plant and equipment of Rs 462.64 crore was among the balances subject to uncertainty because the company had not fully assessed impairment or fair value at 30 September 2026. The auditors said they could not comment on any resulting impairment required in the carrying value of tangible assets under Indian Accounting Standard 36, or Ind AS 36.
The company had also not completed a comprehensive review of its assets and liabilities, including Goods and Services Tax balances, receivables, advances, trade payables and other short-term liabilities. Auditors said the balances were unconfirmed and documentary evidence was unavailable to verify them, while potential asset impairment and liability write-backs had not been assessed during resolution-plan implementation.
Vikas WSP reported total assets lower by Rs 5.15 crore from 31 March 2026, while total current assets fell by Rs 4.97 crore. Cash and cash equivalents rose to Rs 8.91 lakh from Rs 5.86 lakh, but bank balances other than cash equivalents declined to Rs 36.91 lakh from Rs 5.42 crore; the auditors said the reported balances could require adjustment after the pending review.
What did auditors say about Vikas WSP creditor claims?
Vikas WSP’s financial and operational creditor claims were still being reconciled with amounts in the books, so no provision or accounting adjustment had been recorded for excess, short or unreceived claims. The auditors said the financial effect on the results for the half year ended 30 September 2026 was not currently ascertainable while submission and reconciliation remained ongoing.
The issue arises during the Corporate Insolvency Resolution Process, or CIRP, that began after the NCLT admitted the insolvency petition on 2 February 2022. The Committee of Creditors approved the resolution plan submitted by Arcbolt Space and Foods Private Limited on 25 August 2022, and the NCLT approved that plan on 9 September 2026.
Vikas WSP also did not produce a fixed-assets register because it had not been handed over by past management. The auditors therefore could not comment on the accuracy of property, plant and equipment values, the current depreciation calculation or the possible effect on the financial statements at 30 September 2026.
The company said depreciation was measured on a straight-line basis using available information, and that no depreciation was provided on plant and machinery where residual value was considered substantially equal to or higher than carrying value. It recorded depreciation of Rs 12.49 lakh in the September 2026 quarter, unchanged from the June 2026 quarter but below Rs 8.54 crore in the September 2025 quarter.
Got a follow-up? Ask IRIS
How did Vikas WSP losses change in September 2026?
Vikas WSP reported a net loss of Rs 1.53 crore for the quarter ended 30 September 2026, compared with a loss of Rs 8.76 crore in the corresponding quarter a year earlier. Revenue from operations was nil in both quarters, while other income was Rs 7.29 lakh in the latest period, compared with Rs 4.80 lakh a year earlier.
The lower reported quarterly loss coincided principally with a reduction in depreciation and total expenses. Total expenses were Rs 1.61 crore for the September 2026 quarter, down from Rs 8.81 crore in September 2025, although other expenses increased to Rs 1.44 crore from Rs 23.53 lakh and employee-benefit expense rose to Rs 4.35 lakh from Rs 2.97 lakh.
For the six months ended 30 September 2026, Vikas WSP’s net loss narrowed to Rs 1.83 crore from Rs 17.53 crore a year earlier, while total income was broadly unchanged at Rs 11.34 lakh versus Rs 11.14 lakh. The qualified conclusion is relevant to that comparison because the auditors could not determine whether impairment, confirmation of balances and reconciliation of creditor claims would change the reported loss.
What does the resolution-plan implementation mean for Vikas WSP?
Vikas WSP’s resolution plan, submitted by Arcbolt Space and Foods Private Limited, was approved by the NCLT Chandigarh Bench on 9 September 2026 and remained under implementation when the results were issued on 12 November 2026. The plan provides for settlement of creditor claims, funding for working capital and capital expenditure, restructuring of existing share capital and reconstitution of the board within the stipulated timelines.
A monitoring committee exercises the powers otherwise held by Vikas WSP’s board during the implementation term. It includes a Bank of India representative for financial creditors, Karan Jakhar as the resolution applicant’s representative, and Darshan Singh Anand, the erstwhile resolution professional, as chairman; the term cannot extend beyond 90 days from the NCLT approval order.
Auditors drew attention to a material uncertainty related to going concern because Vikas WSP had continuous losses, current liabilities exceeding current assets, and defaults on borrowings and regulatory or statutory dues. They said the ability to restart and sustain operations depends on timely plan implementation, proposed fund availability, restoration of manufacturing facilities, working-capital support and sufficient future cash flows.
Conclusion
Vikas WSP’s September 2026 limited review did not reject the standalone results, but it qualified them because significant reported balances may require verification and adjustment. The reported half-year loss narrowed to Rs 1.83 crore from Rs 17.53 crore, yet the auditors could not quantify the impact of unresolved impairment, asset and liability reviews, creditor claims, fixed-asset records and confidential CIRP information.
The next disclosed milestone is completion of the resolution-plan implementation term, which cannot be later than 90 days from the 9 September 2026 NCLT approval order. Readers should watch for progress on creditor settlements, fund infusion, capital restructuring, restoration of facilities, record transfer and the reconciliation or adjustment of balances identified in the qualified conclusion.