










Virinchi promoter holding could reach 45.76% after dilution
Key highlights
- Virinchi’s promoter holding would rise to 45.76% from 39.46% on the stated fully diluted basis.
- Virinchi proposes 2 crore warrants at Rs 15 each for an intended fund raise of up to Rs 30 crore.
- Viswanath Kompella would receive 1.5 crore warrants, representing up to Rs 22.50 crore.
- The diluted calculation includes 1,33,39,524 outstanding warrants and 58,90,482 ESOPs.
powered by IRIS
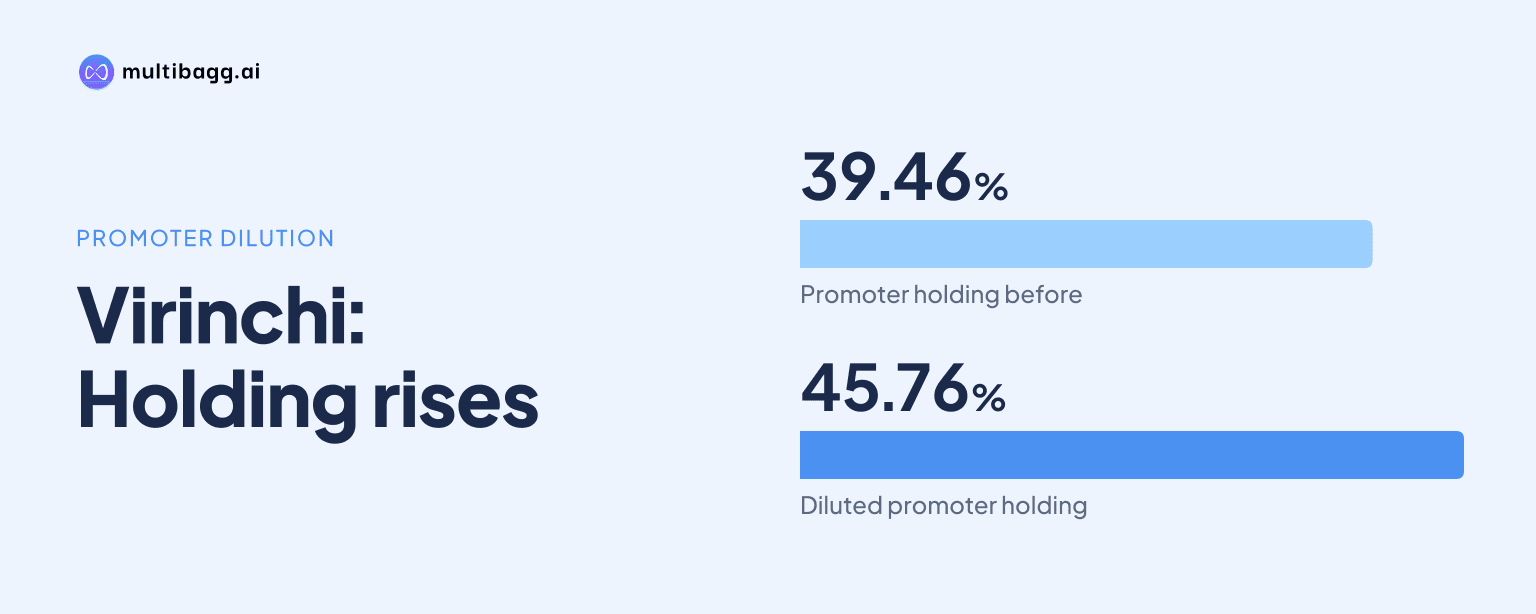
Virinchi Limited’s promoter holding could rise to 45.76% from 39.46% on a fully diluted basis if 2 crore proposed warrants are converted, alongside 1,33,39,524 outstanding warrants and 58,90,482 employee stock options. The November 10, 2026 notice says the proposed preferential issue would not change control of Virinchi.
Know Virinchi inside out
Results, valuation, peers and who's buying, in one view.
How would Virinchi’s ownership change after full conversion?
Virinchi’s promoter ownership would increase by 6.30 percentage points to 45.76% from 39.46% under the fully diluted shareholding pattern in the notice. Promoter shares would rise to 6,95,25,538 from 4,44,75,538, while the total share count would increase to 15,19,37,378 from 11,27,07,372.
The proposed issue accounts for 2 crore of the 3,92,30,006-share increase in the fully diluted total. The remaining 1,92,30,006 potential shares come from 1,33,39,524 warrants outstanding on the notice date and 58,90,482 employee stock options, or ESOPs, outstanding for exercise.
Virinchi’s public holding would decline by 6.30 percentage points to 54.24% from 60.54%, although the public share count would increase by 1,41,80,006. The difference reflects the new 50 lakh warrants proposed for a public allottee as well as the pre-existing warrants and ESOPs included in the company’s post-conversion calculation.
Within promoter ownership, Indian individuals and Hindu Undivided Families would hold 4,19,89,988 shares, or 27.64%, after conversion, compared with 2,69,89,988 shares, or 23.95%, before the issue. Total Indian promoter ownership would move to 44.74% from 38.09%, while foreign promoter individual ownership would represent 1.02% after conversion versus 1.37% before.
Who would receive Virinchi’s new warrants and what would they pay?
Virinchi proposes to issue up to 2 crore warrants at Rs 15 each, for an intended fund raise of up to Rs 30 crore. Each warrant would be convertible into one fully paid equity share with a face value of Rs 10, giving the proposed issue a one-for-one conversion ratio.
Promoter Viswanath Kompella would receive up to 1.5 crore warrants, representing a subscription of up to Rs 22.50 crore at the stated price. IT Peer Technologies LLC, classified as a public shareholder, would receive the remaining 50 lakh warrants, equivalent to up to Rs 7.50 crore at Rs 15 per warrant.
Viswanath Kompella’s holding would increase to 3,13,70,888 shares, or 20.65%, from 1,63,70,888 shares, or 14.53%, on the stated fully diluted basis. IT Peer Technologies LLC would hold 90 lakh shares, or 5.92%, compared with 9,10,476 shares, or 0.81%, before the proposed issue.
Subscribers must pay Rs 3.75 per warrant at subscription and allotment, equal to 25% of the Rs 15 issue price. The remaining Rs 11.25 per warrant, or 75%, would be payable when a holder exercises the conversion right within the permitted tenure.
The notice identifies Rajeshwar Rao Karpe as holding 100% of IT Peer Technologies LLC. It describes Viswanath Kompella as an individual and therefore states that there is no ultimate beneficial owner behind his proposed allotment.
Got a follow-up? Ask IRIS
What existing instruments are included in Virinchi’s diluted calculation?
Virinchi’s post-issue percentages include more than the proposed 2 crore warrants because they also assume conversion of 1,33,39,524 pending warrants and exercise of 58,90,482 ESOPs. Together, those existing instruments represent 1,92,30,006 potential equity shares beyond the proposed preferential issue.
The company had already allotted 39,10,476 equity shares between April 1, 2026 and the notice date following conversion of an equal number of previously issued warrants. The listed conversions included 9,10,476 shares for IT Peer Technologies LLC and 8,50,000 shares for Vivo Bio Tech Limited, which is classified as a promoter-group entity.
The fully diluted presentation shows differing effects across public categories. Foreign companies would hold 90,81,290 shares, or 5.98%, after conversion, compared with 9,91,766 shares, or 0.88%, before the issue; the category includes the proposed 50 lakh warrants for IT Peer Technologies LLC.
Resident individuals holding securities valued at up to Rs 2 lakh would hold 19.29% after conversion, down from 25.83%, despite their shares rising to 2,93,14,718 from 2,91,14,718. Resident individuals holding more than Rs 2 lakh would remain at 2,61,96,888 shares but their percentage would fall to 17.24% from 23.24% because of the larger fully diluted equity base.
When can Virinchi allot and convert the warrants?
Virinchi must complete the warrant allotment within 15 days of shareholder approval of the special resolution, unless a regulatory approval or permission is pending. If such approval is required, the company says allotment would be completed within 15 days of receiving it, or within any further period allowed by the relevant authorities.
Warrant holders may convert their instruments in one or more tranches within 18 months from allotment. After receiving a conversion notice and the outstanding exercise payment, Virinchi says it would allot the resulting equity shares within 15 days of the conversion date.
The warrants would not carry voting rights before conversion. Equity shares issued on conversion would rank pari passu with existing shares, including for voting rights and dividends, and Virinchi says it would apply to BSE and NSE for listing of those shares.
The warrants and resulting shares would be subject to the applicable lock-in requirements under Chapter V of the Securities and Exchange Board of India’s Issue of Capital and Disclosure Requirements Regulations. Virinchi also states that the preferential issue would neither alter the board’s composition nor change control of the company.
Viswanath Kompella would remain classified as a promoter after the proposed issue, while IT Peer Technologies LLC would remain a public shareholder. The notice says the proposed allottees had not sold or transferred Virinchi equity shares during the 90 trading days preceding the relevant date.
Conclusion
Virinchi’s proposed warrants would increase the promoter shareholding percentage to 45.76% on the company’s fully diluted basis, from 39.46% before the issue. That calculation combines the proposed 2 crore warrants with 1,33,39,524 outstanding warrants and 58,90,482 ESOPs, rather than measuring the proposed allotment in isolation.
The next disclosed steps are shareholder approval of the special resolution and warrant allotment within the applicable 15-day period. Holders would then have up to 18 months from allotment to convert, making the pace of exercise of the proposed warrants, existing warrants and ESOPs the key disclosed factor in the eventual shareholding outcome.