










Visaman uses all Rs 48.20 crore raised in preferential issue
Key highlights
- Visaman utilised all Rs 48.20 crore received under its preferential issue by 30 September 2026.
- Working capital received Rs 36.15 crore of preferential proceeds, while general corporate purposes received Rs 12.05 crore.
- Rs 10.35 crore remains receivable upon conversion of 23 lakh outstanding warrants.
- Visaman retained Rs 12.96 lakh of IPO proceeds for manufacturing-facility capital expenditure.
powered by IRIS
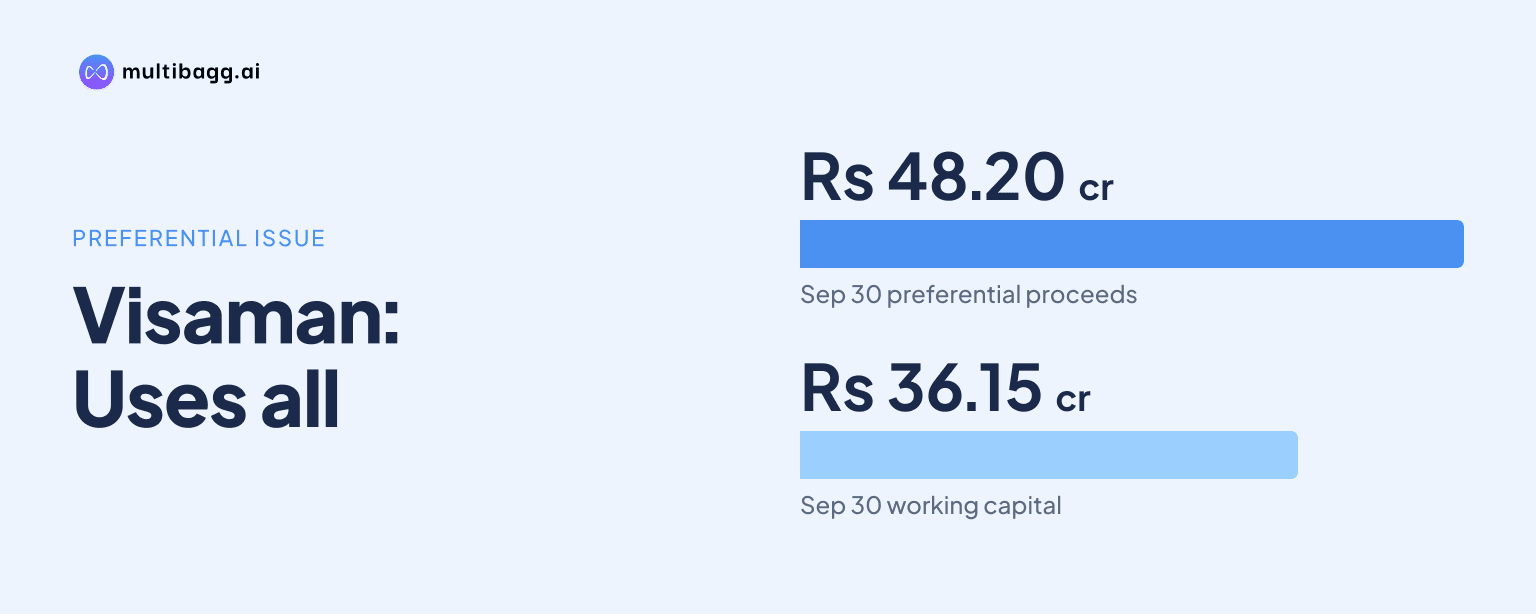
Visaman Global Sales Limited had deployed all Rs 48.20 crore received under its preferential issue by 30 September 2026, with Rs 36.15 crore used for working capital and Rs 12.05 crore for general corporate purposes. A further Rs 10.35 crore remains receivable if 23 lakh outstanding warrants are converted under the issue terms.
Know Visaman Global Sales inside out
Results, valuation, peers and who's buying, in one view.
How much preferential-issue money had Visaman received?
Visaman had received Rs 48.20 crore by 30 September 2026 against Rs 58.64 crore originally disclosed for the preferential issue. The statutory auditor clarified that Rs 9 lakh of the disclosed amount was not issued, reducing the actual aggregate issue size to Rs 58.55 crore. The amount received included upfront money paid on warrants that were still outstanding at the reporting date.
The preferential issue comprised 55.59 lakh equity shares and 42 lakh share warrants. Of the warrants, 19 lakh had converted into equity shares after receipt of the Rs 60-per-warrant balance consideration. The remaining 23 lakh warrants had generated upfront subscription money of Rs 3.45 crore, calculated at Rs 15 per warrant, and were pending conversion on 30 September 2026.
The Rs 10.35 crore balance represents the difference between funds received and the revised Rs 58.55 crore issue size. It is not recorded as unutilised cash in the utilisation statement because it had not been received as of 30 September 2026. The certificate dated 13 November 2026 says receipt remains subject to the terms governing the outstanding warrants.
Where did Visaman use the Rs 48.20 crore received?
Visaman used Rs 36.15 crore for working-capital requirements and Rs 12.05 crore for general corporate purposes, exhausting the Rs 48.20 crore raised by 30 September 2026. The utilisation statement reported no unutilised amount in either category. The two uses together equal the reported funds received to date.
Working capital accounted for the larger portion of the Rs 48.20 crore received, at Rs 36.15 crore, compared with Rs 12.05 crore for general corporate purposes. The original offer-document allocation was Rs 43.98 crore for working capital and Rs 14.66 crore for general corporate purposes. The difference reflects the Rs 10.35 crore that remained receivable on the 23 lakh warrants rather than a reported unspent balance.
The utilisation certificate distinguishes between deployment of received proceeds and the full potential proceeds from the issue. Visaman had spent the money it had received, but the stated working-capital allocation still had Rs 7.76 crore to be raised and the general-corporate allocation had Rs 2.59 crore to be raised. These two amounts total the Rs 10.35 crore balance consideration.
Got a follow-up? Ask IRIS
What depends on Visaman's outstanding warrants?
Visaman's receipt of the remaining Rs 10.35 crore depends on conversion of 23 lakh warrants that were outstanding on 30 September 2026. The company had already received Rs 3.45 crore in upfront subscription money on these warrants, which was included in the Rs 48.20 crore raised. The balance consideration would be received only under the warrant-conversion terms.
The disclosure does not provide a conversion deadline or a scheduled receipt date for the Rs 10.35 crore. It identifies working capital and general corporate purposes as the intended uses of the balance proceeds, allocating Rs 7.76 crore and Rs 2.59 crore respectively. Therefore, the company had no reported unutilised preferential proceeds at 30 September 2026, while further funding remained conditional on conversion.
Visaman's balance sheet separately recorded Rs 3.45 crore as money received against share warrants at both 30 September 2026 and 31 March 2026. That figure corresponds to the upfront money on the 23 lakh pending warrants. It does not include the Rs 10.35 crore balance consideration that the auditor described as receivable upon conversion.
How does the preferential issue compare with Visaman's IPO proceeds?
Visaman's Rs 48.20 crore of preferential proceeds received by 30 September 2026 was larger than the Rs 16.05 crore fresh issue completed in its public offering before listing on the NSE Limited SME Platform on 1 July 2024. Of the public-offering proceeds, Rs 15.92 crore had been utilised and Rs 12.96 lakh remained unutilised at the same reporting date. In contrast, the preferential issue had no reported unused balance from money received.
The Rs 12.96 lakh IPO balance remained earmarked for capital expenditure on a manufacturing facility. Visaman obtained shareholder approval through a special resolution on 21 December 2024 to move the planned site from Village Jiyana, Rajkot, to Wankaner, Morbi, Gujarat. The certificate says the Rs 7.22 crore capex allocation itself was unchanged despite the location change.
The IPO's Rs 7 crore working-capital allocation, Rs 22.02 lakh general-corporate allocation and Rs 1.61 crore offer-expense allocation had all been fully utilised by 30 September 2026. D. K. Kalyani and Associates stated that the IPO and preferential-issue utilisation statement agreed with Visaman's books of account and financial results for the half year ended that date. The auditor said the statement fairly presented utilisation and unutilised funds in all material respects.
Conclusion
Visaman had fully deployed the Rs 48.20 crore raised from its preferential issue as of 30 September 2026, directing Rs 36.15 crore to working capital and Rs 12.05 crore to general corporate purposes. The reported utilisation is complete only for money received, rather than for the revised Rs 58.55 crore aggregate issue size.
The next disclosed matter is whether the remaining 23 lakh warrants convert, which would make Rs 10.35 crore of balance consideration receivable subject to the issue terms. Visaman also had Rs 12.96 lakh of IPO proceeds still allocated to the manufacturing facility at Wankaner, Morbi, following the site change approved on 21 December 2024.