










Warren Tea first-half loss narrows to Rs 2.25 crore in September
Key highlights
- Warren Tea’s consolidated first-half loss was Rs 2.25 crore, compared with Rs 2.43 crore a year earlier.
- Warren Tea’s share of associate loss fell to Rs 1.09 crore from Rs 1.28 crore in the first half.
- Warren Tea’s standalone operating activities used Rs 1.82 crore of cash in the half year ended September 30, 2026.
- Warren Tea’s total assets were Rs 104.23 crore at September 30, 2026, compared with Rs 105.53 crore at March 31, 2026.
powered by IRIS
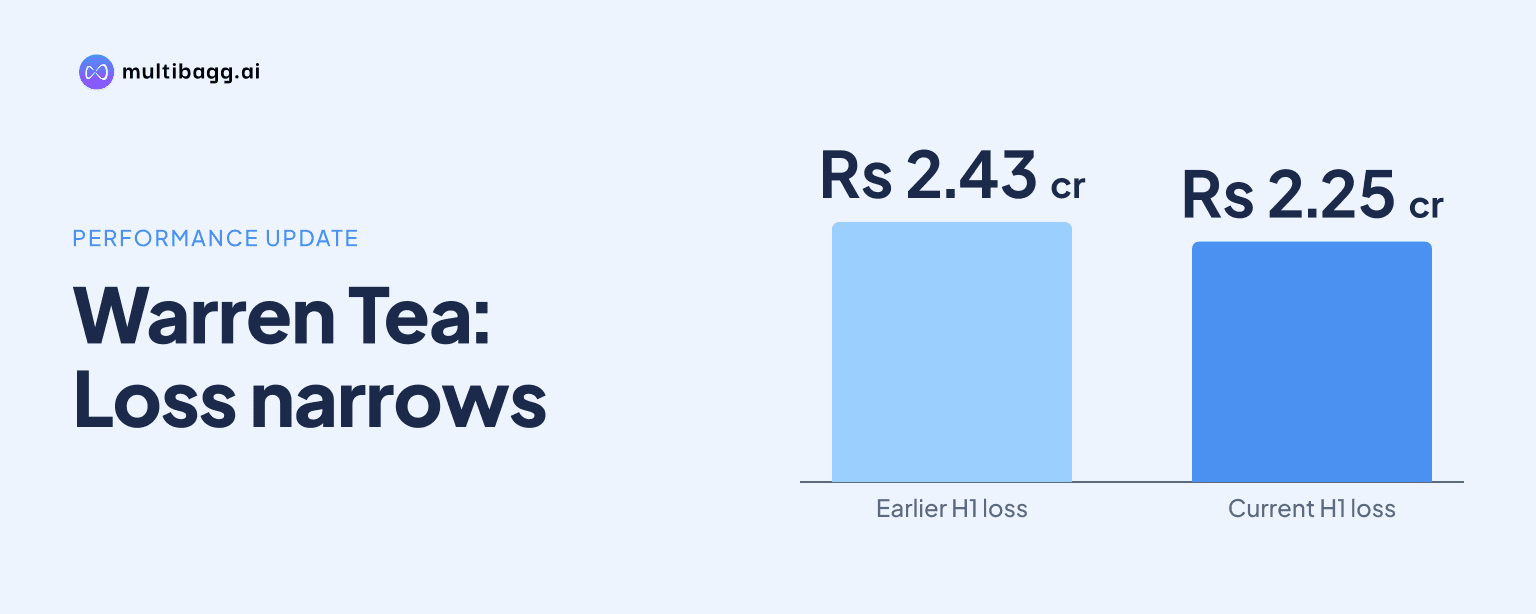
Warren Tea Limited reported a Rs 2.25 crore consolidated loss for the half year ended September 30, 2026, compared with a Rs 2.43 crore loss a year earlier, because its share of loss from an associate decreased to Rs 1.09 crore from Rs 1.28 crore while the loss before that share edged higher to Rs 1.16 crore.
Know Warren Tea inside out
Results, valuation, peers and who's buying, in one view.
What caused Warren Tea’s first-half consolidated loss to narrow?
Warren Tea’s consolidated loss narrowed by Rs 18 lakh in the six months ended September 30, 2026, principally because its share of loss from investments in an associate declined by Rs 19 lakh. The associate loss was Rs 1.09 crore, against Rs 1.28 crore in the half year ended September 30, 2025.
The loss after tax but before the associate’s result was Rs 1.16 crore, compared with Rs 1.15 crore a year earlier. That Rs 1 lakh increase means the reduced consolidated loss was not driven by an improvement in the measure reported before the associate contribution. The consolidated statement recorded no current or deferred tax expense in either first-half period.
Total income was Rs 74 lakh, down Rs 1 lakh from Rs 75 lakh a year earlier, while total expenses were unchanged at Rs 1.90 crore. As a result, the loss before exceptional items and tax was Rs 1.16 crore, compared with Rs 1.15 crore. The filing reported no exceptional item for either first-half period.
How did Warren Tea perform in the September 2026 quarter?
Warren Tea recorded a Rs 1.05 crore consolidated loss in the quarter ended September 30, 2026, compared with a Rs 1.22 crore loss in the September 2025 quarter and a Rs 1.20 crore loss in the June 2026 quarter. Other income was Rs 34 lakh, down from Rs 40 lakh in the year-earlier quarter.
Quarterly total expenses fell to Rs 88 lakh from Rs 98 lakh a year earlier. Employee-benefit expense was Rs 42 lakh against Rs 43 lakh, other expenses were Rs 33 lakh against Rs 37 lakh, finance costs declined to Rs 3 lakh from Rs 7 lakh, and depreciation and amortisation was Rs 10 lakh compared with Rs 11 lakh.
The loss before the associate result was Rs 54 lakh, compared with Rs 58 lakh in the September 2025 quarter. Warren Tea’s share of associate loss was Rs 51 lakh, lower than Rs 64 lakh a year earlier, producing the Rs 1.05 crore consolidated quarterly loss. Basic and diluted earnings per share, or EPS, was a loss of Rs 0.88, compared with a loss of Rs 1.02.
What did the associate contribute to Warren Tea’s result?
Warren Tea included Rs 1.09 crore as its share of associate loss for the half year ended September 30, 2026, versus Rs 1.28 crore in the corresponding 2025 period. In the September quarter, the share was Rs 51 lakh, compared with Rs 58 lakh in the June 2026 quarter and Rs 64 lakh in the September 2025 quarter.
The independent auditor identified Maple Hotels and Resorts Limited as Warren Tea’s associate. Maple Hotels and Resorts Limited reported revenue of Rs 6.2034 crore, net loss after tax of Rs 1.0878 crore and total comprehensive loss of Rs 1.0896 crore for the quarter ended September 30, 2026. The supplied filing does not provide the associate’s half-year revenue or loss.
The first-half comparison shows that the Rs 19 lakh reduction in Warren Tea’s reported share of associate loss was greater than the Rs 1 lakh increase in the loss before that share. The consolidated statement presents this as an equity-accounted share of the associate’s result, rather than identifying a profit contribution from Warren Tea’s operations.
Got a follow-up? Ask IRIS
What do Warren Tea’s cash flow and balance sheet show?
Warren Tea’s standalone net cash used in operating activities was Rs 1.82 crore for the half year ended September 30, 2026. The cash outflow followed a Rs 1.49 crore operating loss before working-capital changes, with trade and other receivables using Rs 18 lakh and trade payables and other liabilities using Rs 12 lakh.
Investing activities generated Rs 1.81 crore of cash, including Rs 1.37 crore from current investments, Rs 26 lakh of rent received and Rs 31 lakh of interest and dividend received. After Rs 6 lakh of finance costs paid, cash and cash equivalents plus current bank deposits fell to Rs 14 lakh at September 30, 2026, from Rs 21 lakh at the start of the half year.
Total assets were Rs 104.23 crore at September 30, 2026, down from Rs 105.53 crore at March 31, 2026. Non-current investments declined to Rs 41.28 crore from Rs 42.36 crore and current investments to Rs 12.25 crore from Rs 12.55 crore. Total equity was Rs 94.30 crore, compared with Rs 95.48 crore, while equity share capital remained Rs 11.95 crore.
What remains unresolved in Warren Tea’s financial statements?
Warren Tea said provisions for current and deferred tax will be determined at the end of the financial year ending March 31, 2027, because the ultimate income-tax liability depends on the full-year result. The independent auditor drew attention to that matter but did not modify its review conclusion.
The National Company Law Tribunal, Kolkata Bench, approved the scheme to amalgamate Warren Tea with and into Maple Hotels and Resorts Limited on September 30, 2026. Warren Tea said it had not given legal effect to the amalgamation because its application for a certified true copy of the tribunal order remained pending.
The statutory auditors completed a limited review for the quarter and half year ended September 30, 2026 under Securities and Exchange Board of India listing regulations. Their report stated that nothing had come to their attention to suggest the consolidated statement omitted required information or contained a material misstatement, while noting that a review has a narrower scope than an audit.
Conclusion
Warren Tea’s first-half consolidated loss reduced by Rs 18 lakh to Rs 2.25 crore, but the movement reflected a smaller associate loss rather than an improvement in the loss before the associate result. Income fell to Rs 74 lakh, expenses remained Rs 1.90 crore and standalone operating activities used Rs 1.82 crore of cash.
The next disclosed matters are receipt of the certified tribunal order needed to give legal effect to the amalgamation with Maple Hotels and Resorts Limited and the determination of current and deferred tax at the March 31, 2027 year end. The future level of Warren Tea’s share of associate profit or loss will also affect subsequent consolidated results.