










Price/Earnings to Growth (PEG) Ratio Depends on Assumptions
Key highlights
- Nifty Bank traded at a P/E of 13.51 on 8 September 2026.
- Nifty Midcap Select traded at a P/E of 31.98 on 8 September 2026.
- The worked HDFC Bank calculation produced a trailing PEG of 1.70.
- Adding a 1.85% dividend yield produced an HDFC Bank PEGY of 1.43.
powered by IRIS
On 8 September 2026, the price/earnings to growth (PEG) ratio showed why growth assumptions matter: Indian benchmark P/Es ranged from 13.51 for Nifty Bank to 31.98 for Nifty Midcap Select, so P/E alone cannot compare groups with different expected growth.
What is the PEG ratio and how is it calculated?
The PEG ratio is the price-to-earnings ratio divided by an expected earnings growth rate. Its full form is price/earnings to growth, and the order matters: P/E is the measure being adjusted, while growth is the adjustment.
PEG is not a separate valuation model. It is one ratio divided by one number. The measure is most closely associated with Peter Lynch, who ran Fidelity's Magellan fund and popularised it in One Up on Wall Street. His formulation, still widely quoted, was that a company's P/E should broadly match its earnings growth rate, making a PEG near 1 the reference point. This was a rule of thumb rather than a valuation method.
PEG = P/E ÷ expected annual earnings growth, with growth entered as a plain number rather than as a percentage. A company on a P/E of 30 with expected annual growth of 15% has a PEG of 2. The same P/E of 30 against expected growth of 30% gives a PEG of 1.
The arithmetic is simple, but the difficulty lies in the source of the growth figure. P/E says how many years of current earnings the market is paying for and stops there. It does not state whether earnings are rising or falling. PEG places that P/E beside a growth expectation, on the basis that a high P/E can be reasonable when earnings grow quickly and a low P/E can be unremarkable when they do not.
What do P/E levels look like across Indian benchmarks in 2026?
P/E levels across Indian benchmarks were wide enough on 8 September 2026 that comparing them without context was meaningless. These were NSE's published figures at market open.
Source: NSE, as of 8 September 2026, market open. Levels move intraday.
From 13.51 to 31.98 is a factor of more than two across indices drawn from the same market on the same day. Current figures sit on NSE's Nifty 50 index tracker; the constituents behind them can be followed through Multibagg's Nifty 50 index page.
There is no growth column because NSE publishes P/E and dividend yield against each index, but no expected earnings growth rate. No such figure exists as an observation. Adding one would mean importing somebody's forecast and presenting it as exchange data. That weakness can make two published PEG ratios for the same company disagree, and means a PEG has to be built one company at a time from that company's own filings.
What does a worked PEG ratio look like for an Indian company?
A worked PEG ratio uses four figures from two published sources and a division that can be checked. Take HDFC Bank Ltd (NSE: HDFCBANK). Its audited results for the year ended 31 March 2026 report standalone basic EPS of Rs 48.62 for FY26, against Rs 44.15 for FY25, and equity share capital of Rs 1,539.34 crore at Rs 1 face value, or 1,539.34 crore shares. The AMFI list for the six months ended 30 June 2026 puts its average market capitalisation over that half-year at Rs 12,86,453 crore.
Computed from the two filings linked above. The market-cap input is a six-month average and the earnings input is a full financial year, so this is a trailing PEG on overlapping rather than identical windows, stated here rather than smoothed over.
The 1.70 figure is a trailing P/E divided by historical EPS growth, so it describes what has already happened. Most published PEG ratios use a forward P/E and a forecast growth rate, and therefore will not match it. One year of EPS growth is also a fragile denominator: a three- or five-year earnings CAGR smooths an unusual year and is the more common choice.
What is PEGY?
PEGY is the PEG ratio with dividend yield added to the denominator: P/E ÷ (earnings growth rate + dividend yield). It exists because a company returning cash to shareholders delivers part of its return outside the earnings-growth figure, so PEG alone penalises a mature, high-payout business for growing slowly.
The same HDFC Bank figures show the effect. For FY26, the bank declared a total dividend of Rs 15.50 per share: a Rs 2.50 special interim dividend paid on 11 August 2025 and a Rs 13.00 final dividend recommended to the annual general meeting. Against the implied average price of Rs 835.72, this is a dividend yield of 1.85%, so PEGY = 17.19 ÷ (10.12 + 1.85) = 1.43, compared with a PEG of 1.70 on identical data. The dividend leg moves the ratio by a quarter of its value, which is the argument for the variant and the purpose of the dividend-yield column above.
Got a follow-up? Ask IRIS
How should a PEG ratio be interpreted?
The convention treats 1 as the point where P/E equals the expected growth rate: below 1, P/E is lower than growth, and above 1, it is higher. That is arithmetic rather than a verdict.
The claim commonly attached to the calculation, Peter Lynch's rule of thumb that a PEG under 1 marks a bargain, assumes that the growth estimate is accurate, growth persists over the chosen horizon, and nothing else about the business differs. All three assumptions fail regularly.
The conventional band treats a PEG below 1 as a P/E lower than growth, 1 to 2 as broadly fair, and above 2 as a P/E higher than growth. In the Indian market, however, benchmark P/E levels are high against the growth rates most large companies actually post. PEG values under 1 are uncommon among established large caps, and a screen set at PEG below 1 can return an almost empty list. The worked HDFC Bank example is 1.70.
A PEG below 1 based on a forecast of 30% growth is a statement about the forecast rather than the company, and fast-growing mid- and small-caps are where growth estimates are least reliable. The ratio also excludes debt, cash generation, margin durability, earnings quality and promoter pledging. Two companies with identical PEG values can therefore have very different balance sheets, visible on the stocks hub but not in PEG.
The practical use is comparative: assess PEG against the same company's own history and direct sector peers calculated on the same growth horizon. PEG values from two sources using different horizons are not comparable.
What does a negative PEG ratio mean?
A negative PEG ratio usually means the measure has stopped being usable rather than that it is signalling something. It can result when earnings are negative, pulling P/E below zero, or when earnings are expected to shrink, making the growth denominator negative.
Either route produces a number the ratio was not designed to produce. It should be discarded rather than ranked.
Why do sources publish different PEG ratios for the same company?
Sources publish different PEG ratios because the numerator is observed while the denominator is an estimate. Price is published and earnings are reported, so sources broadly agree on P/E when they use the same definition.
A trailing P/E divides today's price by the last 12 months of reported earnings, while a forward P/E divides it by an estimate of the coming year's earnings. These are different numbers for the same company on the same day, and the worked example uses the trailing version. Growth estimates can differ further by horizon, method and forecaster: one source may use a two-year estimate, another a five-year EPS growth CAGR, and a third historical growth.
The PEG ratio is only as meaningful as the growth assumption inside it, and that assumption is rarely shown beside the number. Growth expectations also move with the wider economy, which is why debates about India's headline growth figures and what a private company is worth turn on the same problem.
How can a stock screener and common checks be used with PEG?
A stock screener turns a ratio from a definition into a filter that can be applied across a list. Multibagg's screener carries valuation and growth fields across NSE- and BSE-listed companies, allowing a P/E filter to sit beside a growth filter rather than requiring one-company-at-a-time reading.
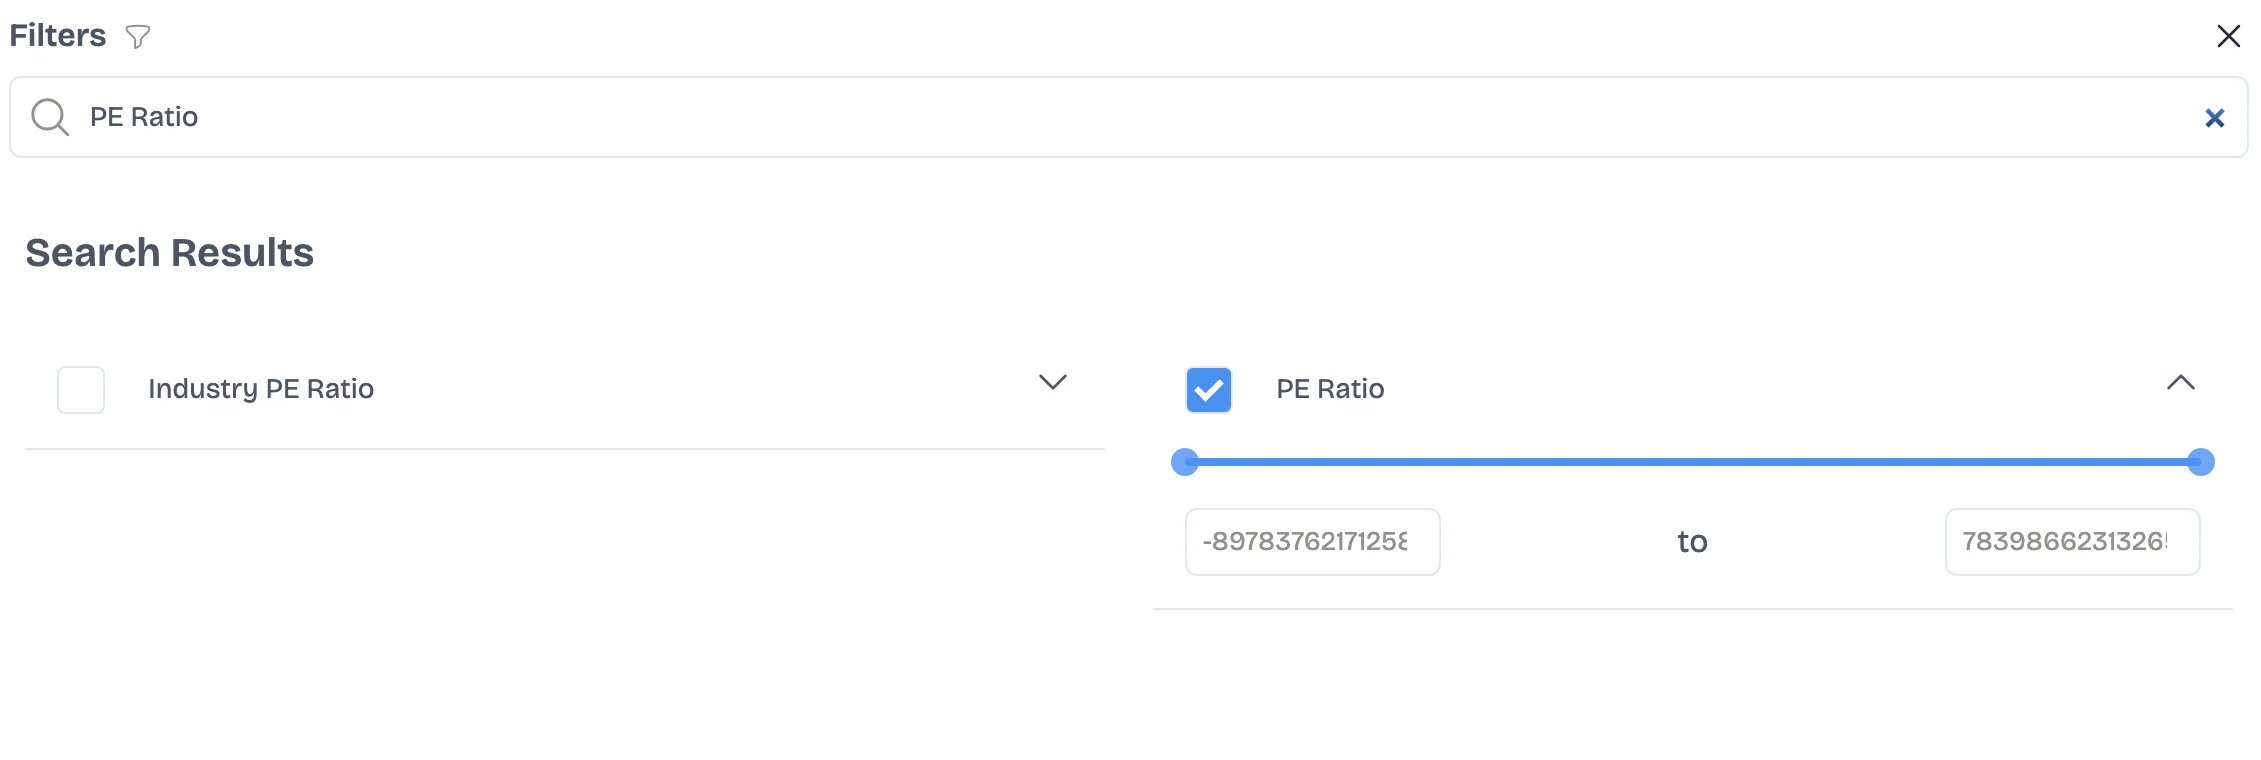
The P/E half of a PEG is a screener field, while the growth half must be chosen and stated. Screenshot taken 15 September 2026. The same principle applies when a business is valued ahead of listing, as the Reliance Jio IPO valuation discussion shows.
Four errors account for most misuse of PEG:
- Treating PEG as a verdict. It is a P/E divided by an estimate, not a conclusion about a company.
- Comparing PEG values from different sources. Different growth horizons can produce different answers from identical price and earnings data.
- Using a negative PEG. Negative earnings or negative expected growth break the ratio; the output is invalid rather than low.
- Comparing sectors without checking the base. Nifty Bank had a P/E of 13.51 against 31.98 for Nifty Midcap Select on 8 September 2026, and the groups do not share a growth profile.
Conclusion
PEG adds a growth assumption to P/E, helping explain why a lower P/E is not automatically more favourable than a higher one. But its result depends on whether the calculation uses trailing or forward earnings, historical or forecast growth, and a one-year rate or a multi-year CAGR. Dividend yield can also alter the result through PEGY.
The practical takeaway is to state the growth basis, use the same horizon when comparing peers or history, and discard negative results rather than ranking them. The ratio should be read alongside balance-sheet and earnings-quality factors that it does not capture.
Disclaimer: This article is for informational and educational purposes only and is not investment, financial, legal or tax advice. Multibagg AI does not recommend whether to buy, sell or hold any security. Figures are as of the dates stated and may change. Consult a SEBI-registered investment adviser before making any investment decision.