Actions
Action Type



Welcome to Multibagg AI
Log in to access personalized features
IRIS
Multibagg AI is an AI powered stock research and analysis platform. We provide data, information, content, and analytics for publicly traded Indian companies listed on NSE and BSE. AI can make mistakes, check important information.
Research powered by GOALZEN CAPITAL SERVICES PRIVATE LIMITED · SEBI Research Analyst INH000013448
Prices might be delayed by a few minutes.
Join our Exclusive Community


Join our Exclusive Community
Made with 💙 in India. © Finsky Technologies Pvt Ltd. 2026


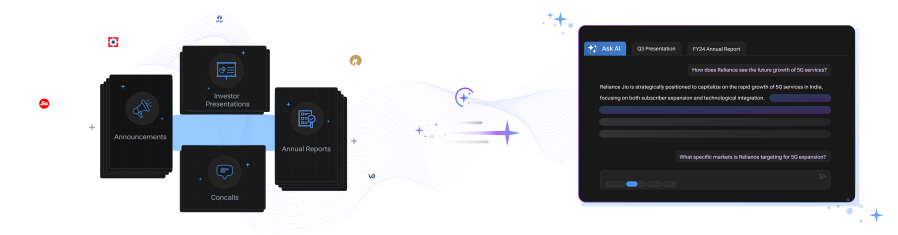
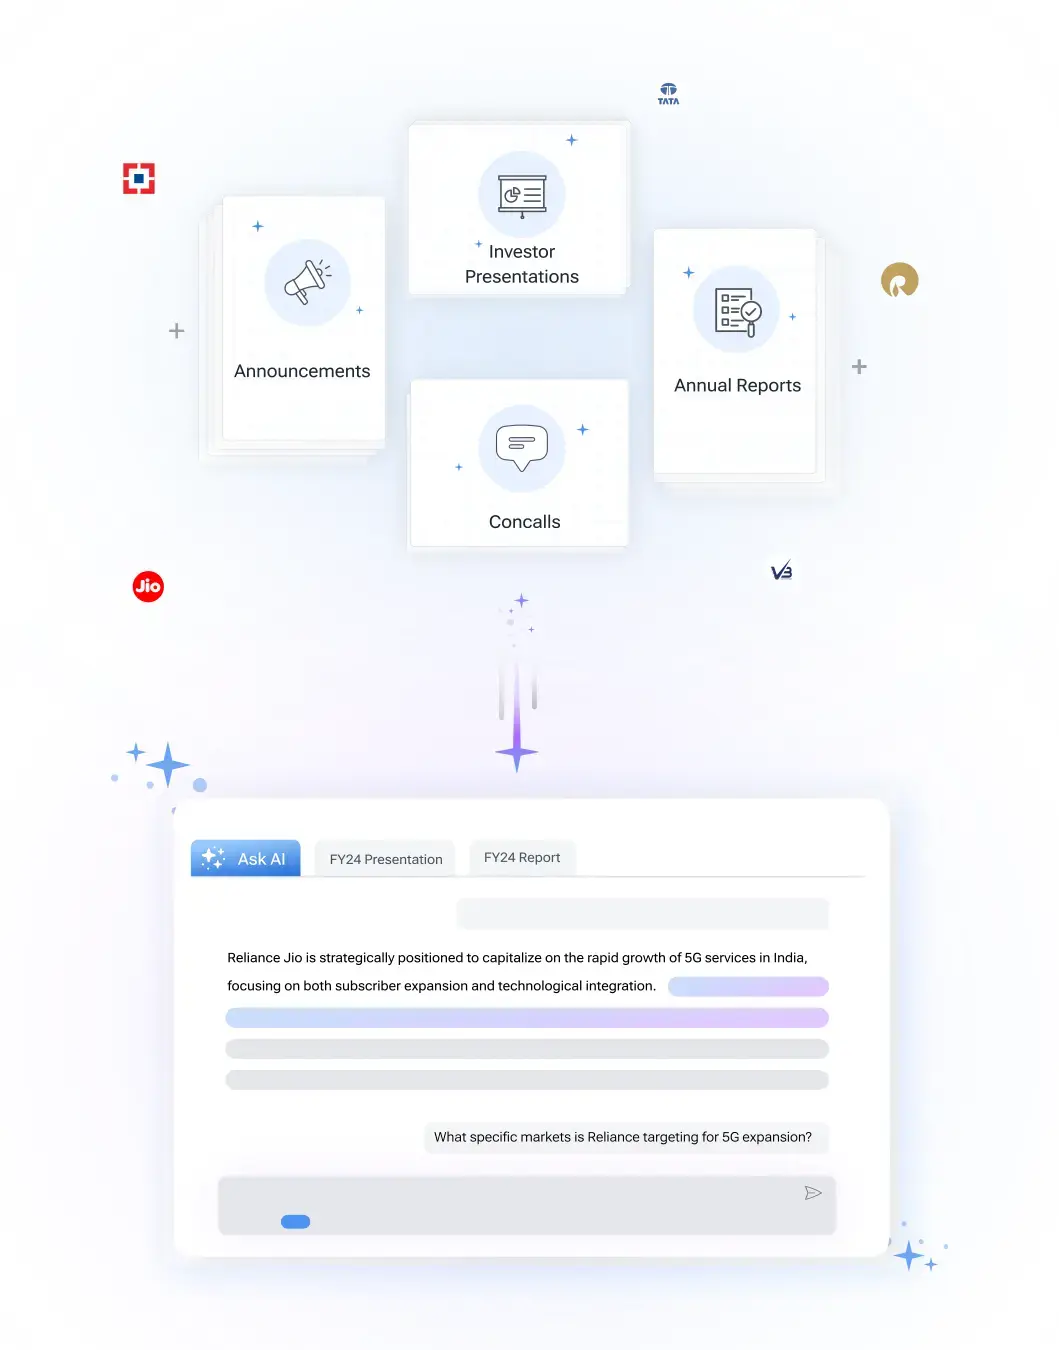
Get instant AI-powered insights about company performance, financials, and strategy. Ask questions about trends, competition, and developments while receiving responses backed by official documents and market data, with clear attribution to source documents.

 Discovery themes featuring this stock
Bearish
8
Neutral
2
Bullish
4
Bearish
16
Neutral
2
Bullish
28
Bearish
8
Neutral
0
Bullish
24
G R Infraprojects Limited is a fully integrated Indian infrastructure developer and EPC contractor focused primarily on roads, with diversification into railways, metro, tunnels, power transmission, oil & gas, BESS and warehousing, operating a portfolio of 43 projects across HAM, BOT, DBFOT and EPC models and executing both construction and asset development roles since 1995.
The company delivered a strong Q1 FY27 with standalone revenue of ~INR2,423 crores, up 32.7% year-on-year, and consolidated revenue of INR2,784 crores up 40% year-on-year; however, standalone adjusted EBITDA margins compressed to about 11%, driven by higher construction and material costs including diesel and energy-linked inputs.
Balance-sheet strength remains a key feature: standalone debt-to-equity is extremely low at 0.03x, consolidated leverage is moderate at 0.55x, net worth increased sequentially, and the company holds an order book of INR25,300 crores plus ~INR32,000 crores of bids pending opening, underpinning multi-year execution visibility.
Strategic diversification is underway across several capital-intensive verticals: management is executing BESS civil works, growing its T&D capability with transmission tower manufacturing, targeting INR1,000 crore-plus in oil & gas revenue for FY27, and plans to deploy significant equity (~INR3,300 crores) into HAM/BoT projects over the next three years.
Monetization and liquidity management are active priorities: the company has transferred assets to Indus Infra Trust and received ~INR70 crores distribution this quarter, targets 3–4 further asset transfers this year, and plans to use monetized capital to fund BoT and new project bids while retaining conservative standalone leverage.
Construction
Civil Construction
7,691 Cr
Low Risk
7.6
21.6
4.1
0.8
1,209.45
738.00
Sales CAGR
Profit CAGR
ROE
ROCE

View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
View Standalone
 Discovery themes featuring this stock
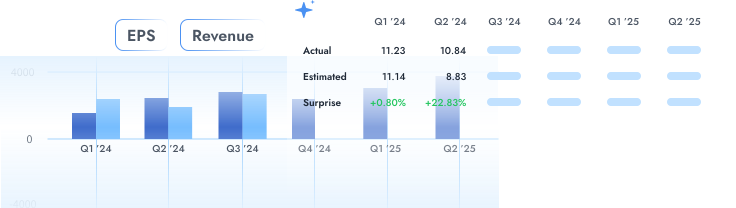
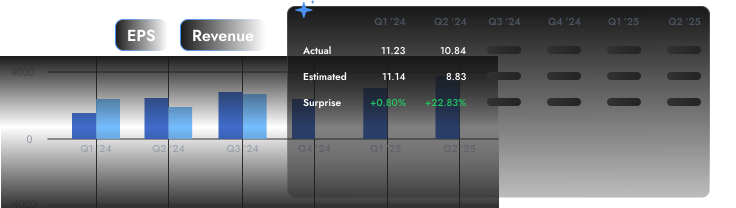

G R Infraprojects Ltd (GRINFRA) is currently trading at 794.85 per share. Stock prices fluctuate during market hours on NSE and BSE based on demand, company updates, and overall market conditions. Refer to the live price chart above for the most recent price movement.
G R Infraprojects Limited is a fully integrated Indian infrastructure developer and EPC contractor focused primarily on roads, with diversification into railways, metro, tunnels, power transmission, oil & gas, BESS and warehousing, operating a portfolio of 43 projects across HAM, BOT, DBFOT and EPC models and executing both construction and asset development roles since 1995. The company delivered a strong Q1 FY27 with standalone revenue of ~INR2,423 crores, up 32.7% year-on-year, and consolidated revenue of INR2,784 crores up 40% year-on-year; however, standalone adjusted EBITDA margins compressed to about 11%, driven by higher construction and material costs including diesel and energy-linked inputs. Balance-sheet strength remains a key feature: standalone debt-to-equity is extremely low at 0.03x, consolidated leverage is moderate at 0.55x, net worth increased sequentially, and the company holds an order book of INR25,300 crores plus ~INR32,000 crores of bids pending opening, underpinning multi-year execution visibility. Strategic diversification is underway across several capital-intensive verticals: management is executing BESS civil works, growing its T&D capability with transmission tower manufacturing, targeting INR1,000 crore-plus in oil & gas revenue for FY27, and plans to deploy significant equity (~INR3,300 crores) into HAM/BoT projects over the next three years. Monetization and liquidity management are active priorities: the company has transferred assets to Indus Infra Trust and received ~INR70 crores distribution this quarter, targets 3–4 further asset transfers this year, and plans to use monetized capital to fund BoT and new project bids while retaining conservative standalone leverage.
Over the past 52 weeks, G R Infraprojects Ltd has traded between a low of ₹738.00 and a high of ₹1,209.45. The 52-week high and low indicate the stock’s price range over the last year and help investors understand its volatility and recent trading levels.
G R Infraprojects Ltd has a market capitalization of approximately 7,691.01. Market capitalization represents the total value of a company’s outstanding shares and helps investors understand its size, stability, and relative risk compared to other listed companies.
G R Infraprojects Ltd’s investment profile depends on its business fundamentals, valuation, and long-term outlook. The stock currently trades at a PE ratio of 7.57 and operates in the its sector sector. Investors typically assess financial performance, growth prospects, and individual risk tolerance before making investment decisions.
Based on its market capitalization of 7,691.01 Cr, G R Infraprojects Ltd is classified as a Small Cap stock. Large-cap stocks are generally more stable, while mid-cap and small-cap stocks tend to offer higher growth potential along with higher price volatility.
G R Infraprojects Ltd operates in the its sector sector. Sector classification matters because companies in the same sector are often affected by similar economic conditions, regulatory changes, and competitive dynamics, which can influence overall stock performance.
The Price-to-Earnings (PE) ratio of G R Infraprojects Ltd is 7.57. The PE ratio compares a company’s share price to its earnings and is commonly used to assess valuation. Comparing the PE ratio with sector peers and historical levels provides better context.
The company said appointed dates for three projects totaling ₹7,250 crore are awaited, and the discussion referenced one Agra-Gwalior project and two HAM projects.
It terminated EPC contracts for Battery Energy Storage System (BESS) implementation at NTPC’s Mouda Super Thermal Power Station in Maharashtra under Lot-1.
The show cause notice proposes an aggregate GST demand of ₹321.60 crore, inclusive of tax, interest, and penalty.
The proposed GST demand in the show cause notice is ₹321.60 crore, comprising tax, interest, and penalty.


| Symbol | Watchlist | Price | Market Cap | P/E | P/B | Div Yield (%) | ROE (%) | ROCE (%) | ROA (%) |
633.35 | 8,766 Cr | 22.90 | 3.13 | 0.46 | 13.09 | 15.75 | 4.75 | ||
327.55 | 8,719 Cr | 15.75 | 1.42 | 1.68 | 9.83 | 12.59 | 2.20 | ||
218.00 | 8,018 Cr | 55.82 | 1.47 | 0.92 | 5.29 | 9.72 | 0.75 | ||
794.85 | 7,691 Cr | 7.57 | 0.82 | 0.31 | 9.63 | 12.39 | 6.33 | ||
116.30 | 7,302 Cr | 9.76 | 0.93 | 1.89 | 8.58 | 14.97 | 2.88 | ||
2125.60 | 6,720 Cr | 15.98 | 2.67 | 0.07 | 14.45 | 18.44 | 7.52 | ||
869.10 | 6,390 Cr | 20.44 | 2.34 | 0.69 | 3.98 | 10.15 | 3.01 | ||
| Median: 7 Co. | — | 633.35 | 7,691 Cr | 15.98 | 1.47 | 0.69 | 9.63 | 12.59 | 3.01 |