










63 Moons Technologies Limited auditors retain NSEL qualification
Key highlights
- Auditors retained a qualified conclusion for the quarter and six months ended September 30, 2026.
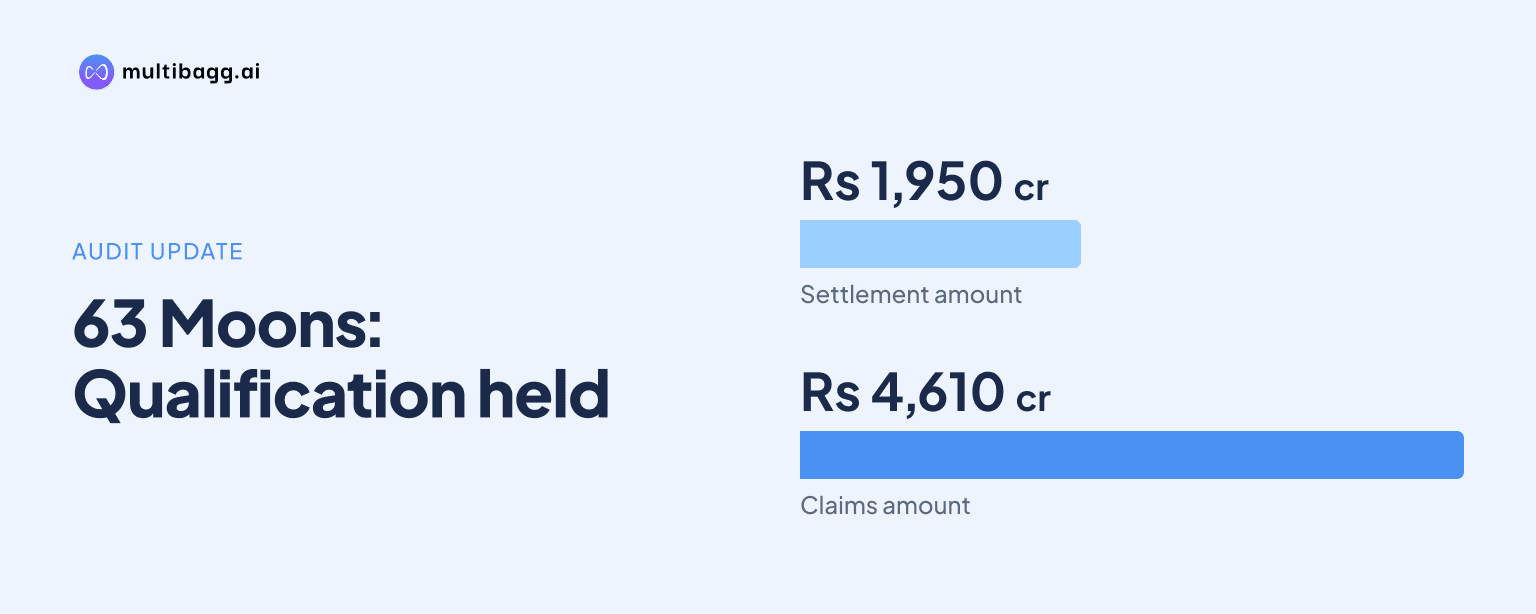
- The NSEL scheme provides for a Rs 1,950 crore settlement of approximately Rs 4,610 crore of claims.
- Fixed deposits of Rs 252.5566 crore were realised and transferred to the settlement account.
- Interest income of Rs 15.4405 crore was recognised on those deposits in the September 2026 quarter.
powered by IRIS
63 Moons Technologies Limited retained a qualified limited-review conclusion for the quarter and six months ended September 30, 2026, because auditors could not quantify the consequences of unresolved NSEL-linked cases or assess recovery of balances awaiting confirmation and reconciliation. The qualification remains despite a Rs 1,950 crore settlement scheme sanctioned in November 2025.
Know 63 Moons Technologies inside out
Results, valuation, peers and who's buying, in one view.
Why did 63 Moons retain a qualified conclusion?
63 Moons retained the qualified conclusion because its auditors could not comment on the consequential financial impact of legal matters whose outcomes remained unknown at September 30, 2026. Civil suits concerning events on National Spot Exchange Limited’s trading platform, alongside investigations and proceedings involving various authorities, were pending at different stages of adjudication or investigation.
The auditors did not identify a quantified provision, charge or loss in the September 2026 quarter or six-month results. Instead, they relied on management and governance representations that, apart from matters disclosed in Note 7, no additional claims or litigation required adjustment or disclosure, while saying the uncertain outcomes prevented them from assessing any resulting effect on the results.
The conclusion arose from a limited review under Standard on Review Engagements 2410, not a full statutory audit. The November 4, 2026 report says a review provides moderate assurance and is substantially narrower than an audit under Standards on Auditing, so the auditors did not express an audit opinion while retaining their qualified conclusion.
Which NSEL legal matters are still unresolved?
The unresolved matters include civil suits, First Information Reports, complaints, charge-sheets, orders and notices involving 63 Moons and other parties. The September 30, 2026 review names the Economic Offences Wing of Mumbai Police, Central Bureau of Investigation, Maharashtra Home Department under the Maharashtra Protection of Interest of Depositors Act, Directorate of Enforcement and Serious Fraud Investigation Office among the bodies involved.
Management stated that parties bringing civil suits would not be able to sustain claims against 63 Moons. After the National Company Law Tribunal, Mumbai sanctioned the scheme, 63 Moons filed applications to dispose of the suits, and orders for disposal, dismissal or withdrawal were passed in the respective cases; however, the auditors said the wider investigations and adjudications still had uncertain outcomes.
63 Moons also applied for release of assets under the Maharashtra Protection of Interest of Depositors Act and the Prevention of Money Laundering Act, 2002. The court allowed those asset-release applications, but that procedural outcome did not remove the qualification because the report continued to cite legal matters and investigations that had not reached final resolution by September 30, 2026.
Why could auditors not assess NSEL balance recoverability?
The auditors said National Spot Exchange Limited’s other receivables, loans, advances and deposits were subject to confirmation and reconciliation, leaving them unable to form an opinion on recoverability. National Spot Exchange Limited management did not expect material changes from the exercise, and legal notices had been sent to counterparties in many cases in earlier years.
This balance issue is separate from the uncertain legal outcomes cited for the quarter and half year ended September 30, 2026. The legal qualification addresses possible effects from litigation and investigations, while the balance qualification addresses whether recorded receivables, loans, advances and deposits can be confirmed, reconciled and recovered; the report gives no amount for the balances on which no recoverability opinion was formed.
The parent auditor reproduced National Spot Exchange Limited’s qualified-conclusion basis because it was significant under Institute of Chartered Accountants of India guidance. That subsidiary report says writ petitions, public-interest litigation, civil suits and regulatory matters were before different forums, and notes that adverse outcomes could expose the group to civil or criminal liabilities.
Got a follow-up? Ask IRIS
How does the Rs 1,950 crore settlement scheme work?
The scheme provides for 63 Moons to pay Rs 1,950 crore towards settlement of approximately Rs 4,610 crore of claims from 5,682 specified creditors. The creditors are traders with outstanding claims above Rs 10 lakh, and the February 18, 2025 board approval contemplated settlement in proportion to claims outstanding on July 31, 2024.
On payment, the scheme envisages closure of proceedings against 63 Moons and persons in the 63 Moons group, discharge from specified creditors’ claims and removal of restraints on dealing with properties. In exchange, the specified creditors’ claims would be assigned to 63 Moons, under the statutory arrangement mechanism in the Companies Act, 2013.
The National Company Law Tribunal sanctioned the scheme on November 28, 2025. Challenges by some traders were dismissed by the National Company Law Appellate Tribunal and subsequently by the Supreme Court, but the November 4, 2026 report says 63 Moons was still taking necessary steps before courts and tribunals to give effect to the arrangement.
What settlement funds and subsidiary results were reported?
Fixed deposits of Rs 252.5566 crore relating to attached assets were realised and transferred to the settlement account under the scheme and designated-court orders. Interest of Rs 15.4405 crore on those deposits was recognised as interest income in the quarter ended September 30, 2026, but the report does not say this transfer resolved the qualified matters.
The review also distinguished between three domestic subsidiaries reviewed by their own auditors and eight subsidiaries whose information was not reviewed by independent auditors. The reviewed subsidiaries reported much larger September-quarter assets and revenue, while the management-certified group information reported a smaller loss; this difference describes review coverage and does not quantify the NSEL balances under reconciliation.
For the reviewed domestic subsidiaries, other comprehensive income was Rs 22.22 lakh in the September 2026 quarter. For the management-certified subsidiaries, comprising four domestic and four foreign entities, other comprehensive income was nil; the parent auditor said this information was not material to the group, while its conclusion on those amounts was based on management-certified statements and reviewed conversion adjustments for the foreign entities.
Conclusion
The qualified conclusion means 63 Moons’ September 2026 consolidated results remain subject to two unresolved areas: financial consequences that may arise from NSEL-linked legal matters and the recoverability of National Spot Exchange Limited receivables, loans, advances and deposits that await confirmation and reconciliation. The Rs 1,950 crore scheme has progressed through tribunal and Supreme Court challenge stages, but it has not eliminated the audit qualification.
The next disclosed development to watch is implementation of the scheme after its November 28, 2025 sanction, including further court or tribunal action to give it effect. Updates on asset releases, any further transfers to the settlement account, and confirmations or reconciliations of outstanding National Spot Exchange Limited balances would address the matters the auditors could not quantify as of September 30, 2026.