










ABFRL Q2 EBITDA Margin Falls to 3.3% Amid Expansion Costs
Key highlights
- ABFRL’s Q2 FY27 revenue rose 2% to Rs 2,030 crore, while EBITDA fell 43% to Rs 67 crore.
- ABFRL’s Q2 FY27 EBITDA margin declined to 3.3% from 5.9% a year earlier.
- ABFRL’s H1 FY27 revenue grew 6% to Rs 4,056 crore, but EBITDA declined 18% to Rs 233 crore.
- ABFRL operated 1,268 stores across 7.8 million square feet in September 2026.
powered by IRIS
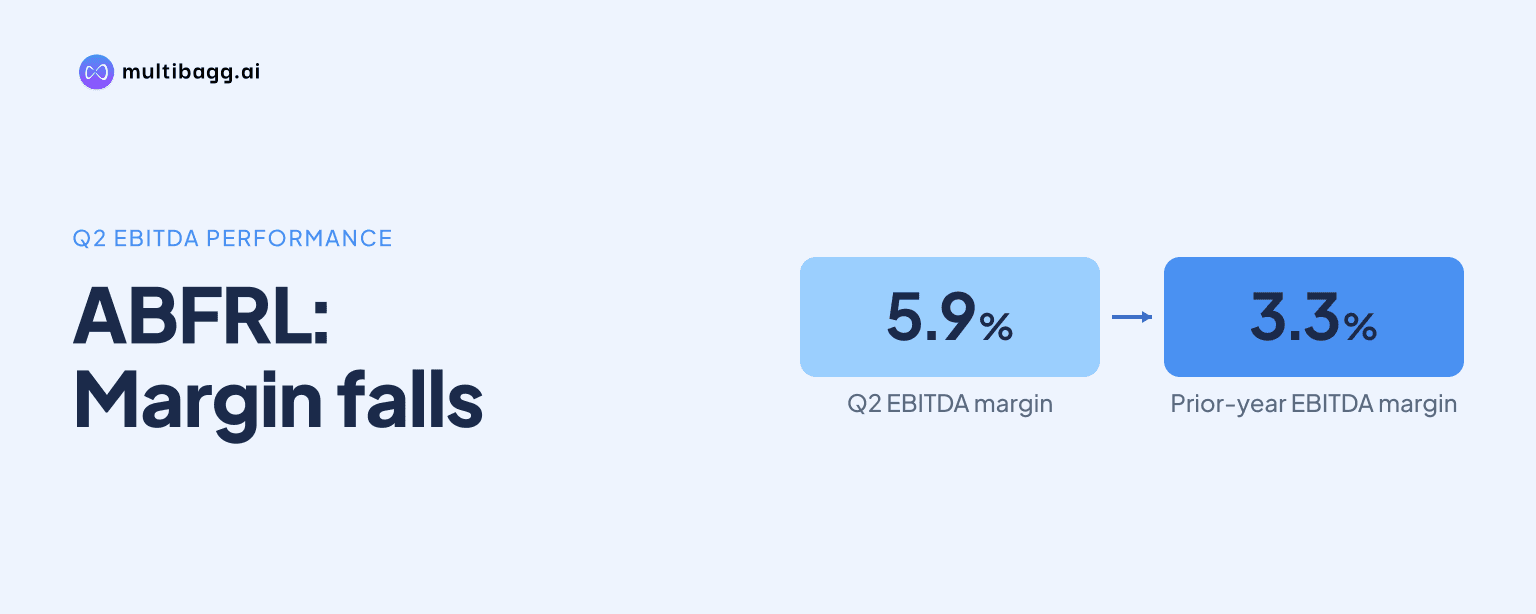
Aditya Birla Fashion & Retail reported a Q2 FY27 EBITDA margin of 3.3%, down from 5.9% a year earlier, after EBITDA fell 43% to Rs 67 crore despite 2% revenue growth to Rs 2,030 crore. ABFRL attributed the decline to festive-shift-led negative operating leverage and the scale-up of OWND and Galleries Lafayette.
Know Aditya Birla Fashion & Retail inside out
Results, valuation, peers and who's buying, in one view.
Why did ABFRL’s Q2 EBITDA margin fall to 3.3%?
ABFRL’s Q2 FY27 EBITDA margin fell to 3.3% because revenue growth did not cover the effect of the festive shift and investments in newer businesses. Revenue increased by Rs 48 crore, from Rs 1,982 crore in Q2 FY26 to Rs 2,030 crore in Q2 FY27, while EBITDA fell by Rs 49 crore, from Rs 116 crore to Rs 67 crore. The margin therefore declined by 2.6 percentage points from 5.9%.
ABFRL said festive timing created negative operating leverage, while the scale-up of OWND and Galleries Lafayette also affected the quarterly margin. The effect extended beyond EBITDA: earnings before interest and tax, or EBIT, widened to a loss of Rs 303 crore from a loss of Rs 209 crore. Profit before tax, or PBT, widened to a loss of Rs 454 crore from Rs 333 crore, and profit after tax, or PAT, widened to a loss of Rs 376 crore from Rs 295 crore.
Which ABFRL segments affected Q2 profitability?
Pantaloons accounted for the largest reported segment-level EBITDA reduction, with EBITDA falling Rs 38 crore to Rs 119 crore in Q2 FY27. Its revenue was broadly unchanged at Rs 1,140 crore, compared with Rs 1,142 crore in Q2 FY26, and its EBITDA margin declined to 10.5% from 13.7%. ABFRL said Pantaloons growth would have been about 10% year on year after adjusting for festive impact and store closures, compared with reported flat revenue.
Ethnic Businesses increased revenue 2% to Rs 517 crore but moved from an EBITDA loss of Rs 1 crore to a loss of Rs 17 crore. The segment’s margin changed from negative 0.3% to negative 3.3%. ABFRL said the ethnic portfolio, excluding TCNS, grew 12% despite a subdued wedding calendar and the festive shift, while profitability reflected timing effects and investments in designer brands.
TMRW recorded a different pattern, with revenue rising 10% to Rs 244 crore and EBITDA loss narrowing to Rs 41 crore from Rs 62 crore. Its EBITDA margin improved to negative 16.8% from negative 27.9%. In Others, revenue rose 11% to Rs 158 crore, but EBITDA declined to Rs 12 crore from Rs 35 crore and margin fell to 7.6% from 24.7%, reflecting Galleries Lafayette scale-up and lower treasury income, according to ABFRL.
Got a follow-up? Ask IRIS
How did ABFRL’s H1 FY27 performance compare with Q2?
ABFRL’s H1 FY27 revenue rose 6% to Rs 4,056 crore, but EBITDA declined 18% to Rs 233 crore and margin fell to 5.7% from 7.5%. The H1 margin remained above the Q2 FY27 margin of 3.3%, showing that the second quarter had a larger effect on the half-year profitability profile. H1 revenue increased by Rs 243 crore from Rs 3,813 crore in H1 FY26.
The first-half loss measures also widened despite the increase in revenue. EBIT was a loss of Rs 486 crore in H1 FY27, against a loss of Rs 355 crore a year earlier, while PBT widened to a loss of Rs 775 crore from Rs 593 crore. PAT was a loss of Rs 625 crore, compared with a loss of Rs 529 crore in H1 FY26.
Where did ABFRL continue to grow despite margin pressure?
ABFRL reported growth in newer businesses even as their scale-up featured in its explanation for lower margins. TMRW revenue grew 10% in Q2 FY27 and 11% in H1 FY27, while its H1 EBITDA loss narrowed by Rs 42 crore to Rs 83 crore. Luxury grew 11% in Q2 and 20% in H1, supported by the ramp-up of Galleries Lafayette and growth in The Collective and Mono brands business.
OWND scaled 58% year on year in Q2 FY27, according to ABFRL, while the ethnic portfolio excluding TCNS grew 12% in Q2 and 13% in H1. ABFRL added 35 gross stores across brands during Q2 and more than 80 stores in H1. Expansion was led by TMRW brands, TCNS and the masstige and value segment.
ABFRL’s network stood at 1,268 stores covering 7.8 million square feet in September 2026, compared with 1,190 stores and 7.5 million square feet in September 2025. Pantaloons remained the largest H1 reported segment, with Rs 2,344 crore of revenue, but its EBITDA fell Rs 33 crore to Rs 311 crore and margin declined to 13.3% from 15.4%. This contrasted with TMRW’s narrowing losses and Ethnic Businesses, where H1 revenue grew 3% but EBITDA moved to a loss of Rs 17 crore.
Conclusion
ABFRL’s Q2 FY27 result shows that 2% consolidated revenue growth was insufficient to maintain profitability when festive timing reduced operating leverage and the company continued to scale OWND and Galleries Lafayette. EBITDA fell 43% to Rs 67 crore, quarterly margin declined to 3.3%, and EBIT, PBT and PAT losses widened. The H1 trend was similar, with EBITDA down 18% despite 6% revenue growth.
The next disclosed markers are whether the approximately 10% festive-adjusted growth cited for Pantaloons in Q2 and H1 converts into reported sales, and whether newer businesses sustain loss reduction as they expand. ABFRL’s more than 80 H1 store additions, its 1,268-store network as of September 2026, Galleries Lafayette scale-up and lower treasury income remain relevant to future profitability disclosures.