










Abhinav Leasing & Finance Gets BSE Nod for ₹6 Crore Warrants
Key highlights
- BSE granted Abhinav Leasing in-principle approval on October 27, 2026, for 6 crore convertible warrants.
- The preferential warrant issue is priced at ₹1 per warrant and can raise up to ₹6 crore.
- Each of the four proposed non-promoter allottees will receive 1.5 crore warrants.
- Warrant holders must pay 25% initially and may convert within 18 months from allotment.
powered by IRIS
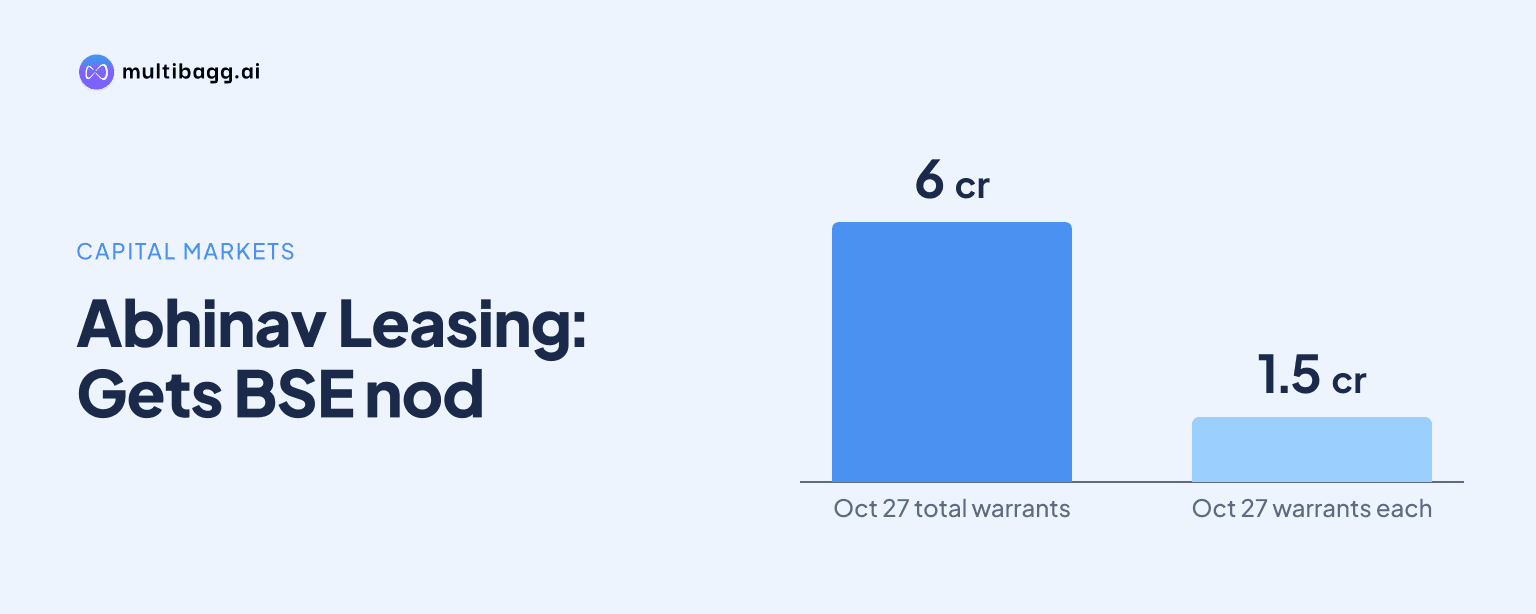
Abhinav Leasing & Finance Limited received BSE in-principle approval on October 27, 2026, to issue 6 crore convertible share warrants at ₹1 each, representing a potential ₹6 crore preferential fund raise for working capital. The approval enables the company to proceed with the proposed allotment to four non-promoter entities, subject to the stated terms.
Know Abhinav Leasing & Finance inside out
Results, valuation, peers and who's buying, in one view.
When did Abhinav Leasing receive BSE approval for the warrants?
Abhinav Leasing informed BSE on October 28, 2026 that it had received in-principle approval a day earlier for the preferential issue. The approval was communicated through BSE letter LOD/PREF/MV/FIP/1021/2026-27 dated October 27, 2026, under Regulation 28(1) of the SEBI Listing Obligations and Disclosure Requirements Regulations, 2015.
The exchange approval follows the company’s shareholder approval at its 42nd Annual General Meeting on September 16, 2026. Shareholders approved the preferential warrant proposal with 99.96% of votes in favour. The AGM also considered an increase in authorised share capital and the re-appointment of director Atul Kumar Agarwal.
A corrigendum dated October 5, 2026 revised the relevant date to August 17, 2026 and reopened e-voting for 48 hours. The company stated that the procedural change related to the proposed capital raise. Its disclosures identified August 20, 2026 as the warrant-issue event date in the corporate action timeline.
What are the terms of Abhinav Leasing’s preferential warrant issue?
Abhinav Leasing proposes to issue 6 crore convertible share warrants on a preferential basis at ₹1 per warrant, aggregating to ₹6 crore. Each warrant carries the right to subscribe to one fully paid-up equity share with a face value of ₹1.
The warrants are proposed to be issued at par, with no premium attached. The ₹1 issue price was above the recalculated floor price of ₹0.86 cited in the company’s disclosures. Warrant holders may exercise their conversion right within 18 months from the allotment date.
Investors must pay 25% of the warrant price at the time of allotment. The remaining 75% becomes payable when they exercise the conversion option. On the disclosed terms, the upfront payment represents ₹1.5 crore across the proposed issue, while the balance is payable on conversion.
Who will receive Abhinav Leasing’s proposed warrants?
Abhinav Leasing has proposed to allot the warrants equally among four non-promoter entities. Amrabathi Investra Private Limited, Masatya Technologies Private Limited, Vardan Ceqube India Investment Fund and Panafic Industrials Limited are each proposed to receive 1.5 crore warrants.
Vardan Ceqube India Investment Fund is identified as a Qualified Institutional Buyer in the disclosed information. The other three proposed allottees - Amrabathi Investra Private Limited, Masatya Technologies Private Limited and Panafic Industrials Limited - are classified as non-QIB entities. Together, the four allottees account for the entire 6 crore warrant issue.
The company has described all the proposed allottees as non-promoter entities. The transaction is a preferential allotment rather than a rights issue, meaning existing public shareholders do not receive an entitlement to subscribe under the disclosed proposal.
Got a follow-up? Ask IRIS
How could the warrant conversion affect Abhinav Leasing’s capital structure?
If all 6 crore warrants are exercised, Abhinav Leasing will issue an equivalent number of new equity shares. The supplied disclosures indicate that the number of shares could rise from about 5 crore before the issue to roughly 11 crore after full conversion, subject to the stated capital structure.
The company’s disclosures also indicate that promoter holding could decline from 3.66% before the issue to 1.66% after full conversion. This reflects dilution resulting from the issuance of new shares to non-promoter warrant holders. The reported public ownership was approximately 83.9% before the proposed conversion.
The company has designated the proceeds exclusively for working capital requirements. The full ₹6 crore would be available only if the warrants are exercised and the remaining 75% payment is made. Until conversion, the warrant structure provides the proposed holders an option to subscribe to equity within the 18-month period.
Why does the BSE approval matter for investors?
The BSE approval is an exchange-level step that allows Abhinav Leasing to move forward with the preferential issue after its shareholder approval. It does not by itself confirm that every warrant will be allotted, exercised or converted. The final equity expansion depends on the warrant holders exercising their conversion rights under the disclosed terms.
For investors, the principal financial considerations are the potential ₹6 crore working-capital funding and the possible expansion in the equity base. Since the issue is priced at ₹1 per warrant, the allotment and later conversion could materially alter the ownership mix if all securities are converted. The company has not disclosed any use of proceeds beyond working capital in the provided information.
Conclusion
Abhinav Leasing has secured BSE in-principle approval for a ₹6 crore preferential issue of 6 crore convertible warrants at ₹1 each. The proposal follows strong shareholder approval and identifies four non-promoter allottees, each proposed to receive 1.5 crore warrants. The warrants can convert into an equal number of equity shares within 18 months.
Investors will watch the allotment, the receipt of the initial 25% payment, and whether the holders exercise the warrants before the conversion period ends. The key unresolved matter is the extent of conversion, which will determine the final capital raised and the resulting dilution in Abhinav Leasing’s shareholding structure.