










ACC Q2 FY27 Results: Profit Falls 92% Despite Capacity
Key highlights
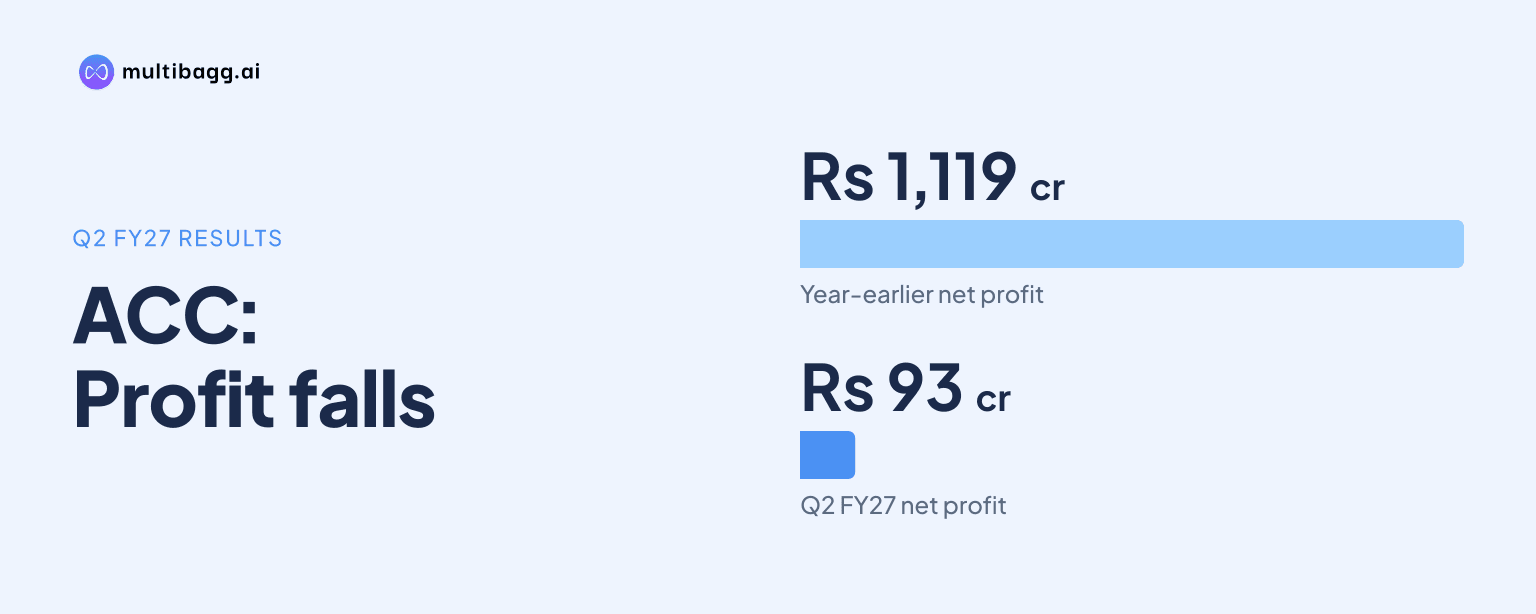
- ACC’s Q2 FY27 consolidated net profit fell 91.7% year-on-year to ₹93 crore from ₹1,119 crore.
- Consolidated revenue from operations declined 5.1% year-on-year to ₹5,666 crore in Q2 FY27.
- ACC’s operating margin narrowed to 2.1% in Q2 FY27 from 12.2% a year earlier.
- ACC reported 9.7 million tonnes of cement sales, a 78% trade share and 47% premium-product share within trade sales.
powered by IRIS
Quarter at a glance
ACC Ltd reported consolidated net profit of ₹93 crore for the quarter ended September 30, 2026, marking a 91.7% year-on-year decline from ₹1,119 crore. Profit was also lower than ₹147 crore reported in the preceding quarter. Consolidated revenue from operations was ₹5,666 crore, down 5.1% year-on-year and 2.1% sequentially, according to the BSE results filing. Total income stood at ₹5,796 crore, compared with ₹6,229 crore in the year-ago period. The results were approved by ACC's Board of Directors on October 27, 2026. The company submitted its unaudited standalone and consolidated financial results, along with the statutory auditors' limited review report, to the stock exchanges.
Know ACC inside out
Results, valuation, peers and who's buying, in one view.
Profit decline reflects lower operating performance
The quarter saw a substantial reduction in operating profitability. Profit before exceptional items and tax was ₹195 crore, against ₹763 crore in Q2 FY26 and ₹224 crore in Q1 FY27. Operating profit declined 83.7% year-on-year and 48.5% quarter-on-quarter, based on the reported filing data. The operating margin was 2.1%, compared with 12.2% in the corresponding quarter last year and 3.4% in the previous quarter. This decline in the underlying operating result came before accounting for exceptional items.
Exceptional charge reduced pre-tax profit
ACC reported exceptional items of ₹71 crore during Q2 FY27, compared with ₹24 crore in Q1 FY27 and no exceptional items in Q2 FY26. The supplied results update identifies this as a voluntary separation scheme, or VSS, charge. After the exceptional item, profit before tax was ₹124 crore. This was lower than ₹200 crore in the preceding quarter and ₹763 crore a year earlier. The reported consolidated net profit of ₹93 crore therefore reflected both weaker operating performance and the exceptional charge.
Revenue figures reported across disclosures
The exchange-results table records revenue from operations of ₹5,666 crore. ACC's Q2 FY27 media update separately cited revenue from operations of ₹5,689 crore. Both disclosures point to lower revenue than the year-ago quarter, although the percentage comparison differs slightly because of the reported base figures. The company also reported standalone revenue of ₹5,635 crore and standalone net profit of ₹101 crore. The supplied material does not provide a reconciliation for the difference between the revenue figures in the various summaries.
Sales volume and trade mix improved
ACC reported cement sales volume of 9.7 million tonnes in Q2 FY27. Its trade share increased to 78%, indicating a higher contribution from the trade channel. Premium products accounted for 47% of trade sales during the quarter. These operating indicators were highlighted in the company's media release alongside the financial results. They show the company's focus on product mix and distribution even as reported revenue and profit declined year-on-year.
Got a follow-up? Ask IRIS
New cement capacity commissioned
The company commissioned 3.4 million tonnes per annum, or MTPA, of additional cement capacity at Salai Banwa and Kalamboli. Another supplied update referred to 2.4 MTPA of new capacity being online, while ACC's media release highlighted 3.4 MTPA commissioned capacity. The 3.4 MTPA figure is the capacity addition stated in the company update. Capacity expansion is relevant for a cement producer because it increases the ability to serve demand across its operating markets. However, ACC did not provide earnings-call guidance for the quarter in the supplied material.
Ambuja merger process moves to NCLT
ACC also said that the proposed merger with Ambuja Cements had advanced to the National Company Law Tribunal, or NCLT. The update confirms a procedural step in the merger process. No timeline for an NCLT decision or completion of the transaction was provided in the supplied information. Investors will therefore need to rely on future company and regulatory disclosures for further developments. The merger process remains separate from the quarter's reported operational and financial performance.
Key Q2 FY27 financial data
What the quarter means for investors
ACC's Q2 FY27 result was marked by lower revenue, a sharp contraction in operating margin and a significant fall in net profit. The company nevertheless reported higher trade-channel participation, a greater premium-product share within trade sales, and additional commissioned capacity. These factors relate to its sales mix and production footprint, but the reported quarter did not include management guidance through an earnings-call transcript. The disclosed numbers remain reported results rather than an outlook for future performance.
Upcoming disclosures to watch
ACC's earnings presentation was scheduled for October 29, 2026, according to the company calendar included in the supplied information. Future disclosures may provide further details on capacity ramp-up, trade mix, merger proceedings and financial performance. For now, the reported Q2 FY27 outcome shows a quarter of lower profitability alongside ongoing operational expansion. The next formal company updates will be relevant for assessing changes in these reported trends.