










Accel auditors retain qualification over Rs 3.15 crore gap
Key highlights
- Accel carried its Secureinteli investment at Rs 4.88 crore on 30 September 2026.
- An independent valuation dated 28 February 2025 valued the investment at Rs 1.73 crore.
- The disclosed carrying amount exceeded the independent valuation by Rs 3.15 crore.
- The issue was also qualified in the 30 June 2026 review and the 31 March 2026 audit.
powered by IRIS
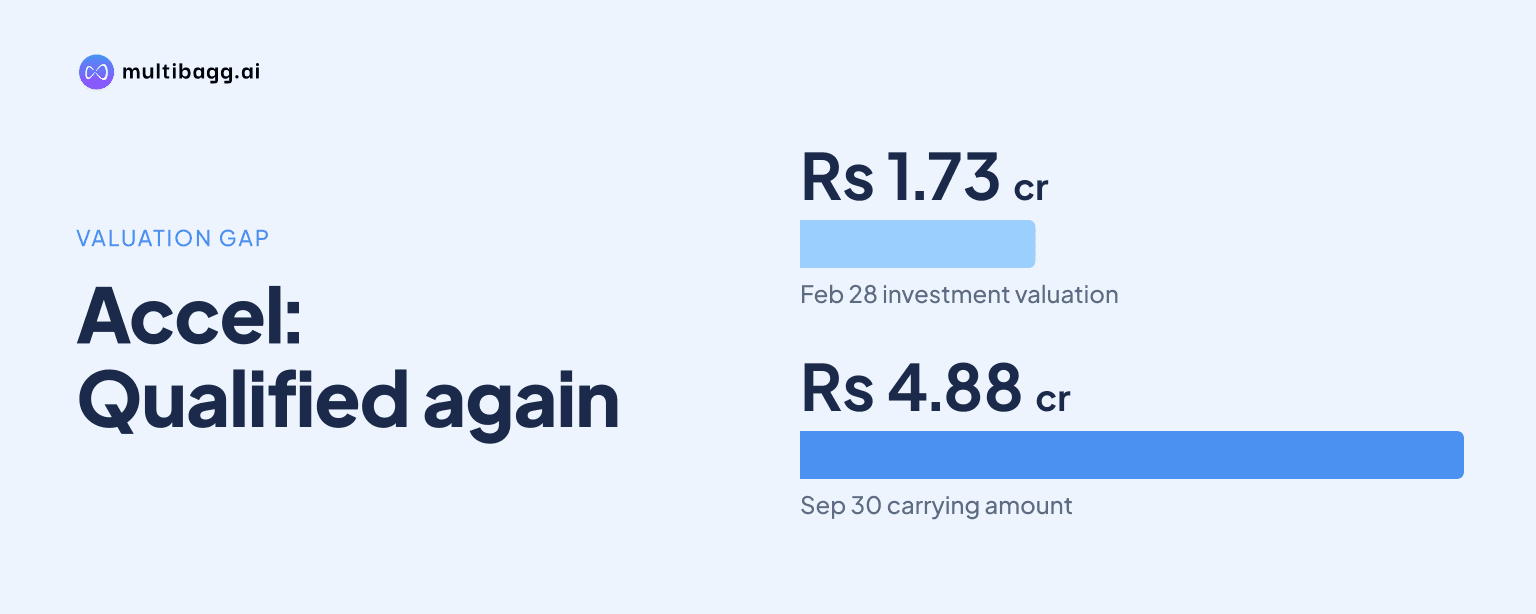
Accel Limited received a continuing qualified conclusion for the quarter and half year ended 30 September 2026 because it carried its Secureinteli Technologies Private Limited investment at Rs 4.88 crore, compared with an independent valuation of Rs 1.73 crore dated 28 February 2025, a Rs 3.15 crore difference.
Know Accel inside out
Results, valuation, peers and who's buying, in one view.
Why did Accel receive a qualified conclusion?
Accel received the qualified conclusion because Menon & Pai said it lacked sufficient appropriate evidence to support management’s assessment of the recoverable value of the associate investment as at 30 September 2026. The auditors therefore could not determine whether an adjustment was needed to the Rs 4.88 crore carrying amount or the resulting effect on the unaudited financial results.
Management’s stated view is that the investment had suffered no impairment or diminution in value and should remain recorded at Rs 4.88 crore. The auditor did not state that a write-down was definitely required, nor did it quantify any required adjustment; its qualification concerns the absence of enough evidence to assess management’s position.
The Board approved the unaudited standalone and consolidated results on 13 November 2026, the date Menon & Pai issued its review reports. The review was performed under Standard on Review Engagements 2410, which the auditor said is narrower in scope than an audit and does not provide assurance that all significant matters would be identified.
How large is Accel’s Secureinteli valuation difference?
Accel’s disclosed carrying value exceeded the independent valuation by Rs 3.15 crore, based on the Rs 4.88 crore amount at 30 September 2026 and the Rs 1.73 crore valuation in the 28 February 2025 report. The filing identifies Secureinteli Technologies Private Limited as an associate in the consolidated-review report.
The independent valuation was not recognised as the investment’s carrying amount in the 30 September 2026 results. Menon & Pai referred to the valuation in both its standalone and consolidated reports, while management continued to say that no impairment or diminution was necessary.
The qualification is about whether the recorded amount is recoverable, rather than an instruction to adopt the Rs 1.73 crore valuation automatically. The reports do not disclose the valuation methodology, management’s supporting assumptions, or an alternative value that the auditors believe should be used.
Got a follow-up? Ask IRIS
Has Accel faced this qualification before?
Yes. Menon & Pai said predecessor auditors had qualified the standalone limited-review report for the quarter ended 30 June 2026 and the audit report for the year ended 31 March 2026 over the same matter. The issue was therefore still unresolved at the 30 September 2026 reporting date.
The qualification’s recurrence spans reports issued after the independent valuation dated 28 February 2025. The source does not provide a revised valuation, an impairment charge, or a date by which management will submit further evidence supporting the Rs 4.88 crore carrying value.
Menon & Pai’s qualified conclusion nevertheless said that, except for the possible effects of this matter, nothing had come to its attention indicating that the statements failed to make disclosures required under Regulation 33 of the Securities and Exchange Board of India’s Listing Obligations and Disclosure Requirements Regulations, 2015. That wording applies to the 30 September 2026 limited review, not to an audit opinion.
What does Accel’s consolidated review disclose?
Accel’s consolidated review lists Cetronics Technologies Private Limited as a subsidiary and Secureinteli as an associate. It includes the group’s share of the associate’s net profit after tax for the quarter and half year ended 30 September 2026, although the filing does not state that share’s amount in the review report.
Consolidated total assets rose to Rs 183.65 crore at 30 September 2026 from Rs 176.67 crore at 31 March 2026, an increase of Rs 6.98 crore. Consolidated equity was Rs 68.89 crore at 30 September 2026, compared with Rs 68.44 crore at 31 March 2026.
Menon & Pai also noted that the subsidiary’s financial results and the associate’s share of profit were consolidated from information supplied by their respective managements and had not been reviewed by the firm. The auditor explicitly said its conclusion was not modified for that separate matter, distinguishing it from the valuation-based qualification.
Conclusion
Accel’s 30 September 2026 reports retain a qualification because management kept the Secureinteli investment at Rs 4.88 crore despite an independent valuation of Rs 1.73 crore, creating a Rs 3.15 crore disclosed difference. The auditors have not concluded that a specific impairment is required, but say they cannot determine the necessary adjustment without sufficient appropriate evidence.
The next point to watch is whether a later financial statement provides evidence supporting the Rs 4.88 crore carrying value or records an adjustment. The matter had already produced qualifications in the 30 June 2026 review and the 31 March 2026 audit, while the 13 November 2026 filing gives no timetable for its resolution.