










Addictive Learning shifts Rs 5.2132 crore to working capital
Key highlights
- Addictive Learning reallocated Rs 5.2132 crore of IPO proceeds to working-capital requirements on September 28, 2026.
- Addictive Learning had Rs 7.2132 crore unutilised from its Rs 57.918 crore fresh issue at September 30, 2026.
- The revised working-capital allocation was Rs 13.2132 crore, of which Rs 8 crore had been used.
- Shareholders extended use of Rs 2 crore for an identified acquisition through financial year 2027-28.
powered by IRIS
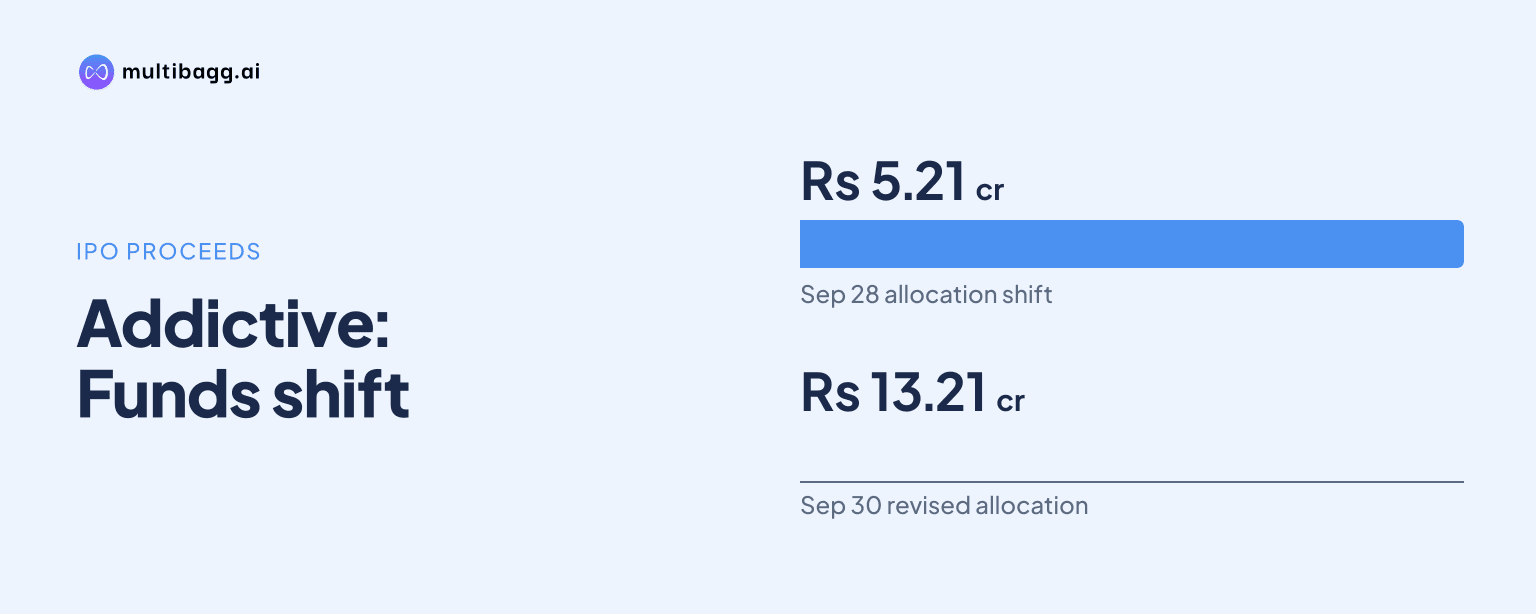
Addictive Learning Technology Limited reallocated Rs 5.2132 crore of IPO proceeds to working-capital requirements after shareholders approved the change on September 28, 2026, taking that allocation to Rs 13.2132 crore. Addictive Learning had Rs 7.2132 crore unutilised from its Rs 57.918 crore fresh issue at September 30, 2026.
Know Addictive Learning Technology inside out
Results, valuation, peers and who's buying, in one view.
How did Addictive Learning reallocate its IPO proceeds?
Addictive Learning moved Rs 5.2132 crore from unutilised allocations for an unidentified acquisition and issue expenses into working-capital requirements through the shareholder resolution of September 28, 2026. The original Rs 5 crore allocation for an unidentified acquisition in India and abroad was reallocated in full. The remaining Rs 21.32 lakh under issue expenses was also transferred, making up the Rs 5.2132 crore change.
The reallocation increased the working-capital allocation from Rs 8 crore in the offer document to Rs 13.2132 crore, without changing the Rs 57.918 crore gross proceeds or the total revised allocation. Addictive Learning had used Rs 8 crore of the working-capital allocation by September 30, 2026, leaving the newly reallocated Rs 5.2132 crore unutilised. KRA & Co., the statutory auditor, certified that the disclosed utilisation figures had been extracted from the books and records it examined.
The shareholder action changed the planned use of money rather than the fresh-issue size. The unidentified-acquisition category, initially allotted Rs 5 crore, had no revised allocation or balance at September 30, 2026. Similarly, the revised issue-expense allocation stood at Rs 10.1105 crore, all of which had been used by the reporting date.
What IPO money remained unspent at Addictive Learning?
Addictive Learning had Rs 7.2132 crore of unutilised fresh-issue proceeds at September 30, 2026, comprising Rs 5.2132 crore for working capital and Rs 2 crore for an identified acquisition. It had used Rs 50.7048 crore of the Rs 57.918 crore raised through the fresh issue. Working capital accounted for about three quarters of the amount still to be deployed, while the identified-acquisition allocation accounted for the balance.
The Rs 2 crore for the identified acquisition was not redirected. Addictive Learning had spent Rs 1 crore from the original Rs 3 crore allocation by September 30, 2026, and shareholders approved an extension to use the remaining amount through financial year 2027-28. The filing does not identify the acquisition target or provide a transaction date within that extended period.
The utilisation schedule shows that Rs 31.5943 crore had been fully spent across technology investment, new-course development, branding and marketing, and general corporate purposes. Those four original objects had no balance at September 30, 2026. The two remaining uses of IPO proceeds were therefore the enlarged working-capital pool and the identified-acquisition allocation whose deadline now extends to financial year 2027-28.
Got a follow-up? Ask IRIS
Which Addictive Learning IPO objectives were fully used?
Addictive Learning had fully used Rs 8 crore for investment in technology, Rs 5 crore for development of new courses, Rs 10 crore for branding and marketing expenses, and Rs 8.5943 crore for general corporate purposes by September 30, 2026. These four purposes together represented Rs 31.5943 crore of the Rs 57.918 crore fresh issue. The disclosure records no unutilised amount in any of these categories.
Issue expenses were also fully utilised after the Rs 21.32 lakh reallocation. Addictive Learning spent Rs 10.1105 crore against the revised issue-expense allocation of Rs 10.1105 crore, compared with the original Rs 10.3237 crore provision. The full Rs 5 crore previously marked for an unidentified acquisition was transferred to working capital, so that category had neither a revised allocation nor an unspent balance at September 30, 2026.
The filing identifies Education Technology, or EdTech, as the group’s sole reportable business segment under Accounting Standard 17. It says the group primarily operates in India and receives an insignificant portion of revenue from exports and overseas subsidiaries. No geographical segment met the quantitative thresholds for separate disclosure, so the IPO-use schedule is not split between Indian and overseas operations.
What financial results did Addictive Learning report with the IPO update?
Addictive Learning reported revenue from operations of Rs 47.9814 crore for the half year ended September 30, 2026, up from Rs 41.8893 crore in the corresponding half year ended September 30, 2025. Profit after tax declined to Rs 2.5985 crore from Rs 4.1627 crore, while profit before tax fell to Rs 3.4618 crore from Rs 5.7687 crore. The period therefore showed higher revenue but lower profit than a year earlier.
For the quarter ended September 30, 2026, revenue from operations was Rs 25.2926 crore, compared with Rs 22.6888 crore in the quarter ended June 30, 2026 and Rs 20.9629 crore in the quarter ended September 30, 2025. Quarterly profit after tax was Rs 2.2859 crore, versus Rs 31.26 lakh in the preceding quarter and Rs 2.8777 crore a year earlier. Addictive Learning said it voluntarily began publishing quarterly results as well as half-yearly results from financial year 2026-27.
Cash and cash equivalents increased to Rs 4.7592 crore at September 30, 2026 from Rs 1.1671 crore at March 31, 2026. Net cash from operating activities for the half year was Rs 9.5574 crore, while investing activities used Rs 5.9653 crore, including Rs 7.1188 crore for fixed-asset purchases. The financial statements recorded no cash flow from financing activities for the half year.
Conclusion
Addictive Learning’s September 28, 2026 shareholder resolution redirected Rs 5.2132 crore from an unidentified acquisition and unused issue-expense provision to working capital. By September 30, 2026, the company had deployed Rs 50.7048 crore of its Rs 57.918 crore fresh issue, with completed spending in technology, course development, branding and marketing, general corporate purposes, and revised issue expenses.
The next disclosed milestone is the extended financial year 2027-28 deadline for the Rs 2 crore remaining for the identified acquisition. Investors can also monitor subsequent quarterly or half-yearly disclosures for deployment of the Rs 5.2132 crore still earmarked for working capital, which was the largest component of the Rs 7.2132 crore unutilised balance at September 30, 2026.