










Ahluwalia Contracts (India) profit falls 28.6% despite growth
Key highlights
- Ahluwalia Contracts reported Q2 FY27 revenue of ₹1,463.66 crore, up 24.32% year on year.
- Q2 FY27 net profit was ₹56.09 crore, down 28.61% year on year but up about 439.9% sequentially.
- Operating margin excluding other income recovered to 7.58% from 4.29% in Q1 FY27 but remained below 10.93% in Q2 FY26.
- Ahluwalia Contracts reported latest ROCE of 25.62%, against a 31.27% assessment-period average.
powered by IRIS
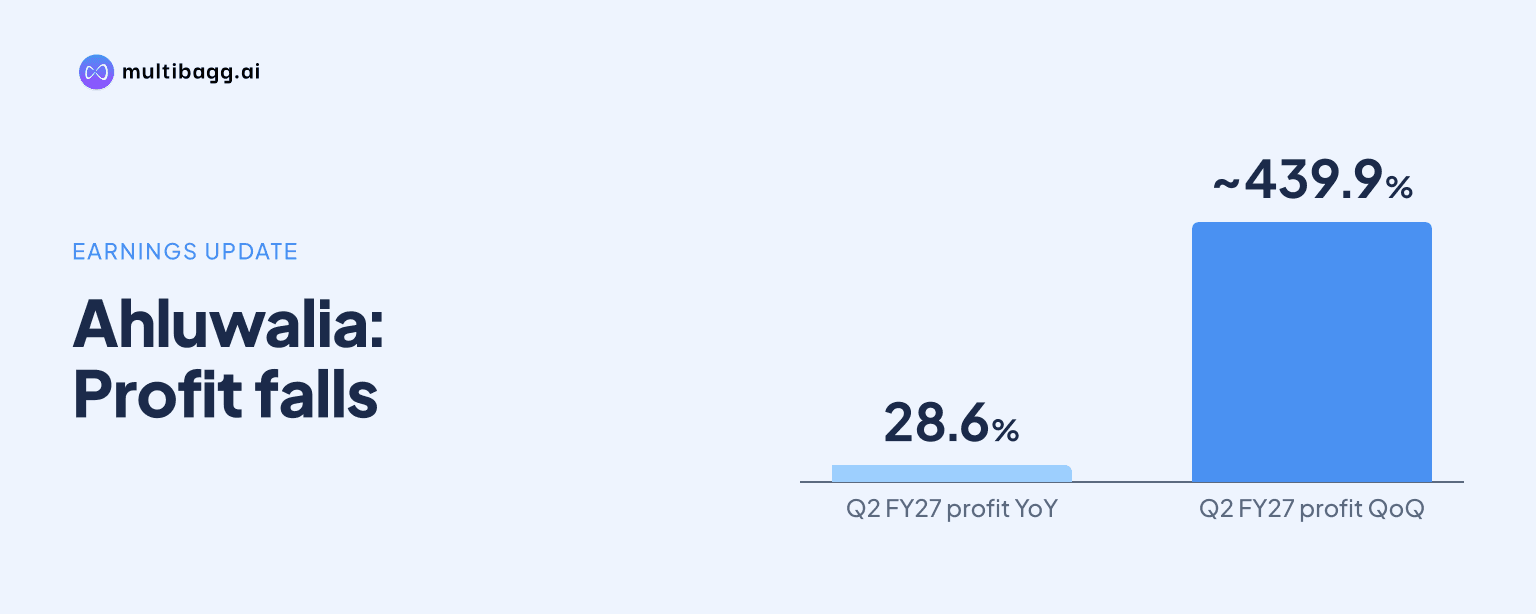
Ahluwalia Contracts (India) Ltd reported a 28.61% year-on-year fall in Q2 FY27 net profit to ₹56.09 crore, even as revenue from operations increased 24.32% to ₹1,463.66 crore. The July-September quarter showed stronger project execution and a sequential earnings recovery, but lower margins kept profit below the previous year's level.
Know Ahluwalia Contracts (India) inside out
Results, valuation, peers and who's buying, in one view.
What did Ahluwalia Contracts report for Q2 FY27?
Ahluwalia Contracts reported consolidated revenue from operations of ₹1,463.66 crore for Q2 FY27, compared with ₹1,177.30 crore in Q2 FY26 and ₹1,125.80 crore in Q1 FY27. Revenue rose 24.32% year on year and 30.01% sequentially, making it the company's highest quarterly revenue in its recent history according to the reported results.
Net profit stood at ₹56.09 crore, down from ₹78.57 crore a year earlier. However, profit recovered sharply from ₹10.39 crore in the preceding quarter, representing sequential growth of about 439.9%. Profit before tax was ₹75.6 crore, against ₹105.9 crore in Q2 FY26 and ₹14.3 crore in Q1 FY27.
The contrast between revenue and profit is central to the quarter. Ahluwalia Contracts executed a larger volume of work during the period, but the improvement in sales did not translate into a comparable year-on-year rise in earnings. Reported exceptional items were nil.
Why did revenue growth not lift profit at the same pace?
Ahluwalia Contracts' operating margin excluding other income improved to 7.58% in Q2 FY27 from 4.29% in Q1 FY27, indicating a substantial sequential recovery. Yet the margin remained below 10.93% in Q2 FY26, a year-on-year contraction of 335 basis points.
Operating profit declined to ₹110.94 crore from ₹128.63 crore despite the increase in revenue. This reflects the effect of lower profitability per rupee of sales compared with the corresponding quarter last year. EBITDA margin was reported at about 7.6%, compared with about 10.9% in Q2 FY26.
The profit after tax margin also narrowed to 3.83% from 6.67% a year earlier, a contraction of 284 basis points. The company did not publish an earnings-call transcript for the quarter in the supplied material, so the reported results do not provide detailed management commentary on the specific cost or project-level factors behind the margin change.
Got a follow-up? Ask IRIS
How does Q2 compare with the previous quarter and last year?
Q2 FY27 was materially stronger than Q1 FY27 on a sequential basis, with revenue rising by ₹337.86 crore and net profit increasing by ₹45.70 crore. The recovery followed a weak first quarter, when the operating margin excluding other income was 4.29% and net profit was ₹10.39 crore.
The year-on-year comparison remains less favourable. Revenue expanded by ₹286.36 crore, but net profit fell by ₹22.48 crore. Profit before tax declined by about ₹30.3 crore from Q2 FY26, while operating profit declined by ₹17.69 crore.
What do the returns and board changes mean for investors?
Ahluwalia Contracts reported an average return on equity of 13.87% over the assessment period cited in the material. Its average return on capital employed was 31.27%, while the latest ROCE was 25.62%. These figures indicate that the company continued to generate returns from its operating capital, although the latest ROCE was below the stated assessment-period average.
For investors, the quarter presents two separate trends: revenue execution improved strongly and profitability recovered from Q1 FY27, while year-on-year margin and profit performance remained weaker. The earnings per share decline to ₹8.37 from ₹11.73 also tracks the fall in consolidated net profit.
The board also appointed Sanjay Bharti as Company Secretary and Compliance Officer, effective 14 November 2026. He succeeded Vipin Kumar Tiwari. The limited review reports cited in the results did not identify any matter indicating a material misstatement.
What should investors monitor after the Q2 FY27 results?
Investors should monitor whether Ahluwalia Contracts can sustain higher revenue execution while improving the operating margin from the 7.58% reported in Q2 FY27. The company delivered a meaningful sequential margin recovery, but the gap with the 10.93% margin recorded in Q2 FY26 remains significant.
The next quarterly filing will be relevant for assessing whether the Q2 profit rebound can be maintained and whether revenue growth converts more effectively into operating profit and net profit. The supplied material does not provide management guidance, a future revenue target, or a scheduled earnings-call discussion.
Conclusion
Ahluwalia Contracts delivered its strongest recent quarterly revenue of ₹1,463.66 crore in Q2 FY27, supported by a 30.01% sequential increase in sales. But operating profit, net profit and key margins remained below Q2 FY26 levels, showing that higher execution alone did not offset the year-on-year profitability pressure.
The next results will show whether the sequential improvement in operating margin from 4.29% to 7.58% can continue. Investors will also watch the gap between revenue growth and profit growth, as no detailed management guidance or project-level explanation for the margin movement was disclosed in the supplied material.