










AIL's share reaches about 42% after certification reset
Key highlights
- AIL reported about 42% India video-surveillance share in the 12 months to September 2026, up from 30% at its FY25 IPO.
- AIL said more than 100 CP PLUS models were STQC security-certified as certified-camera rules took effect from April 2025.
- AIL reported in-house manufacturing capacity of 2.5 million units a month for certified supply.
- AIL guided for FY27 market share of 43% to 45%, after reporting about 42% in the trailing 12 months.
powered by IRIS
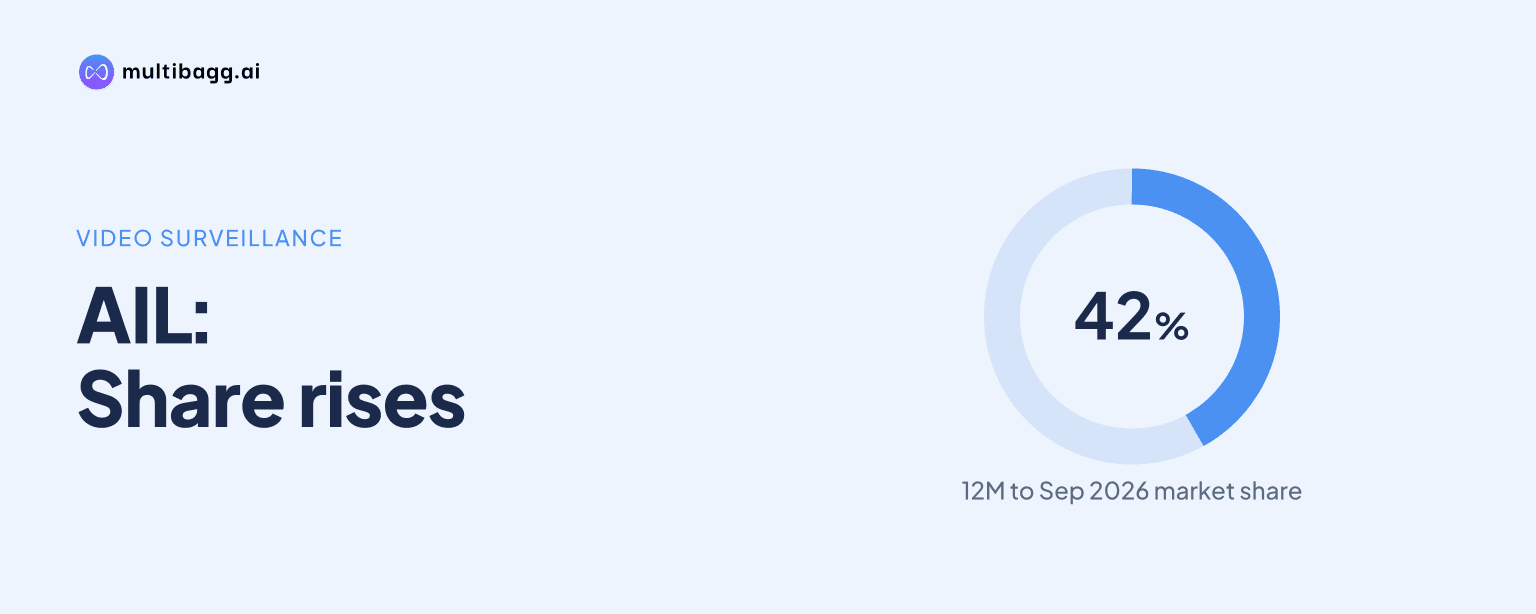
Aditya Infotech Limited said its share of India’s video-surveillance market reached about 42% in the 12 months to September 2026, rising from 30% at its FY25 initial public offering (IPO). AIL attributes the increase to certified CP PLUS products, 2.5 million units of monthly manufacturing capacity and nationwide distribution during an industry compliance transition.
Know Aditya Infotech inside out
Results, valuation, peers and who's buying, in one view.
How much market share has AIL gained since its IPO?
AIL said it gained roughly 12 percentage points of India video-surveillance market share, from 30% at its FY25 IPO to about 42% in the 12 months to Q2 FY27, which ended in September 2026. Its presentation puts share at about 34% in FY26, indicating that the increase accelerated after FY26.
AIL’s 43% to 45% FY27E share range is management guidance rather than a reported outcome. From the approximately 42% trailing-12-month result, that range implies a further gain of about 1 to 3 percentage points. AIL identifies manufacturing scale, research and development, distribution and brand as factors behind its position.
The company’s share calculation is set against a market estimated at Rs 10,620 crore in FY25, Rs 12,370 crore in FY26 and Rs 15,000 crore in FY27. AIL attributes the FY25 figure to Frost & Sullivan. It describes the FY26 figure as interpolated from Frost & Sullivan growth while accounting for an under-indexed unorganised segment, while the FY27 figure is a company estimate.
Why did certification rules help AIL take share?
AIL said higher industry standards favoured CP PLUS because it had certified products and supply capacity as camera requirements tightened between April 2024 and March 2026. Security rules were notified in April 2024, original equipment manufacturers (OEMs) could sell only certified cameras from April 2025, and the sell-off of uncertified cameras ended in March 2026.
AIL does not quantify the share increase caused directly by the rules. However, it says more than 100 CP PLUS models were Security Testing and Certification (STQC) security-certified, providing the base to bring certified supply to market first. The company presents that portfolio as a differentiator during the compliance-led market reset.
Manufacturing and distribution were the other mechanisms AIL cited. It reported in-house plant capacity of 2.5 million units a month, ready to ramp certified supply, and said its nationwide distribution put compliant products on shelves first. The March 2026 deadline is significant because it ended the permitted sale of uncertified inventory.
What capabilities does AIL say supported the gain?
AIL attributes its share gain to in-house manufacturing, own firmware, in-house design, distribution reach and the CP PLUS brand. Its stated evidence includes more than 100 STQC-certified models and plant capacity of 2.5 million units a month, both of which were available through the April 2025 to March 2026 certification transition.
AIL also describes a multi-brand portfolio across price points and deeper component localisation as part of its operating model. It identifies PRO in the premium segment, which it estimates at about 10% of the market. NEXIVIEW and EYRA are intended to address the unorganised market, although the presentation does not provide revenue, volume or market-share splits for those brands.
The company also cites own firmware and multi-system-on-chip (multi-SoC) designs as technology enablers. On 5 November 2026, AIL signed agreements to invest Rs 45.4 crore for a 30% stake in BLUE, subject to customary conditions. AIL says BLUE’s compression technology can reduce storage and bandwidth by up to 90%, based on BLUE company data.
Got a follow-up? Ask IRIS
Is AIL funding capacity growth while expanding market position?
AIL said it is funding capacity and product expansion through a Rs 1,500 crore qualified institutional placement (QIP) and had net cash of Rs 1,071.2 crore at 30 September 2026. The QIP involved 4.33 million shares issued at Rs 3,467 each, while net proceeds were Rs 1,465.5 crore.
Of the net QIP proceeds, Rs 325 crore is allocated to repaying or prepaying borrowings of AIL and AIL Dixon, Rs 650 crore to capital expenditure at AIL Dixon’s Kadapa Phase III and Knowledge Park plant, and Rs 490.5 crore to acquisitions and general corporate purposes. At 30 September 2026, AIL reported cash and cash equivalents of Rs 1,433.9 crore and total borrowings of Rs 362.7 crore, before saying debt was fully repaid in October.
The funding programme accompanied rapid H1 FY27 growth. Revenue was Rs 3,148 crore, up 89.7% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) rose 192.7% to Rs 515 crore. EBITDA margin increased 580 basis points year on year to 16.3%, while net working-capital days declined to 72 from 78 in FY26.
Profit after tax before exceptional items was Rs 362 crore in H1 FY27, up 252.0% year on year. Reported profit after tax was Rs 327.7 crore after a Rs 34.4 crore fire loss at AIL Dixon. In Q2 FY27, revenue was Rs 1,746 crore and profit after tax before exceptional items was Rs 219.9 crore.
What does AIL expect next in surveillance?
AIL has guided for FY27 market share of 43% to 45% and estimates India’s video-surveillance market will rise from Rs 15,000 crore in FY27 to Rs 26,000 crore by FY30. The company describes this market path as approximately 20% compound annual growth, and both market-size figures are company estimates.
AIL’s disclosed plan has four parts: defend and increase core-market share, serve premium and unorganised segments, add manufacturing capacity at Kadapa Phase III and Greater Noida, and enter exports through original design manufacturer partnerships in about 18 months. It also identifies localisation, multi-SoC designs and BLUE’s compression technology as enablers, without providing a timetable for product launches or export revenue.
Conclusion
AIL’s reported rise from 30% share at its FY25 IPO to about 42% in the 12 months to September 2026 coincided with the April 2025 certified-camera requirement and the March 2026 end of uncertified sell-offs. The company attributes the gain to its certified CP PLUS range, manufacturing capacity and distribution network, alongside a market that it estimates expanded from Rs 10,620 crore in FY25 to Rs 15,000 crore in FY27.
The next measures to watch are management’s FY27 guidance of 43% to 45% share, deployment of Rs 650 crore of QIP proceeds at Kadapa Phase III and the Knowledge Park plant, and the planned export entry in about 18 months. Completion of the Rs 45.4 crore BLUE investment remains subject to customary conditions.