










Aimtron Electronics Limited H1 FY27 Revenue Climbs 83%
Key highlights
- Aimtron Electronics reported H1 FY27 consolidated revenue of ₹224.71 crore, up 83.3% year on year.
- H1 FY27 profit after tax rose 71.5% year on year to ₹34.79 crore.
- Aimtron India revenue increased about 69% to ₹161.56 crore from ₹95.60 crore.
- Aimtron Electronics plans a ₹205 crore preferential raise to fund two acquisitions.
powered by IRIS
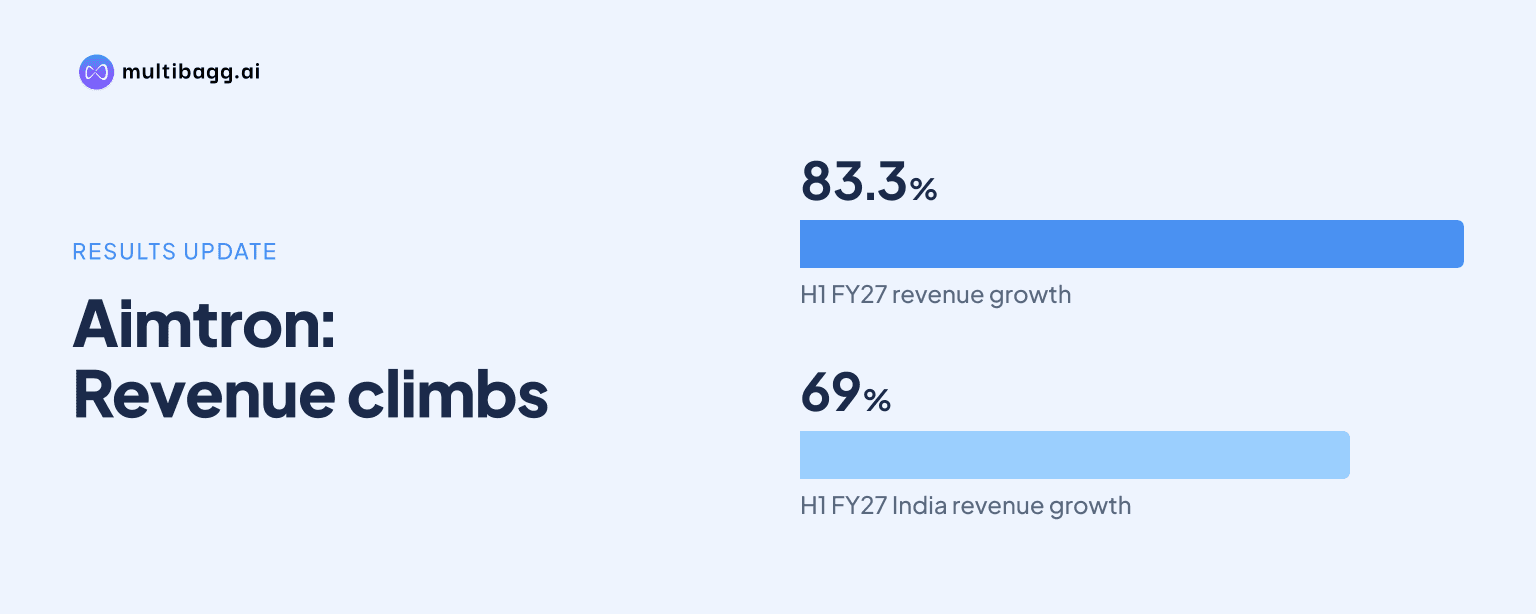
Aimtron Electronics Limited reported consolidated H1 FY27 revenue of ₹224.71 crore, up 83.3% year on year, while profit after tax rose 71.5% to ₹34.79 crore for the six months ended September 2026. The performance matters because the company is pursuing rapid organic and acquisition-led expansion while addressing pressure on consolidated operating margins.
Know Aimtron Electronics inside out
Results, valuation, peers and who's buying, in one view.
What did Aimtron Electronics report for H1 FY27?
Aimtron Electronics reported sharp year-on-year growth across revenue, operating profit and net profit in H1 FY27. Consolidated revenue from operations reached ₹224.71 crore, compared with the prior-year period, while PAT increased to ₹34.79 crore. The company said EBITDA was ₹48.61 crore, up 61.4% year on year.
Aimtron India revenue was ₹161.56 crore in H1 FY27, compared with ₹95.60 crore in H1 FY26, an increase of about 69%. Management attributed the India business growth to broad programme execution. The disclosed figures show that consolidated revenue grew faster than the India operation during the period.
The earnings call was held on 6 November 2026, with Chairman Mukesh Vasani, Whole-Time Director Sneh Shah and Chief Financial Officer Nikita Shah representing management. The company discussed its H1 performance, growth plans and the effect of integrating AIC into the consolidated business.
Why did Aimtron Electronics' margin come under scrutiny?
Aimtron Electronics acknowledged that the AIC integration affected consolidated margins. Call summaries cited a decline in consolidated EBITDA margin from about 25% to 22%, while management indicated that AIC was targeting margins comparable with the parent business over time.
There is a difference among the figures carried in the available call materials. One summary cited an EBITDA margin of 24.17%, while another reported EBITDA of ₹48.61 crore on revenue of ₹224.71 crore and stated a 21.6% margin, compared with 24.6% a year earlier. The latter percentage is consistent with the reported absolute EBITDA and revenue figures. The materials do not provide a detailed reconciliation for the differing margin references.
Management remained confident about growth but did not provide numerical support in response to questions on margin sustainability. The call materials also identified component shortages and working-capital strain as ongoing operational considerations.
Got a follow-up? Ask IRIS
What is Aimtron Electronics' growth plan?
Aimtron Electronics has set a target of reaching ₹1,000 crore in revenue around FY29 through an indicated organic compound annual growth rate of 40% to 50%. This target provides the framework for the company’s expansion strategy following the strong H1 FY27 revenue increase.
The company has also outlined a ₹205 crore preferential fund raise to finance two acquisitions. Acquisition-led growth can add scale and order opportunities, but the H1 discussion showed that consolidation and integration can also affect reported margins in the near term.
AIC's order book was reported at $18.8 million, up 161%. The order-book increase is relevant to the company’s international and consolidated growth plans, although the call materials did not split consolidated H1 revenue between organic growth and acquired businesses.
How do the results affect investors and operations?
For investors, the central issue is the balance between rapid revenue expansion and profitability. Revenue rose 83.3% and PAT increased 71.5%, but EBITDA expanded at a slower 61.4% pace in the reported figures. This difference is reflected in the lower operating-margin reference in the call summary.
For operations, component availability and working-capital needs remain relevant as the company handles higher programme execution and acquisition integration. These factors can influence procurement, inventory requirements and cash deployment, though the call did not quantify their effect for H1 FY27.
The disclosed ₹205 crore preferential raise is also important because it links planned capital raising directly to two proposed acquisitions. Investors will need to assess future disclosures on the acquisitions, integration progress and the relative contribution of organic and acquired revenue.
Conclusion
Aimtron Electronics delivered strong H1 FY27 growth, with consolidated revenue of ₹224.71 crore and PAT of ₹34.79 crore. However, the results also brought attention to the decline in consolidated EBITDA margin cited in the call materials and the limited numerical explanation of its sustainability.
The next points to watch are the proposed ₹205 crore preferential raise, progress on the two acquisitions and execution toward the company’s stated goal of ₹1,000 crore revenue around FY29. Further disclosures on AIC integration, order conversion and working-capital requirements will provide additional context on the quality of growth.