










Amarnath Securities review qualified over missing records
Key highlights
- Amarnath Securities’ September 30, 2026 review was qualified because RBI-compliance documents were unavailable.
- Loans increased by Rs 18.39 lakh to Rs 20.89 lakh at September 30, 2026.
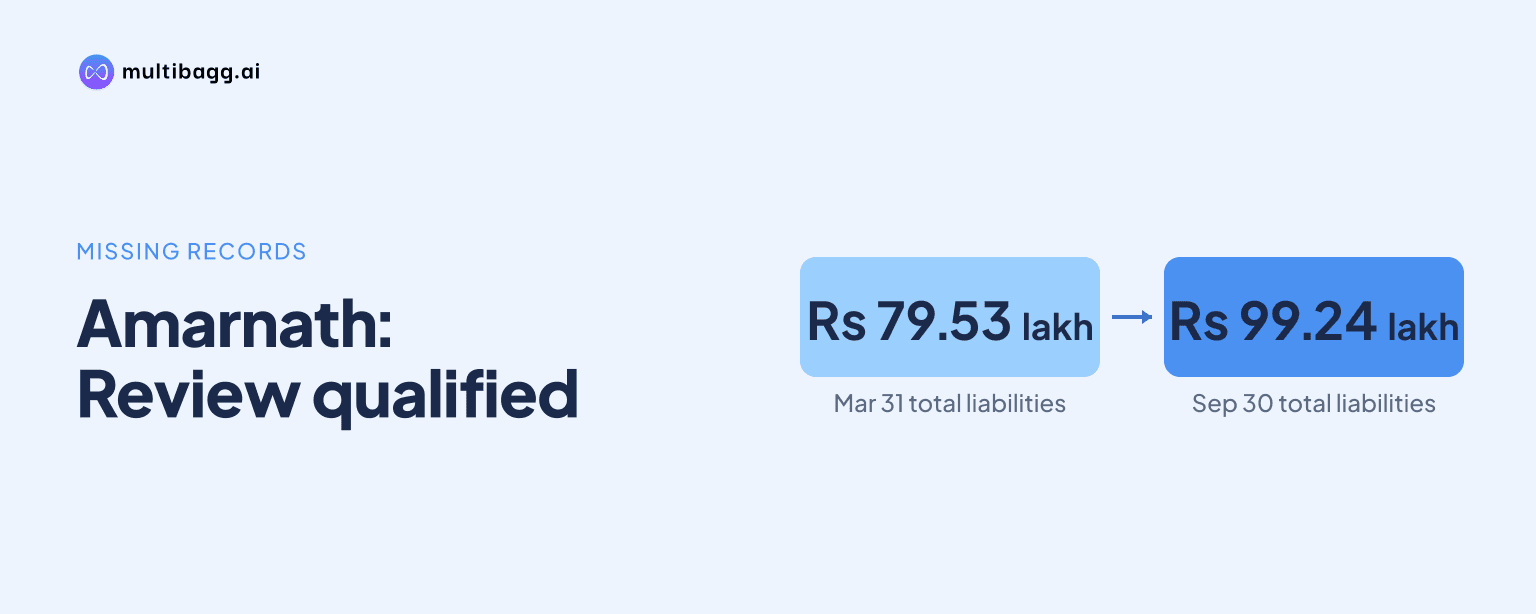
- Total liabilities rose to Rs 99.24 lakh from Rs 79.53 lakh at March 31, 2026.
- The auditor highlighted Rs 6.87 lakh of revenue from a related-party loan write-back.
powered by IRIS
Amarnath Securities Limited received a qualified review conclusion for the quarter and half year ended September 30, 2026, because its auditor lacked Reserve Bank of India compliance records and could not assess their possible effects on the unaudited financial results. The review also cited unavailable loan, investment, liability and expense documentation.
Know Amarnath Securities inside out
Results, valuation, peers and who's buying, in one view.
Why was Amarnath Securities’ September 2026 review qualified?
Amarnath Securities received a qualified conclusion because H K Shah & Co. said documents concerning Reserve Bank of India, or RBI, compliance had not been received from the auditee non-banking financial company, or NBFC, by the date of its November 14, 2026 report. The auditor said it was unable to determine the possible effects, if any, of the missing documents on results for the quarter and half year ended September 30, 2026.
The qualification does not say a misstatement was established. H K Shah & Co. said that, except for the matters in the basis for qualified conclusion, nothing had come to its attention suggesting that the September 30, 2026 statement failed to disclose required information or contained a material misstatement. The review was performed under Standard on Review Engagements 2410, which the auditor said provides less assurance than an audit.
Amarnath Securities disclosed that, after a change in management, it had yet to make an application or intimation to the RBI seeking approval for the change. The company said the approval remained pending as of the November 14, 2026 signing date of the financial statements. The filing does not state a financial effect or a timetable for completing the RBI process.
Which balances could the auditor not verify?
The auditor said Amarnath Securities’ liabilities appeared to have been compromised in light of recent developments, but management had not clarified the details. It was therefore unable to comment on the merits of the issue or quantify its effect on profit or loss, assets and liabilities at September 30, 2026, when total liabilities were reported at Rs 99.24 lakh.
Investment support was also unavailable. H K Shah & Co. said it had not received documents for the Rs 0.51 lakh investment balance and could not verify its existence, ownership, carrying value or presentation. The reported investment balance was Rs 0.51 lakh both at September 30, 2026 and March 31, 2026, with no underlying instrument or counterparty identified in the filing.
Loan and advance agreements were not received for the auditor’s review. As a result, it could not verify loan terms and conditions or assess whether adjustments were required to related balances, interest income, impairment provisions and disclosures. Loans rose to Rs 20.89 lakh at September 30, 2026 from Rs 2.50 lakh at March 31, 2026, an increase of Rs 18.39 lakh.
What expense and governance issues did the review identify?
The auditor said certain expenses could not be verified because documentation was unavailable or limited. It cited rent expense of Rs 0.21 lakh for the quarter ended September 30, 2026, where the leave-and-licence agreement for the premises was in a director’s personal name rather than Amarnath Securities’ name. The auditor could not comment on the company’s right to use the premises or the appropriateness of recording that expense.
Amarnath Securities was also without a whole-time company secretary for part of the quarter under review, according to the report. H K Shah & Co. said it could not determine the extent or consequences of possible secretarial non-compliances. The report further said the previous year’s secretarial audit report had not been received and that no interest had been provided for or paid on share application money, without disclosing an amount.
The auditor separately drew attention to Rs 6.87 lakh of revenue recognised during the quarter from a write-back of a loan amount payable to a related party. It said this recognition followed management’s decision. This was presented as an emphasis of matter, rather than as one of the stated grounds for the qualified conclusion, and the filing gives no earlier carrying value for the payable.
Got a follow-up? Ask IRIS
How did Amarnath Securities’ September figures change from March?
Amarnath Securities reported total assets of Rs 27.10 lakh at September 30, 2026, compared with Rs 6.49 lakh at March 31, 2026. The largest identified change was loans, which increased by Rs 18.39 lakh to Rs 20.89 lakh. Other receivables of Rs 0.62 lakh and other financial assets of Rs 2.81 lakh were reported at September 30, 2026, without comparative balances shown in the extract.
Borrowings increased to Rs 78.55 lakh at September 30, 2026 from Rs 55.95 lakh at March 31, 2026, a rise of Rs 22.60 lakh. The cash-flow statement recorded Rs 22.60 lakh of short- or long-term borrowing during the half year and Rs 0.08 lakh of finance cost, resulting in Rs 22.51 lakh of net cash from financing activities.
Operating activities used Rs 23.70 lakh of cash in the half year ended September 30, 2026, compared with Rs 5.93 lakh of cash generated from operating activities in the year ended March 31, 2026. The cash-flow statement attributed Rs 18.39 lakh to long- and short-term loans and advances, while provisions declined by Rs 3.11 lakh during the half year.
What does the filing show about equity, cash and operations?
Amarnath Securities reported negative equity of Rs 72.13 lakh at September 30, 2026, compared with negative Rs 73.04 lakh at March 31, 2026. Share capital remained Rs 300.02 lakh on both dates, while other equity moved to negative Rs 372.15 lakh from negative Rs 373.06 lakh. H K Shah & Co. also drew attention to the financial statements’ indication that the company’s entire net worth had been eroded.
Cash and cash equivalents were Rs 2.16 lakh in the September 30, 2026 balance-sheet statement, down from Rs 3.48 lakh at March 31, 2026. The cash-flow statement showed closing cash and cash equivalents of Rs 2.18 lakh, comprising Rs 0.06 lakh of cash on hand and Rs 2.12 lakh in current-account balances. The supplied filing does not explain the Rs 0.02 lakh difference between the two reported closing figures.
Amarnath Securities said it operates in one segment, finance and investment, and therefore did not provide segment reporting. It also said it has no subsidiary or associate. The audit committee reviewed, and the board approved, the September 2026 results at its November 14, 2026 meeting.
Conclusion
The qualified September 2026 review leaves several reported matters unquantified: RBI-compliance records were unavailable, liabilities were described as apparently compromised without management clarification, and supporting records for loans, investments and certain expenses were not provided. These documentation limits sit alongside loans of Rs 20.89 lakh, total liabilities of Rs 99.24 lakh and negative equity of Rs 72.13 lakh.
The disclosed next point to watch is Amarnath Securities’ pending RBI application or intimation following the management change, as approval had not been received by November 14, 2026. Subsequent filings may also show whether the company provides the loan agreements, investment records, liability clarification, secretarial audit report and support for the Rs 0.21 lakh quarterly rent expense.