










Andrew Yule’s first-half profit came from associate income
Key highlights
- Andrew Yule reported Rs 1.01 crore first-half profit after Rs 22.50 crore of associate income offset a Rs 21.49 crore post-tax loss.
- Andrew Yule’s loss before tax was Rs 19.08 crore in the half year ended September 30, 2026, against a Rs 25.92 crore profit a year earlier.
- Andrew Yule’s segment revenue rose to Rs 155.34 crore from Rs 127.65 crore, with Electrical-Kolkata contributing Rs 86.49 crore.
- Andrew Yule used Rs 14.37 crore in operating activities, while cash and cash equivalents increased to Rs 36.55 crore.
powered by IRIS
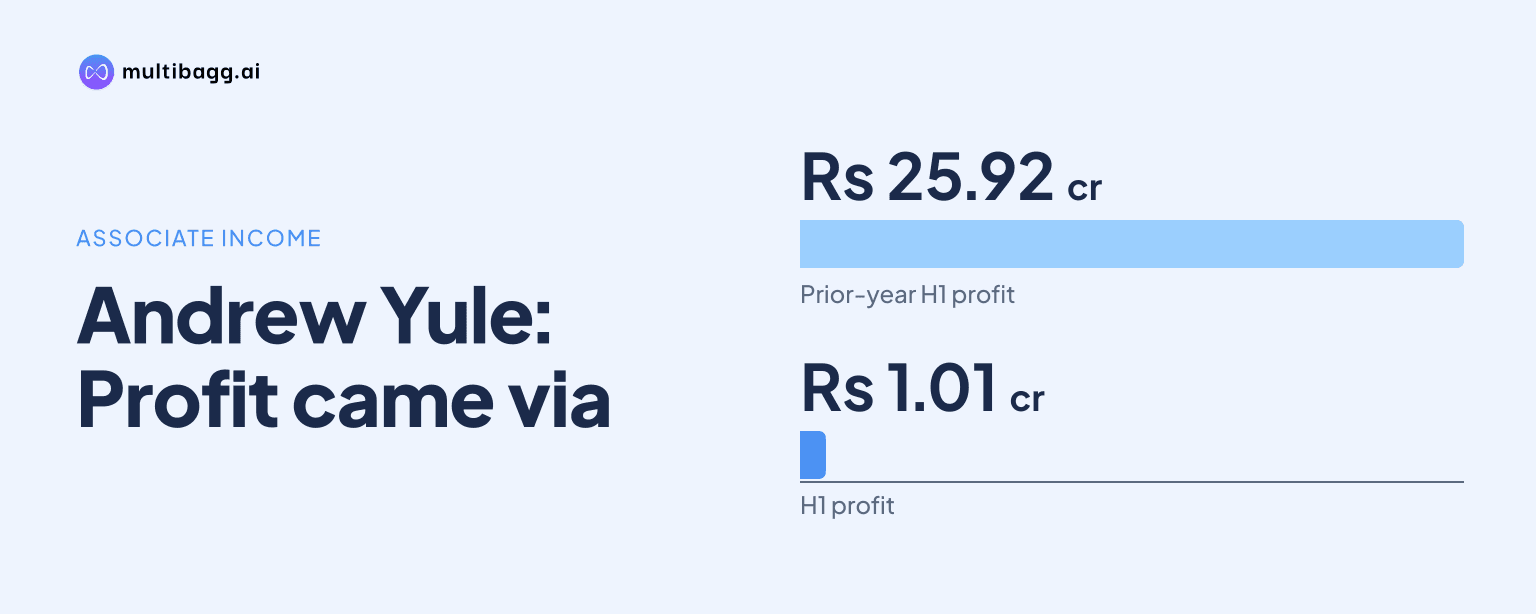
Andrew Yule & Company Limited reported Rs 1.01 crore consolidated profit for the half year ended September 30, 2026, only after booking Rs 22.50 crore as its share of profit from associate Veedol Corporation Limited. Before that contribution, Andrew Yule recorded a Rs 21.49 crore loss after tax, while total comprehensive income was Rs 4.93 crore.
Know Andrew Yule & Company inside out
Results, valuation, peers and who's buying, in one view.
Why did Andrew Yule report a first-half profit?
Andrew Yule reported a Rs 1.01 crore first-half profit because its Rs 22.50 crore share of profit from group companies exceeded its Rs 21.49 crore loss after tax before that line item. The consolidated statement for the half year ended September 30, 2026, records a Rs 19.08 crore loss before tax, followed by Rs 2.41 crore of tax expense and then the associate contribution.
The contribution came from Veedol Corporation Limited, which is listed as Andrew Yule’s associate in the auditor’s annexure. The auditor said the proportionate group share of Veedol Corporation Limited’s total comprehensive income of Rs 22.50 crore for the September 2026 half year was reviewed by another auditor and accounted for in the consolidated results.
Other comprehensive income of Rs 3.92 crore increased total comprehensive income to Rs 4.93 crore, compared with Rs 22.41 crore in the corresponding half year ended September 30, 2025. The reported Rs 1.01 crore profit therefore reflects both the associate’s contribution and items recognised outside profit or loss, rather than a pre-associate operating profit.
How did Andrew Yule’s underlying result change from last year?
Andrew Yule’s loss before exceptional items and tax was Rs 19.08 crore in the half year ended September 30, 2026, compared with a Rs 25.92 crore profit in the corresponding half year a year earlier. The change was Rs 45.00 crore and occurred before the Rs 22.50 crore associate contribution was included in consolidated profit.
The September 2026 half-year result moved from the Rs 19.08 crore pre-tax loss to a Rs 21.49 crore loss after tax because tax expense was Rs 2.41 crore. In the corresponding September 2025 half year, Andrew Yule reported a Rs 22.31 crore loss after tax before recording a Rs 2.01 crore share of loss from group companies.
The segment reconciliation shows Rs 13.62 crore of interest for the September 2026 half year, against Rs 9.40 crore in the corresponding period. Depreciation and amortisation were Rs 10.85 crore, compared with Rs 10.02 crore a year earlier, while unallocable expenditure net of unallocable income was Rs 3.57 crore.
Which Andrew Yule segments increased revenue in the half year?
Andrew Yule’s segment revenue increased to Rs 155.34 crore in the half year ended September 30, 2026, from Rs 127.65 crore in the corresponding period of 2025. Electrical-Kolkata was the largest segment at Rs 86.49 crore, followed by Tea at Rs 45.91 crore and Electrical-Chennai at Rs 22.71 crore.
Electrical-Kolkata revenue rose by Rs 16.79 crore from Rs 69.70 crore a year earlier, while Tea revenue increased by Rs 1.93 crore from Rs 43.98 crore. Electrical-Chennai delivered the largest percentage increase among the main businesses, rising Rs 9.04 crore from Rs 13.68 crore; Engineering revenue fell to Rs 21.71 lakh from Rs 30.19 lakh.
Revenue growth did not produce a consolidated pre-tax profit in the September 2026 half year. Segment results before interest and tax show Electrical-Chennai generated Rs 2.83 crore, while Electrical-Kolkata recorded a Rs 13.37 crore loss, Tea a Rs 40.89 lakh loss and Engineering a Rs 9.02 crore loss.
Got a follow-up? Ask IRIS
What did Andrew Yule’s cash flow show?
Andrew Yule used Rs 14.37 crore in operating activities during the half year ended September 30, 2026, compared with Rs 80.41 crore used during the year ended March 31, 2026. The cash-flow statement starts with the Rs 19.08 crore loss before tax and shows a Rs 5.20 crore operating loss before changes in current assets and liabilities.
Investing activities used Rs 17.09 crore in the September 2026 half year, while financing activities generated Rs 35.28 crore. Consequently, cash and cash equivalents increased by Rs 3.82 crore to Rs 36.55 crore at September 30, 2026, from Rs 32.72 crore at March 31, 2026.
The cash-flow statement includes Rs 22.50 crore as an adjustment for the increase in group share of profit of associates. That adjustment means the associate income recognised in consolidated profit did not represent cash generated from Andrew Yule’s operating activities during the six-month period.
What audit and subsidiary matters accompanied Andrew Yule’s results?
Andrew Yule’s auditor did not modify its limited-review conclusion, but identified two wholly owned subsidiaries as not going concerns under Indian Accounting Standard 1. Yule Engineering Limited and Yule Electrical Limited had no significant transactions or operating activities in the second quarter and half year ended September 30, 2026, as well as in the recent past, according to the auditor.
The auditor also said there was no agreement on repayment terms or interest payable on borrowings from Andrew Yule to those subsidiaries. Together, the subsidiaries had total assets of Rs 5,790 and total comprehensive loss of Rs 85,300 for the relevant period; their respective auditors included emphasis-of-matter paragraphs.
Separately, the auditor disclosed delayed deposits of provident fund, deposit-linked insurance, provident-fund administration charges, gratuity and leave encashment. The disclosed provident-fund liability was Rs 62.55 crore and gratuity was Rs 18.93 crore, while Rs 5.32 crore of penalty or demurrage related to delayed provident-fund payments had not been considered or accounted for.
Andrew Yule provided Rs 71.41 lakh for a Securities and Exchange Board of India penalty for non-compliance with listing regulations, including Rs 10.68 lakh related to the first quarter of 2026-27. The company has requested a waiver of that penalty, according to the auditor’s report dated November 12, 2026.
Conclusion
Andrew Yule’s September 2026 half-year result shows that the reported Rs 1.01 crore profit depended on Rs 22.50 crore of associate income, rather than the group’s own pre-associate result. Revenue increased by Rs 27.69 crore to Rs 155.34 crore, led by Electrical-Kolkata and Electrical-Chennai, but the group still recorded a Rs 19.08 crore loss before tax.
The next disclosures should clarify whether higher segment revenue can reduce the pre-tax loss and whether the associate contribution remains material to reported profit. Investors should also watch for the outcome of Andrew Yule’s request for waiver of the Rs 71.41 lakh SEBI penalty and any accounting or payment developments related to the Rs 5.32 crore provident-fund penalty or demurrage disclosed by the auditor.