










Andrew Yule subsidiaries not going concerns with nil income
Key highlights
- Yule Engineering and Yule Electrical were not going concerns at September 30, 2026.
- The subsidiaries reported nil income and a combined Rs 85,300 loss for both the September 2026 quarter and half year.
- Closure proposals for both subsidiaries were submitted on January 4, 2023.
- The two subsidiaries had combined assets of Rs 5,790 at September 30, 2026.
powered by IRIS
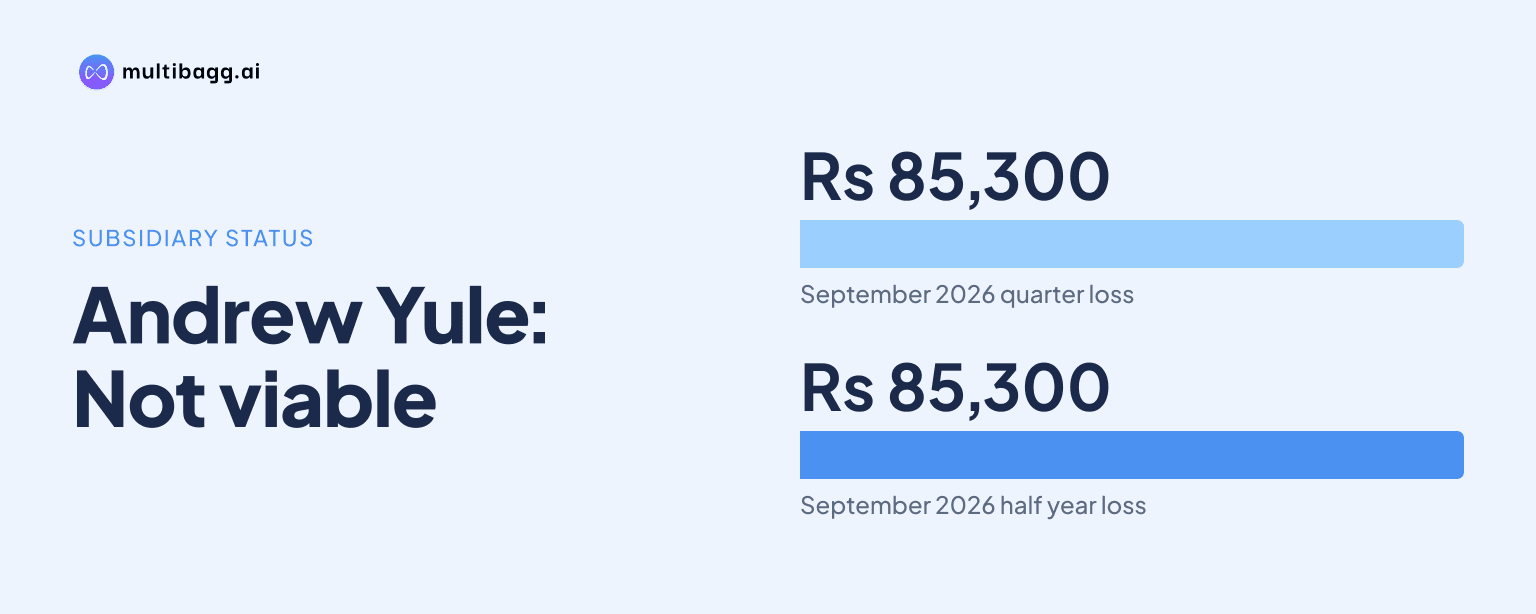
Andrew Yule & Co. Limited’s two wholly owned subsidiaries were not going concerns at September 30, 2026, after reporting nil income and a combined Rs 85,300 net loss for both the quarter and half year, while closure proposals submitted on January 4, 2023 continued to be described as proposals.
Know Andrew Yule & Company inside out
Results, valuation, peers and who's buying, in one view.
Why are Andrew Yule subsidiaries not going concerns?
Andrew Yule’s subsidiaries, Yule Engineering Limited and Yule Electrical Limited, were not going concerns under Indian Accounting Standard 1 because there were no significant transactions or operating activities during the quarter and half year ended September 30, 2026, or in the recent past. The consolidated auditor disclosed this assessment in the Other Matters section of its limited review report dated November 12, 2026.
The filing identifies Yule Engineering and Yule Electrical as Andrew Yule’s two wholly owned subsidiaries in Annexure 1 to the review report. Veedol Corporation Limited is identified separately as an associate, meaning the going-concern observation applies to the two subsidiaries and not to Veedol, whose proportionate group share of total comprehensive income was Rs 22.5023 crore for the half year ended September 30, 2026.
What is the status of Andrew Yule’s closure proposals?
Andrew Yule submitted proposals to close Yule Engineering and Yule Electrical to the Ministry of Heavy Industries, Government of India, on January 4, 2023. The November 12, 2026 review report does not disclose approval, rejection, implementation or a timetable for either proposal, and still refers to them as proposals for closure.
The closure matter remained part of Andrew Yule’s September 2026 reporting package nearly four years after the January 2023 submission. Andrew Yule’s board approved the unaudited consolidated financial results for the quarter and half year ended September 30, 2026 on November 12, 2026, the same date as the auditor’s report that repeated the closure disclosure.
How large were Andrew Yule’s subsidiaries in September 2026?
Andrew Yule’s two subsidiaries together had total assets of Rs 5,790 at September 30, 2026, nil total income, and a combined net loss and total comprehensive loss of Rs 85,300. The auditor reported the same nil-income and Rs 85,300-loss figures for both the second quarter and the half year ended September 30, 2026, indicating no additional reported loss between the quarter-only and half-year disclosures.
The subsidiaries’ nil income contrasts with Andrew Yule’s consolidated net sales or income from operations of Rs 155.3381 crore for the half year ended September 30, 2026, compared with Rs 127.6541 crore in the corresponding half year ended September 30, 2025. The group’s reported half-year operating income therefore increased by Rs 27.684 crore year on year, while the two subsidiaries recorded no income in the 2026 period.
The auditor’s subsidiary figures were reviewed by the respective independent auditors rather than directly reviewed by the consolidated auditor. The filing says the two subsidiaries’ unaudited interim results and financial information were considered in Andrew Yule’s consolidated statement, despite their combined assets being only Rs 5,790 at September 30, 2026.
Got a follow-up? Ask IRIS
What intercompany matters did Andrew Yule’s auditor identify?
Andrew Yule’s auditor said there was no agreement setting out repayment terms or interest payable on borrowings from Andrew Yule by Yule Engineering and Yule Electrical. The November 12, 2026 report does not quantify the total amount of those borrowings, but specifically identifies the absence of agreed repayment and interest terms as an Other Matter involving both subsidiaries.
A separate issue concerned a Rs 2.37 lakh advance associated with Yule Electrical and Yule Engineering at September 30, 2026. Yule Electrical had not received formal balance confirmation for the borrowing referred to in the report, while Yule Engineering did not disclose a corresponding Rs 2.37 lakh advance recoverable from Yule Electrical because management said Yule Engineering had written off the entire outstanding advance.
The review report does not state whether the missing balance confirmation or the written-off Rs 2.37 lakh advance will affect the closure proposals filed in January 2023. It does establish that the subsidiaries had no significant operating activity in the September 2026 quarter and half year while intercompany borrowing documentation and balance recognition remained matters noted by the auditors.
Did the auditor modify its conclusion on Andrew Yule’s results?
The auditor did not modify its conclusion on Andrew Yule’s unaudited consolidated financial results for the quarter and half year ended September 30, 2026. Based on its limited review procedures, the auditor said nothing had come to its attention that caused it to believe the statement was materially misstated, and it explicitly said its conclusion was not modified for the matters reported.
The report nevertheless noted that the limited review reports of Yule Engineering and Yule Electrical each contained an emphasis of matter on the going-concern and intercompany-borrowing issues. A limited review provides moderate assurance and is narrower than an audit, according to the report, which says its procedures included inquiries of Andrew Yule personnel and analytical review work.
The same November 12, 2026 report also highlighted wider reporting matters at Andrew Yule, including audit-trail features introduced only for financial transactions such as the cash book and significant manual intervention in consolidation. The auditor said the manual consolidation process created a higher level of audit risk because Andrew Yule did not have an integrated system.
Conclusion
Andrew Yule’s September 2026 disclosure places Yule Engineering and Yule Electrical in a formal no-going-concern position, supported by nil income, total assets of Rs 5,790 and a combined Rs 85,300 loss. Although their financial scale was limited against Andrew Yule’s Rs 155.3381 crore half-year operating income, both entities remained within the consolidated accounts and were subject to specific audit observations on operations and intercompany arrangements.
The next disclosure to watch is an update from Andrew Yule or the Ministry of Heavy Industries on the closure proposals submitted on January 4, 2023. Andrew Yule may also disclose whether repayment and interest terms are documented for subsidiary borrowings and whether the Rs 2.37 lakh intercompany balance matter has been formally resolved.