










Anondita targets FY27 ₹240-250 crore revenue from orders
Key highlights
- Anondita targets FY27 revenue of ₹240-250 crore after reporting ₹73.54 crore of consolidated H1 FY27 revenue.
- Management cited about ₹70 crore of domestic government orders and ₹40 crore of export orders for H2 FY27.
- Own-brand sales were ₹52.72 crore in H1 FY27, compared with approximately ₹12 crore from government sales and ₹8.77 crore from exports.
- Anondita expects four additional male-condom lines to lift annual capacity to 1.1 billion units within two weeks.
powered by IRIS
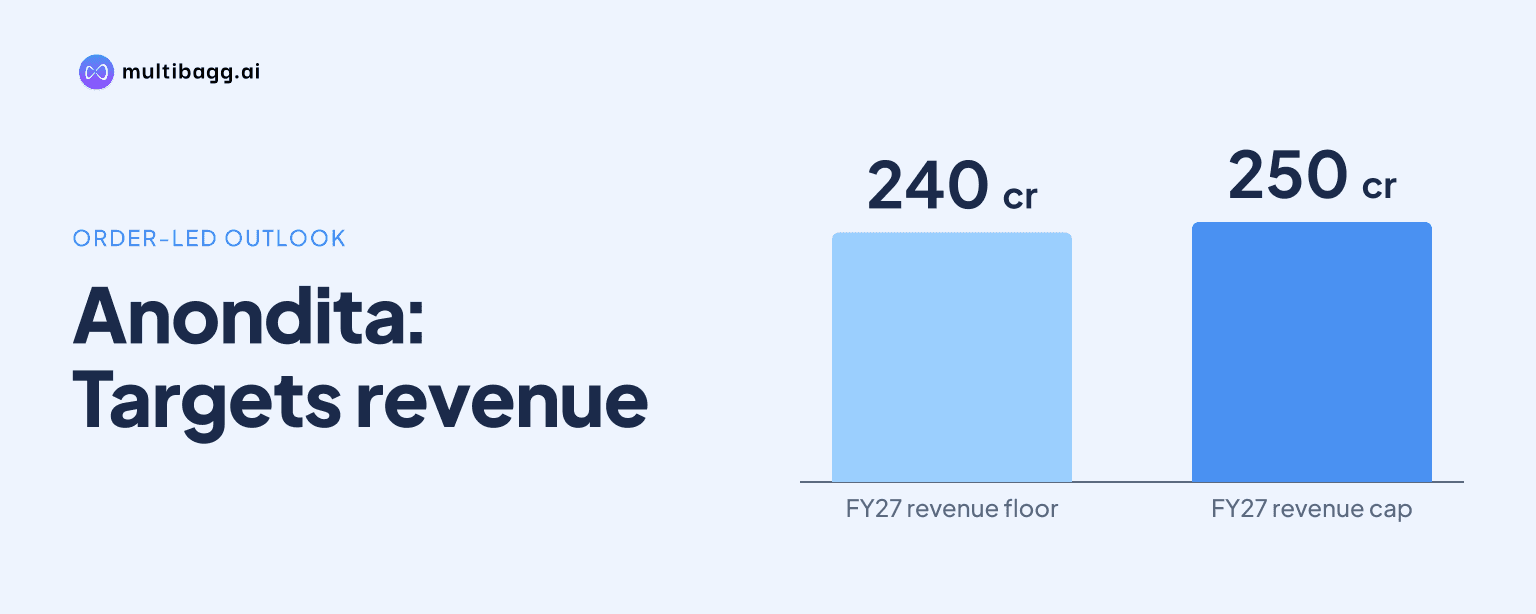
Anondita Medicare Limited targets FY27 revenue of ₹240-250 crore after reporting ₹73.54 crore of consolidated revenue in the first half, citing about ₹70 crore of domestic government orders and ₹40 crore of export orders for second-half execution. Management said supplies against both order streams had already started, while also referring to own-brand sales.
Know Anondita Medicare inside out
Results, valuation, peers and who's buying, in one view.
Why does Anondita target FY27 revenue of ₹240-250 crore?
Anondita targets FY27 revenue of ₹240-250 crore because management said it had received domestic purchase orders worth about ₹70 crore and held export orders worth about ₹40 crore for execution in the second half. In response to an analyst, management said the domestic supplies had started after purchase-order approvals that had been delayed by transfers and postings in the health ministry.
The government orders include supplies for National AIDS Control Societies, including Nirodh and Deluxe Nirodh products, according to management. It also cited products for which it had been declared L1, or lowest bidder. Anondita said it supplied approximately ₹12 crore to the government in H1 FY27, compared with the about ₹70 crore domestic orders identified for the following six months.
On exports, management said Anondita had completed initial shipments of 10 containers valued at ₹8.70 crore in one statement and ₹8.77 crore in a later answer. It said the customer had made advance payment and was releasing the remaining 40 containers. Management subsequently described export orders in hand at about ₹40 crore, which it said were executable in H2 FY27.
Management also told the analyst that ₹240-250 crore of orders were in hand, with four months left in the financial year, and said FY27 revenue could exceed the guided range. However, the call did not provide a detailed reconciliation between the ₹70 crore domestic orders, ₹40 crore export orders, own-brand orders and the full stated order amount. The ₹240-250 crore figure is therefore management guidance, not reported revenue.
What did Anondita report in H1 FY27?
Anondita reported consolidated revenue of ₹73.54 crore in H1 FY27, with own-brand sales of ₹52.72 crore, government revenue of approximately ₹12 crore and export revenue of ₹8.77 crore, according to management. The disclosed channel figures total ₹73.49 crore, or ₹5 lakh below reported consolidated revenue, and management did not explain that difference during the call.
Own-brand sales were Anondita's largest disclosed H1 FY27 channel at ₹52.72 crore, exceeding government sales of about ₹12 crore and exports of ₹8.77 crore. Management attributed H1 profitability partly to the own-brand mix, while saying export business carried higher pricing and incentives than domestic government supplies.
Management said export government supplies were priced about 20% above domestic government supplies. It also said government contracts generally run for one or two years and do not permit price changes during the tender period. The H1 mix therefore included a ₹52.72 crore own-brand contribution alongside smaller but higher-priced export sales.
What margins and working-capital changes did Anondita disclose?
Anondita said its profit after tax margin should remain between 26% and 29%, according to management, rather than decline to the 20%-25% range raised during the discussion. Management linked that expectation to export sales, stating that export pricing and incentives contribute more than domestic government business.
Management gave channel-level margins of about 60%-65% for own brands, 55%-60% for exports and 50%-52% for government sales in H1 FY27. The transcript did not identify whether those channel measures were gross, operating or another type of profit margin. Management also put its electronic test pass rate at approximately 98%-99%.
Working-capital use increased because Anondita had purchased materials and prepared goods before government orders expected in August were issued, finance management said. An analyst cited working-capital days of 200, compared with 170 days in FY26. Management said the delay in government purchase orders left the company holding more finished goods and inventory.
Latex is the principal raw material and requires advance payment, management said. Anondita also extended credit of 60 to 70 days to super distributors, distributors and retailers as it developed its own-brand business. Management said the company had previously relied more on advance payment or payment-on-delivery terms, making receivables another stated factor in working-capital use.
Got a follow-up? Ask IRIS
What capacity additions support Anondita's supply plans?
Anondita said it had capacity of 869 million pieces across 15 manufacturing lines after adding 307 million pieces during the year. Four additional male-condom lines had completed trial production and were expected to enter commercial production within two weeks, which management said would take annual male-contraceptive capacity to 1.1 billion units.
The company acquired adjacent D2 and D3 buildings after operating from D1, which management described as a one-acre site. Management said the extra space would support manufacturing expansion. It also said it completed a ₹91 crore rights issue at ₹950 per share to fund female latex and non-latex condom capacity, infrastructure, working capital and domestic and international expansion.
For female products, management said two female-latex lines had completed trials and were expected to be ready by the end of December. Two female non-latex lines were expected to begin trials by December and enter commercial production within the financial year. Management stated planned female-latex capacity of 60 million units, while its explanation of non-latex capacity was not sufficiently detailed to assign a specific figure to each line.
Management said the already disclosed ₹70 crore domestic and ₹40 crore export orders had begun moving into supply, so it presented them as executable with existing operations. The female-condom programme instead forms part of the next growth phase: management said it expected female tenders and supplies to be ready in FY28.
Would WHO qualification affect Anondita's revenue plan?
Anondita said a delay in World Health Organization, or WHO, pre-qualification would not affect its existing revenue benchmarks, including its FY29 ₹1,000 crore target. Management said its disclosed targets did not include orders from WHO or the United Nations, meaning any orders associated with qualification would be additional to its stated plan.
Management said it expected WHO certification within eight months after receiving a review schedule. That is a management expectation rather than a completed approval. It also said the company had passed South African Bureau of Standards requirements, but did not provide the date or scope of that certification on the call.
Separately, management said Anondita was one of two companies shortlisted by the South African government to develop and supply a youth-focused condom product. It also said a surgical-glove product submitted in an African tender had been accepted and shortlisted for future procurement. Management did not quantify either opportunity as revenue or include either in the FY27 target.
Conclusion
Anondita's FY27 revenue guidance of ₹240-250 crore is based on management's stated order visibility rather than solely on an aspirational growth forecast. The principal disclosed support is about ₹70 crore of domestic government orders and ₹40 crore of export orders for H2 FY27, after ₹73.54 crore of consolidated revenue in H1 FY27. Own-brand sales of ₹52.72 crore were the largest disclosed first-half sales channel.
The next issues to watch are delivery and cash collection from the H2 domestic and export orders, particularly after management cited 60-to-70-day distributor credit and an analyst cited 200 working-capital days. Management plans to commercialise four male lines within two weeks, have female-latex lines ready by December, bring female non-latex lines into commercial production within the financial year, and complete the WHO review process within eight months.