










Anupam Rasayan Q2FY27 EBITDA rises 41% as margin reaches 25%
Key highlights
- Anupam Rasayan’s Q2FY27 consolidated EBITDA rose 41% year on year to Rs 202 crore.
- Anupam Rasayan’s Q2FY27 EBITDA margin increased to 25% from 19% in Q2FY26.
- Anupam Rasayan’s Q2FY27 profit after tax rose 14% to Rs 65 crore as finance cost reached Rs 56 crore.
- Anupam Rasayan acquired a 50.07% controlling stake in Bliss GVS Pharma on September 28, 2026.
powered by IRIS
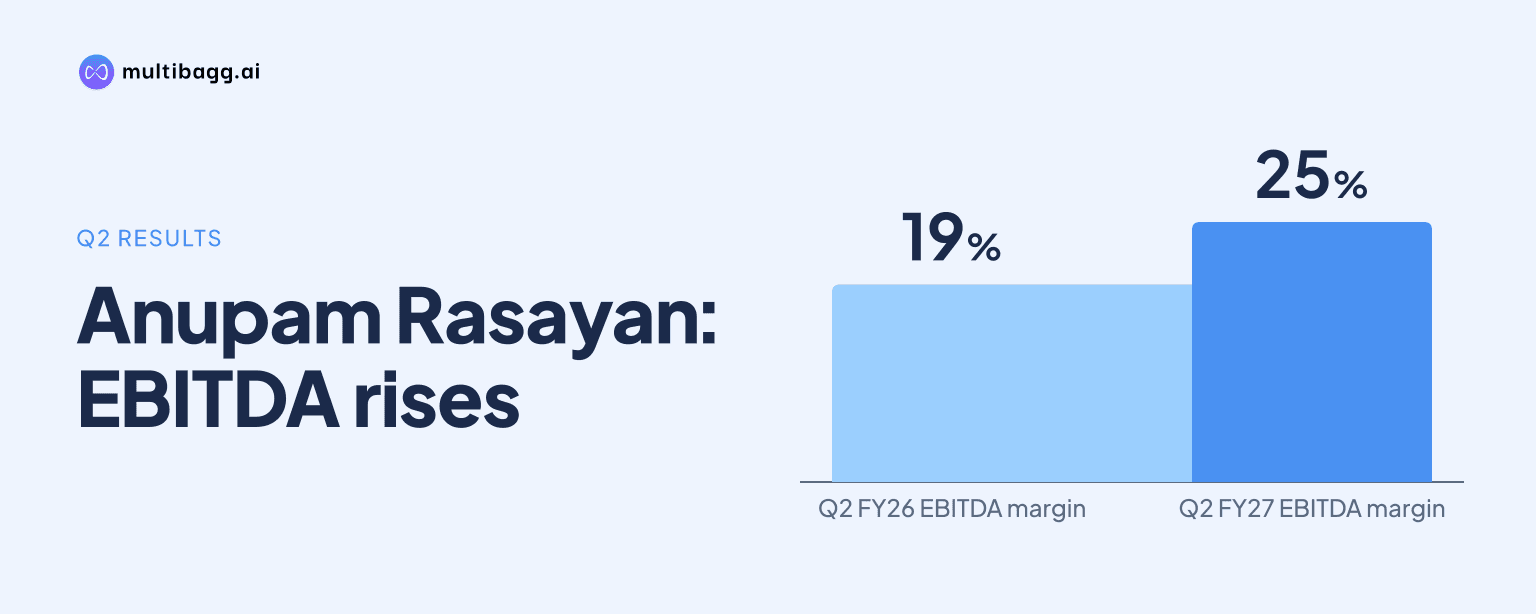
Anupam Rasayan India Limited reported consolidated Q2FY27 EBITDA of Rs 202 crore, up 41% year on year, as EBITDA margin increased to 25% from 19%. Profit after tax rose 14% to Rs 65 crore, as depreciation increased to Rs 57 crore and finance cost rose to Rs 56 crore.
Know Anupam Rasayan India inside out
Results, valuation, peers and who's buying, in one view.
How did Anupam Rasayan perform in Q2FY27?
Anupam Rasayan reported consolidated total income of Rs 821 crore in Q2FY27, up 11% from Rs 739 crore in Q2FY26. Revenue from operations increased to Rs 806 crore from Rs 731 crore, while other income rose to Rs 15 crore from Rs 8 crore.
The prior-year revenue-from-operations figure included Rs 180 crore of one-off sales, according to the profit-and-loss statement. Against that base, EBITDA increased by Rs 58 crore to Rs 202 crore from Rs 144 crore, while profit after tax increased by Rs 8 crore to Rs 65 crore from Rs 57 crore.
Anupam Rasayan’s quarterly highlights also reported sequential growth of 23% in consolidated total revenue, 16% in EBITDA and 27% in profit after tax. Earnings per share increased to Rs 6.81 in Q2FY27 from Rs 3.93 in Q2FY26, while the profit-after-tax margin remained 8% in both periods.
Why did Anupam Rasayan’s EBITDA margin increase?
Anupam Rasayan said Q2FY27 EBITDA margin increased to 25% from 19% because Performance Materials and Pharmaceutical products made a higher contribution to the sales mix. The presentation does not disclose separate revenue, EBITDA or margin figures for either product category.
The cost structure changed alongside the margin expansion. Cost of materials consumed declined to Rs 398 crore in Q2FY27 from Rs 474 crore in Q2FY26, despite revenue from operations increasing by Rs 75 crore. Employee expenses rose to Rs 68 crore from Rs 17 crore, and other expenses increased to Rs 144 crore from Rs 104 crore.
The first-half comparison also showed higher operating profitability. H1FY27 EBITDA rose 38% to Rs 377 crore from Rs 273 crore in H1FY26, while the EBITDA margin rose to 25% from 22%. Total income grew 21% to Rs 1,489 crore from Rs 1,230 crore, making the H1 margin expansion smaller than the six-percentage-point Q2 increase.
Why did Anupam Rasayan’s PAT grow slower than EBITDA?
Anupam Rasayan’s Q2FY27 profit after tax grew 14%, below the 41% EBITDA increase, as depreciation rose by Rs 25 crore and finance cost increased by Rs 20 crore. Depreciation was Rs 57 crore against Rs 32 crore a year earlier, while finance cost was Rs 56 crore against Rs 36 crore.
EBIT therefore increased by Rs 34 crore to Rs 146 crore, compared with the Rs 58 crore EBITDA increase. Profit before tax rose to Rs 89 crore from Rs 76 crore, and tax increased to Rs 24 crore from Rs 18 crore, leaving the net margin unchanged at 8%.
The H1FY27 figures show a similar difference between operating and net-profit growth. Depreciation rose to Rs 113 crore from Rs 63 crore and finance cost increased to Rs 105 crore from Rs 72 crore. EBITDA grew 38% to Rs 377 crore, but profit after tax rose 10% to Rs 116 crore and the profit-after-tax margin declined to 8% from 9%.
Got a follow-up? Ask IRIS
What changed in Anupam Rasayan’s balance sheet and cash flow?
Anupam Rasayan’s consolidated balance-sheet total increased to Rs 11,395 crore at September 2026 from Rs 8,013 crore at March 2026. The presentation states that Bliss GVS Pharma Limited’s financials were included in full in the consolidated balance sheet following Anupam Rasayan’s acquisition of a 50.07% stake on September 28, 2026.
Non-current assets increased to Rs 6,214 crore from Rs 4,285 crore, and current assets rose to Rs 5,181 crore from Rs 3,728 crore. Inventories increased to Rs 2,089 crore from Rs 1,775 crore, trade receivables rose to Rs 1,582 crore from Rs 959 crore, and cash and cash equivalents including fixed-deposit investments stood at Rs 764 crore against Rs 394 crore.
Borrowings were higher at September 2026. Long-term borrowings rose to Rs 853 crore from Rs 511 crore, while short-term borrowings increased to Rs 1,605 crore from Rs 1,304 crore. Net cash from financing activities was Rs 2,228 crore at September 2026, compared with Rs 621 crore at March 2026.
Cash generated from operations was Rs 328 crore at September 2026, compared with Rs 379 crore at March 2026, while net cash from operating activities was Rs 303 crore against Rs 334 crore. Net cash used in investing activities was Rs 2,318 crore, compared with Rs 820 crore in the March-period comparison.
What are Anupam Rasayan’s disclosed next priorities?
Anupam Rasayan has entered finished dosage formulations through its 50.07% controlling stake in Bliss GVS Pharma. Bliss GVS contributed to consolidated revenue only from September 28, 2026, although its financials were included fully in the consolidated balance sheet and cash-flow statement.
Management said the acquisition complements Anupam Rasayan’s pharmaceutical-intermediates and custom-synthesis capabilities. Its stated priorities include integrating strategic investments, using capital employed optimally, and enhancing manufacturing and technological capabilities.
Anupam Rasayan also signed a six-year supply agreement with a US-based global specialty metal manufacturer, marking its entry into the geological resources sector. The presentation does not provide the contract value, product volumes, start date or expected revenue contribution.
The group structure presentation lists pro forma FY26 revenue of more than Rs 4,000 crore, specialty-chemicals capacity of more than 200,000 metric tonnes, and pharmaceutical-formulation capacity of more than 4,800 million units. It also lists 14 manufacturing plants, more than 200 clients and more than 175 research-and-development professionals on a consolidated basis.
Conclusion
Anupam Rasayan’s Q2FY27 results show that EBITDA grew faster than income and net profit, with margin expansion to 25% associated with a greater contribution from Performance Materials and Pharmaceutical products. Higher depreciation and finance costs narrowed the translation of the Rs 58 crore EBITDA increase into an Rs 8 crore rise in profit after tax.
The next disclosed matters to watch are the integration of Bliss GVS Pharma after the September 28, 2026 transaction and the execution of the six-year specialty-metal supply agreement. Management has identified integration and capital-employed utilisation as priorities, while the presentation leaves the acquisition’s earnings contribution and the supply contract’s financial value unresolved.