










Apsis Aerocom uses Rs 25.57 crore with no IPO deviation
Key highlights
- Apsis Aerocom used Rs 25.57 crore of Rs 35.77 crore gross IPO proceeds by September 30, 2026.
- Machinery purchases received Rs 19.52 crore of IPO funds against an original allocation of Rs 27.02 crore.
- Rs 10.20 crore remained unutilised at September 30, 2026, including Rs 7.50 crore for machinery.
- Apsis Aerocom reported Rs 0.00 deviation or variation across all three IPO objects.
powered by IRIS
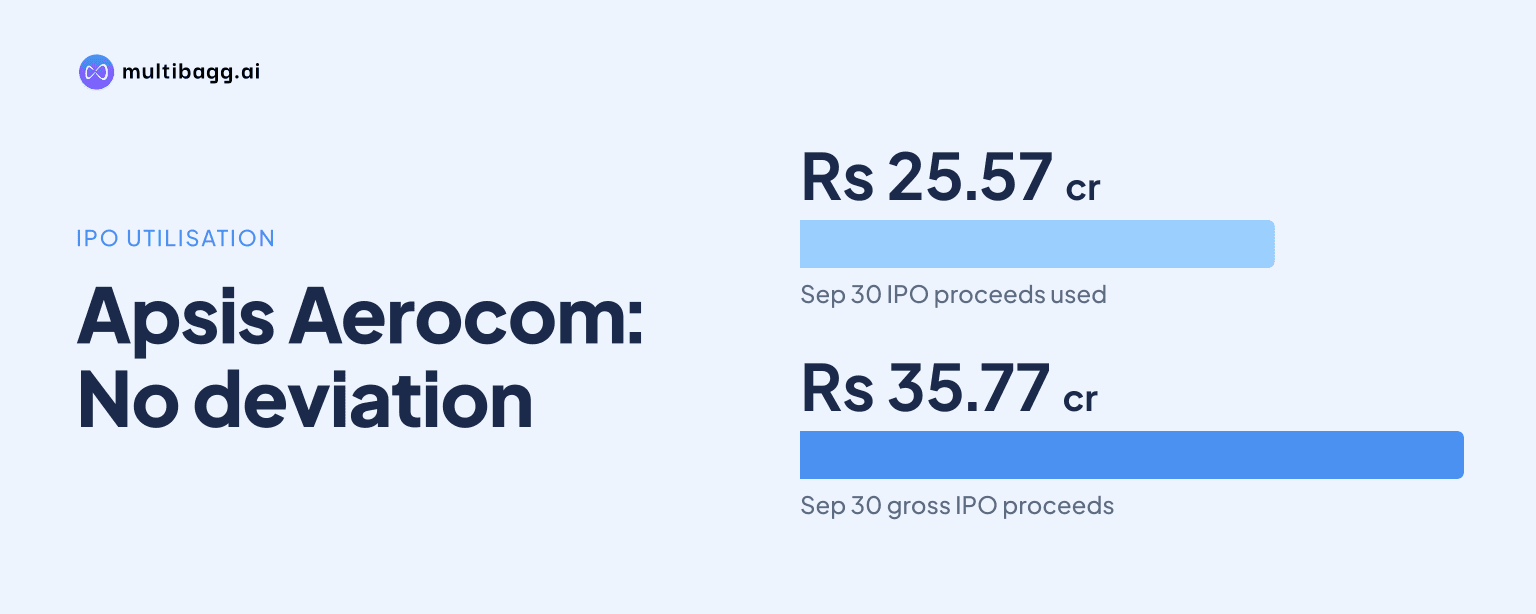
Apsis Aerocom Limited used Rs 25.57 crore of Rs 35.77 crore in gross initial public offer, or IPO, proceeds by September 30, 2026, including Rs 19.52 crore for machinery, and disclosed no deviation from its stated objects. Statutory auditors YCRJ & Associates certified the recorded utilisation after examining books and relevant records.
Know Apsis Aerocom inside out
Results, valuation, peers and who's buying, in one view.
How much of Apsis Aerocom’s IPO proceeds had been used?
Apsis Aerocom had used Rs 25.57 crore of its Rs 35.77 crore gross IPO proceeds as of September 30, 2026, leaving Rs 10.20 crore unutilised. The company’s object-wise schedule and the auditor’s certificate both report the utilisation amount as including goods and services tax.
The IPO opened on March 11, 2026 and closed on March 13, 2026. Apsis Aerocom reported Rs 30.94 crore in net proceeds after issue-related expenses, while the utilisation schedule tracks the gross proceeds because Rs 4.84 crore of the fundraise was allocated to IPO expenses.
Machinery accounted for Rs 19.52 crore of the Rs 25.57 crore used, making it the largest stated application of funds at September 30, 2026. Of the remaining Rs 10.20 crore, Rs 7.50 crore was still allocated to machinery, compared with Rs 2.44 crore for general corporate purpose and Rs 25.84 lakh for IPO expenses.
Where did Apsis Aerocom spend the IPO money?
Apsis Aerocom spent Rs 19.52 crore of IPO proceeds on capital expenditure towards machinery purchases by September 30, 2026. The original machinery allocation was Rs 27.02 crore, higher than the Rs 3.91 crore allocated to general corporate purpose and Rs 4.84 crore for IPO expenses.
The company used Rs 1.48 crore for general corporate purpose and Rs 4.58 crore for IPO expenses. The latter left Rs 25.84 lakh unutilised, whereas machinery purchases retained Rs 7.50 crore of their original allocation at the reporting date.
The half-year cash-flow statement reported Rs 13.30 crore of purchases of property, plant and equipment and Rs 10.02 crore of advances for capital expenditure in the six months ended September 30, 2026. Total cash used in investing activities was Rs 23.33 crore, compared with Rs 2.91 crore in the half year ended September 30, 2025; the filing does not separately match individual cash-flow payments with IPO-funded machinery purchases.
Property, plant and equipment rose to Rs 24.61 crore at September 30, 2026 from Rs 12.30 crore at March 31, 2026. That balance-sheet increase occurred alongside the Rs 23.33 crore investing outflow, but the filing does not provide an asset-by-asset reconciliation of the Rs 19.52 crore of IPO-funded machinery spending.
Did Apsis Aerocom report any change in IPO use?
Apsis Aerocom reported no deviation or variation in the use of IPO funds for the half year ended September 30, 2026. Its Regulation 32 statement showed no modified allocation for machinery, general corporate purpose or IPO expenses, and recorded Rs 0.00 deviation or variation for each object.
The Audit Committee reviewed the use of funds and stated that there was no deviation or variation from the IPO. The filing also recorded nil auditor comments and said that no monitoring agency was applicable to the issue.
Apsis Aerocom’s financial-results notes similarly state that there had been no deviation or variation from the objects in the prospectus dated March 16, 2026. The company defines deviation or variation as a change in the fund-raising purpose, a difference in use against the originally disclosed amount, or a change in terms of a contract referred to in the offer document.
YCRJ & Associates issued its certificate on November 7, 2026 for submission to the National Stock Exchange of India Limited under Regulation 32 of the Securities and Exchange Board of India Listing Obligations and Disclosure Requirements Regulations, 2015. The auditors certified that Rs 25.57 crore had been used for purposes stated in the offer document after reviewing Apsis Aerocom’s books and relevant records.
Got a follow-up? Ask IRIS
How did capital spending coincide with Apsis Aerocom’s half-year finances?
Apsis Aerocom reported Rs 21.17 crore in revenue from operations for the half year ended September 30, 2026, up from Rs 13.65 crore in the corresponding half year ended September 30, 2025. Profit after tax increased to Rs 3.97 crore from Rs 3.27 crore over the same year-on-year comparison.
Compared with the half year ended March 31, 2026, revenue increased from Rs 16.99 crore to Rs 21.17 crore, while profit after tax decreased from Rs 4.24 crore to Rs 3.97 crore. Depreciation and amortisation was Rs 99.66 lakh in the September 2026 half year, compared with Rs 46.97 lakh a year earlier.
Operating activities generated Rs 2.78 crore in cash during the half year ended September 30, 2026, while financing activities used Rs 94.26 lakh and investing activities used Rs 23.33 crore. The cash-flow statement reported closing cash and cash equivalents of Rs 12.95 crore, against an opening balance of Rs 34.44 crore.
The balance sheet separately reported cash and cash equivalents of Rs 15.07 crore at September 30, 2026, compared with Rs 36.51 crore at March 31, 2026. The supplied notes do not explain the difference between the Rs 15.07 crore balance-sheet figure and the Rs 12.95 crore closing figure in the cash-flow statement.
What IPO proceeds remain for Apsis Aerocom to use?
Apsis Aerocom had Rs 10.20 crore of gross IPO proceeds left to use after September 30, 2026. The largest outstanding allocation was Rs 7.50 crore for machinery, followed by Rs 2.44 crore for general corporate purpose and Rs 25.84 lakh for IPO expenses.
The November 7, 2026 disclosure retained the original allocations of Rs 27.02 crore for machinery, Rs 3.91 crore for general corporate purpose and Rs 4.84 crore for IPO expenses. It showed no revised object and no modified allocation for any of the three categories.
Apsis Aerocom operates in a single segment, so the filing does not provide segment-level revenue, profit or capital-spending data for the machinery programme. It also gives no completion date for the remaining machinery purchases or for deployment of the Rs 10.20 crore still unutilised at September 30, 2026.
Conclusion
The utilisation disclosure shows that machinery purchases were the central use of Apsis Aerocom’s March 2026 IPO proceeds through September 30, while general corporate purpose and IPO expenses made up the remainder. The company, its Audit Committee and its statutory auditors all reported that the spending remained within the disclosed IPO objects.
The next point to watch is deployment of the Rs 10.20 crore balance, particularly the Rs 7.50 crore still designated for machinery. The November 7, 2026 filing kept the original allocation intact but did not disclose a timetable for the outstanding spending.