










Arvind SmartSpaces estimates ₹5,197 crore operating cash flow
Key highlights
- ASL states net estimated unrealised operating cash flow of ₹5,197 crore from projects with definitive agreements signed.
- Gujarat contributes ₹2,325 crore and Karnataka contributes ₹2,128 crore of estimated operating cash flow.
- Projects yet to be launched contribute ₹2,652 crore of estimated operating cash flow in ASL’s state-level rows.
- ASL lists ₹9,018 crore of total estimated booking value in planned projects versus ₹8,763 crore in ongoing projects.
powered by IRIS
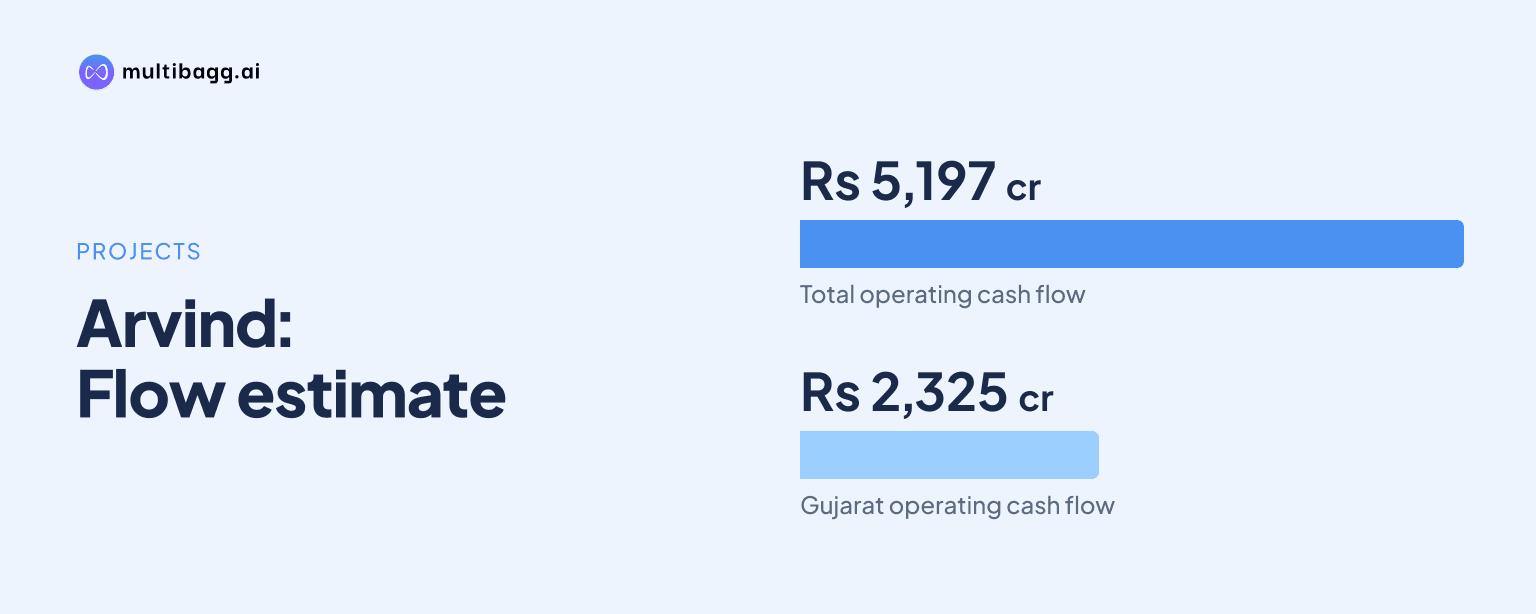
Arvind SmartSpaces estimates ₹5,197 crore of net unrealised operating cash flow from projects with definitive agreements signed as of its Q2 FY27 update, after a ₹200 crore negative surplus/(deficit) line. Gujarat contributes ₹2,325 crore and Karnataka ₹2,128 crore of estimated operating cash flow, while Maharashtra contributes ₹944 crore.
Know Arvind SmartSpaces inside out
Results, valuation, peers and who's buying, in one view.
How does ASL calculate ₹5,197 crore of operating cash flow?
ASL calculates its stated ₹5,197 crore net estimate from ₹5,396 crore of estimated operating cash flow and a ₹200 crore negative surplus/(deficit) adjustment. The company defines the measure as estimated cash flow at the earnings before interest, taxes, depreciation and amortisation, or EBITDA, level after allocating corporate overheads.
The calculation starts with total estimated booking value of ₹21,092 crore across completed, ongoing and yet-to-be-launched projects. ASL reported ₹8,766 crore of booking value till date, leaving ₹12,326 crore of estimated inventory; adding ₹2,612 crore of receivables produces the disclosed ₹14,938 crore inventory-plus-receivables figure.
ASL then deducts ₹9,541 crore of balance cost to be incurred from the ₹14,938 crore inventory-plus-receivables amount, producing the reported ₹5,396 crore estimated operating cash flow before the adjustment. The disclosure includes land cost payable to land partners and covers only projects for which definitive agreements have been signed.
The estimate is not presented as reported revenue, cash on the balance sheet or a schedule of collections. For development-management, or DM, projects, ASL says revenue and cost are grossed up in the disclosure, but its net operating cash flow is limited to DM fees; the estimate otherwise represents the company’s share only.
Which states provide ASL’s estimated operating cash flow?
ASL identifies Gujarat as the largest contributor, with ₹2,325 crore of estimated operating cash flow, followed by Karnataka at ₹2,128 crore and Maharashtra at ₹944 crore. Gujarat’s amount is based on ₹6,175 crore of estimated inventory plus receivables and ₹3,850 crore of balance cost to be incurred.
Gujarat’s ongoing projects account for ₹1,414 crore of its ₹2,325 crore estimate, compared with ₹811 crore from projects yet to be launched and ₹100 crore from completed projects. Its portfolio includes Smartpark, a commercial joint-development project with an estimated 2030 completion date and ₹634 crore of total estimated booking value.
Karnataka’s ₹2,128 crore estimate comprises ₹1,087 crore from ongoing projects, ₹902 crore from projects yet to be launched and ₹139 crore from completed projects. The state has ₹4,494 crore of estimated inventory plus receivables against ₹2,366 crore of balance cost, and includes ongoing Sylva and Skycrest, both scheduled for estimated completion in 2029.
Maharashtra contributes ₹944 crore, including ₹939 crore from projects yet to be launched and ₹5 crore from completed projects. Its planned portfolio includes Khopoli with ₹1,520 crore of estimated booking value, Sigma, Goregaon with ₹2,433 crore, and Harikripa with ₹312 crore.
Got a follow-up? Ask IRIS
How much of ASL’s estimate depends on projects not completed?
ASL’s state rows show ₹2,652 crore of estimated operating cash flow from projects yet to be launched and ₹2,501 crore from ongoing projects, compared with ₹244 crore from completed projects. The two not-completed categories therefore account for ₹5,153 crore based on the state-level rows, making execution and future launches central to the estimate.
The planned-project contribution is led by Maharashtra at ₹939 crore, narrowly ahead of Karnataka at ₹902 crore and Gujarat at ₹811 crore. All these projects are labelled “Yet to be launched” in ASL’s portfolio summary, rather than being given estimated completion years.
Ongoing projects are concentrated in Gujarat and Karnataka, as the cash-flow table does not list an ongoing Maharashtra category. Gujarat’s Aquacity has an estimated 2028 completion date, while Karnataka’s Forest Trails and Orchards Phase II are scheduled for 2027, illustrating that the ongoing portfolio has completion dates ranging from 2026 to 2030.
The disclosed rows do not fully reconcile to the stated grand-total operating cash flow: the three state estimates add to ₹5,397 crore, while the grand-total row reports ₹5,396 crore before the ₹200 crore adjustment. Readers can therefore identify the regional mix from the rows, but the company’s stated net estimate remains ₹5,197 crore.
What portfolio structures affect ASL’s cash-flow estimate?
ASL’s ₹21,092 crore total estimated booking value consists of ₹3,311 crore for completed projects, ₹8,763 crore for ongoing projects and ₹9,018 crore for planned projects. Planned projects therefore have the largest booking-value component, exceeding the ongoing portfolio by ₹255 crore.
The portfolio uses owned projects, joint ventures, joint developments and DM arrangements with different economic interests. For example, ASL lists Uplands 2.0 and 3.0 as a joint venture with about 55% revenue share, Smartpark as a joint development with about 70.5% revenue share, and Forreste 5 as a DM project with about 10% revenue share.
HDFC Platform 2 also appears in the project list. Sylva is an ongoing Karnataka project in which ASL lists 33.33% investment interest, while the planned Nallurhalli, Whitefield project carries the same 33.33% interest; both project-level interests are relevant because the cash-flow estimate represents ASL’s share only.
ASL separately disclosed that its board approved an additional ₹375 crore H-Dream residential development platform in May 2026. The proposed investment was ₹125 crore from ASL and ₹250 crore from H-Dream, but this platform approval is distinct from the signed-project cash-flow table.
Conclusion
ASL’s stated ₹5,197 crore net unrealised operating cash-flow estimate links future inventory sales and receivables to ₹9,541 crore of remaining project cost, rather than measuring current reported profit or cash. Gujarat and Karnataka supply the largest regional amounts, while the ₹2,652 crore contribution from yet-to-be-launched projects shows the material role of planned execution.
The next points to watch are launches within the ₹9,018 crore planned portfolio and delivery against estimated completion dates spanning 2026 to 2030 for ongoing projects. Changes in receivables, balance cost and the company’s disclosed ₹200 crore surplus/(deficit) adjustment would also affect how the project-level estimate develops.