










Astonea Labs Limited targets ₹40 crore FY28 pipeline revenue
Key highlights
- Astonea’s FY28 pipeline totals ₹40 crore, comprising ₹25 crore from approximately 60 registrations and ₹15 crore of US OTC export potential.
- Approximately 60 registrations are expected in Q1 FY28 and are projected to contribute ₹25 crore of revenue.
- Astonea targets more than ₹300 crore of FY28 revenue, following a more than ₹215 crore FY27 target.
- H1 FY27 revenue from operations was ₹95.86 crore, up 44.6% year on year.
powered by IRIS
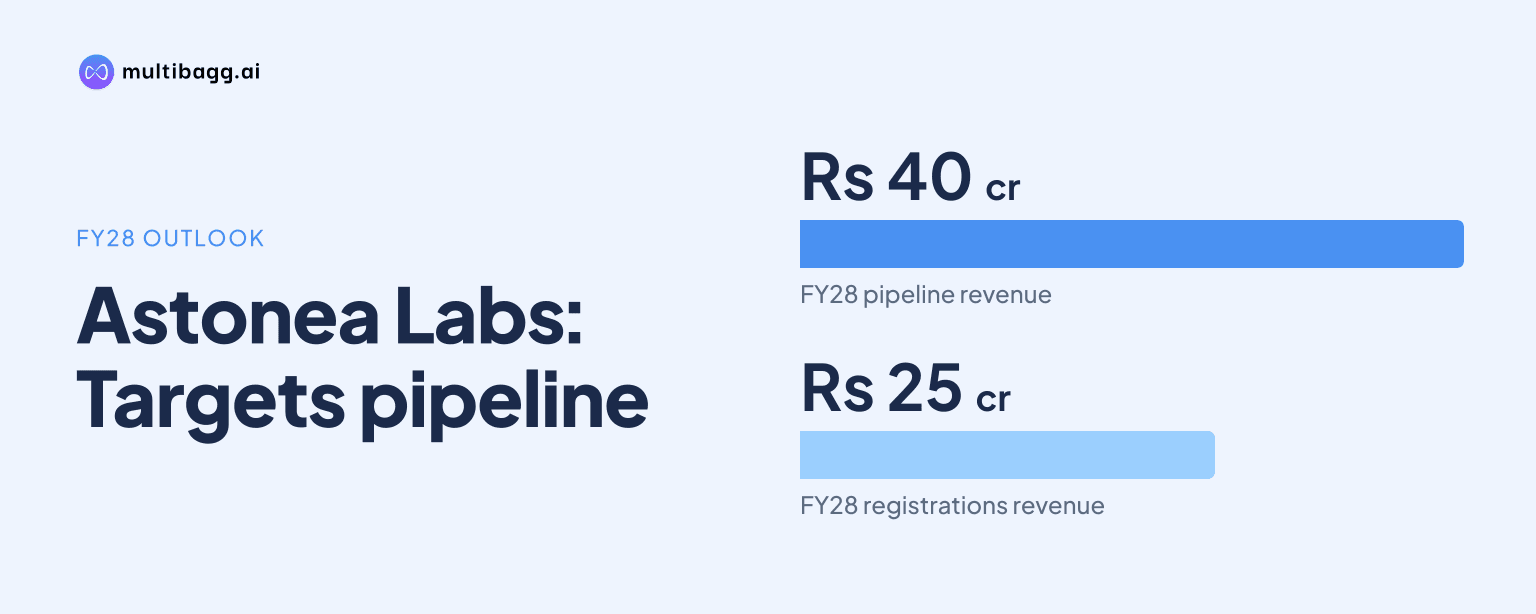
Astonea targets a ₹40 crore FY28 revenue pipeline, combining ₹25 crore projected from about 60 registrations expected in Q1 FY28 and ₹15 crore of potential US over-the-counter, or OTC, exports. Management presents these two components as a forward-looking opportunity alongside revenue and margin guidance through FY29.
Know Astonea Labs inside out
Results, valuation, peers and who's buying, in one view.
What makes up Astonea’s ₹40 crore FY28 pipeline?
Astonea’s stated ₹40 crore FY28 pipeline consists of approximately ₹25 crore from roughly 60 product registrations and ₹15 crore from a US OTC export opportunity. The presentation says the registrations are expected in Q1 FY28, while describing the US export figure as additional revenue potential. These are pipeline estimates rather than reported sales, and the ₹40 crore combined target is the sum shown in management’s FY2027-28 revenue-pipeline table.
The two streams differ in their stated mechanism and timing. Registrations are tied to a defined expected milestone of approximately 60 registrations in Q1 FY28, whereas the US OTC component is identified as an export opportunity without a specified registration count or timing beyond its inclusion in the FY28 pipeline. The presentation also reports approximately 5% month-on-month, or MoM, momentum across Astonea’s core OTC portfolio, providing the operating context for the OTC export plan.
How does Astonea’s FY28 pipeline fit its revenue targets?
Astonea positions the ₹40 crore pipeline within a wider management target of more than ₹300 crore of FY28 revenue from operations. The FY28 target follows a more than ₹215 crore FY27 target and precedes a more than ₹405 crore FY29 target. Management says the FY28 target represents 40% growth on the FY27 target, while the FY29 target represents 35% growth on the FY28 target.
The presentation sets the FY27 target at more than ₹215 crore, described as 46% above FY26, and reports ₹95.86 crore delivered in H1 FY27, up 44.6% year on year. It also states that H2 represented 55% of FY26 revenue. The historical chart labels a 36% compound annual growth rate, or CAGR, from FY24 to FY26 and an approximately 40% CAGR from FY26 to FY29, with the latter calculation based on the lower end of management’s targets.
The target series should be read with its stated accounting qualification. FY24 and FY25 figures were prepared under previous generally accepted accounting principles, or GAAP, while FY26 onward uses Indian Accounting Standards, or Ind AS, on a standalone basis. The presentation explicitly labels the FY27 to FY29 revenue figures as management estimates and forward-looking statements, so the ₹25 crore registrations and ₹15 crore US OTC opportunity are not equivalent to booked revenue.
Got a follow-up? Ask IRIS
What are Astonea’s FY27 margin and growth benchmarks?
Astonea guides for a FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, margin of 13% to 15% and a profit after tax, or PAT, margin of 5% to 6%. These are margins on revenue from operations. The EBITDA measure includes other income, as presented, which is an important qualification when comparing it with measures that may exclude such income.
The FY27 EBITDA-margin range is above the 9.5% reported for FY26, while H1 FY27 EBITDA margin was 13.8%. For PAT, the FY27 guidance range of 5% to 6% compares with 3.0% in FY26, and H1 FY27 PAT margin was 5.0%. The H1 FY27 figures therefore sit within the stated annual guidance ranges, but the presentation does not provide a separate full-year operating forecast for the registration pipeline or US OTC exports.
Management’s revenue pathway links those margins to a target sequence of more than ₹215 crore in FY27, more than ₹300 crore in FY28 and more than ₹405 crore in FY29. However, the source does not allocate EBITDA or PAT contributions between the approximately 60 registrations, US OTC exports and existing businesses. It therefore supports the existence of the targets and margins, but not a segment-level profitability conclusion for either FY28 pipeline component.
How is Astonea building the export channels behind its outlook?
Astonea is expanding a distributor-led network across nine markets in Central America, South America and the Caribbean to support international distribution. The footprint comprises five Central American markets, three South American markets and one Caribbean market. The company identifies branded pharmaceutical, nutraceutical and wellness offerings as the product categories being expanded through this international presence.
Central America accounts for Guatemala, Nicaragua, Costa Rica, Panama and Honduras, while South America includes Ecuador, Bolivia and Peru; the Caribbean presence is in the Dominican Republic. Astonea says it appointed new distributors in Guatemala and Panama, adding two named distribution developments within its nine-market network. The presentation does not provide revenue by country, distributor or product category, so it does not quantify the current sales contribution from these markets.
The export strategy describes four mechanisms: distribution partnerships, wider market access, deeper regional presence and revenue diversification. These initiatives are framed around emerging international markets rather than the US OTC opportunity specifically. As a result, the disclosed nine-market Latin American and Caribbean footprint establishes the broader distribution strategy, while the ₹15 crore US OTC item remains a separately stated potential export opportunity.
Conclusion
Astonea’s FY28 pipeline is a management estimate of ₹40 crore, split between ₹25 crore associated with about 60 registrations expected in Q1 FY28 and ₹15 crore of potential US OTC exports. It sits alongside a broader more than ₹300 crore FY28 revenue target, following ₹95.86 crore of H1 FY27 revenue from operations and management’s stated 13% to 15% FY27 EBITDA-margin range.
The next disclosed milestone is the expected Q1 FY28 registration activity, which management associates with the approximately ₹25 crore component. Investors can also watch progress against the more than ₹215 crore FY27 revenue target, the FY27 PAT-margin guidance of 5% to 6%, and any later disclosure that clarifies the timing, orders or revenue recognition for the ₹15 crore US OTC export opportunity.