










Axis Bank Q2FY27 Preview: Profit Seen Up 43% in FY27
Key highlights
- Axis Bank’s gross advances rose 22.7% year-on-year to ₹1,384,600 crore as of September 30, 2026.
- Total deposits increased 20.7% year-on-year to ₹1,452,100 crore, while CASA deposits grew 10.6% and term deposits rose 27.3%.
- Excluding certain FCNR(B)-linked loans, adjusted advances growth was 18.8% year-on-year and adjusted deposit growth was 17.0%.
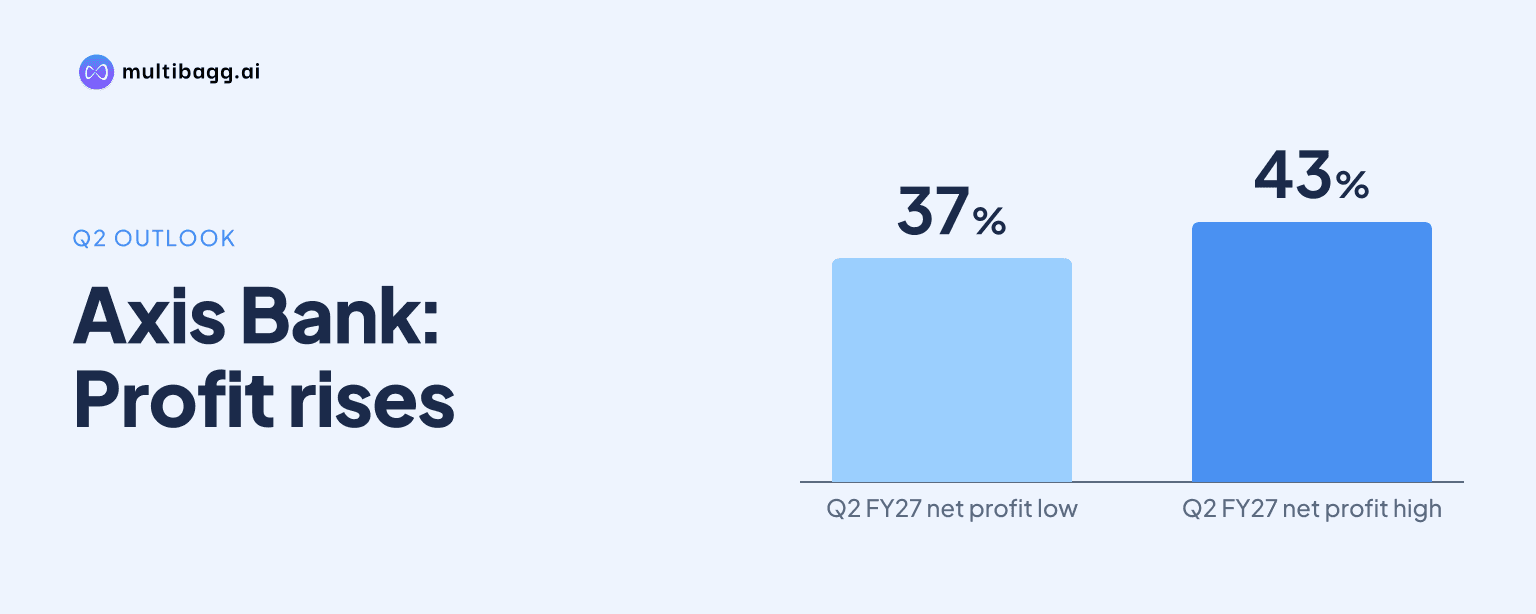
- Brokerages expect Q2FY27 net profit to rise 37%–43% year-on-year, while net interest margin could decline 7–12 basis points sequentially.
powered by IRIS
Provisional business update sets the tone
Axis Bank has released provisional business figures for the quarter ended September 30, 2026, pointing to strong year-on-year expansion in both advances and deposits. The bank reported gross advances of ₹1,384,600 crore, up 22.7% year-on-year and 8.8% sequentially. Total deposits stood at ₹1,452,100 crore, rising 20.7% year-on-year and 5.8% quarter-on-quarter. The update comes ahead of the lender’s scheduled September quarter earnings announcement on Saturday, October 17. While the headline growth numbers appear strong, brokerages are closely tracking the impact of FCNR(B) deposit mobilisation on margins. Axis Bank has also flagged that the disclosed figures are provisional and subject to a limited review by statutory auditors.
Know Axis Bank inside out
Results, valuation, peers and who's buying, in one view.
Loans grow 22.7% YoY, driven by higher book size
Axis Bank’s gross advances increased to ₹1,384,600 crore as of September 30, 2026, compared with ₹1,128,400 crore a year earlier. On a quarter-on-quarter basis, advances rose from ₹1,272,900 crore. The bank’s provisional disclosure supports the broad expectation of strong credit growth in the 20-22% range for the quarter, as cited by brokerages in their previews. Some analysts have also described growth as being supported by corporate and SME segments, along with a pickup in retail disbursements. However, the update also highlights that headline loan growth needs to be read alongside the FCNR(B)-linked impact. For investors, the key will be to separate underlying credit growth from transient effects tied to international branch lending related to deposit mobilisation.
Deposits rise 20.7% YoY, with term deposits outpacing CASA
Total deposits increased to ₹1,452,100 crore from ₹1,203,500 crore in the year-ago quarter, reflecting 20.7% year-on-year growth. Deposit growth also translated into a 5.8% sequential increase on the end-balance measure. On a quarterly average basis, total deposits grew 22.5% year-on-year to ₹1,396,400 crore. Deposit mix remains a key theme: CASA deposits rose 10.6% year-on-year to ₹529,600 crore, indicating a slower pace than overall deposits. Term deposits, by contrast, climbed 27.3% year-on-year to ₹922,500 crore. This mix shift is important because it can influence funding costs and, in turn, net interest margins.
FCNR(B) mobilisation complicates reported growth
Axis Bank stated it mobilised FCNR(B) deposits aggregating USD 10.62 billion, equivalent to approximately ₹101,800 crore, through the Reserve Bank of India’s swap facility as of September 30, 2026. The bank also disclosed that loans extended by its international branches to customers as a leveraging facility for placing deposits stood at ₹43,800 crore. Excluding certain loans related to FCNR(B) deposits, adjusted gross advances would have grown 18.8% year-on-year and 5.3% quarter-on-quarter. Similarly, adjusted total deposits would have grown 17.0% year-on-year and 2.6% sequentially. Axis Bank also indicated that, on this adjusted basis, term deposits would have grown 21.3% year-on-year and 3.2% quarter-on-quarter as of September 30, 2026. These disclosures put the focus on “clean” growth, separate from the mechanical effects of swap-linked mobilisation.
Q2FY27 results preview: profit seen up 37%–43% YoY
Brokerages expect Axis Bank to report a year-on-year increase in net profit in the 37-43% range for Q2FY27. One projection cited is a 41% rise in net profit to ₹7,180 crore. Mirae Asset Sharekhan estimates profit after tax could increase 36.8% year-on-year to ₹6,962.8 crore, helped by lower credit costs. Motilal Oswal Financial Services (MOFSL) estimates net profit could rise 42.7% year-on-year to ₹7,259 crore. These estimates imply that profitability will be shaped not only by balance-sheet growth but also by credit costs and margin trends.
NIM is the swing factor, with 7–12 bps pressure expected
Margin commentary is likely to be central to the earnings discussion. Analysts expect net interest margins (NIMs) to face pressure due to elevated FCNR(B) deposit mobilisation and higher corporate growth. Mirae Asset Sharekhan estimates NIM may decline 7 basis points quarter-on-quarter to 3.39% in Q2FY27. Another brokerage estimate points to a 12 basis point sequential decline in NIM amid similar drivers. While loan and deposit growth are strong, these margin estimates suggest that earnings quality will depend on whether the bank can stabilise spreads as the funding mix evolves.
Got a follow-up? Ask IRIS
NII, income and operating profit: what estimates indicate
Brokerage estimates suggest mid-to-high single-digit growth in net interest income (NII), alongside double-digit growth in operating metrics. Mirae Asset Sharekhan projects NII to rise 8.4% year-on-year to ₹14,893.9 crore and pre-provision operating profit (PPOP) to increase 11.3% year-on-year to ₹11,586.5 crore. MOFSL pegs total income at ₹21,830 crore and estimates NII at ₹14,919.9 crore, up 8.5% year-on-year. MOFSL also expects operating profit to rise 12.3% year-on-year to ₹11,690 crore. Taken together, the estimates point to an earnings quarter supported by operating momentum, with the margin line remaining the area of debate.
Asset quality expected to stay steady
On asset quality, brokerages expect trends to remain stable during the quarter. MOFSL expects gross non-performing assets (GNPA) to remain flat at 1.3%, with the net NPA ratio unchanged at 0.4%. If these expectations hold, the quarter’s profitability improvements could reflect a combination of operating leverage and controlled credit costs rather than a one-off spike in recoveries. Stability in NPA ratios would also matter because the bank is simultaneously navigating funding-cost pressures.
Market reaction: stock rises after business update
Axis Bank shares reacted positively after the business update. The stock rose as much as 1.8% to an intraday high of ₹1,244.60 on Tuesday, October 6. The move suggests the market acknowledged the strength in headline growth numbers. At the same time, the range of margin estimates highlights why investors are likely to treat the results day as a key confirmation event. The provisional update has provided balance-sheet direction, but it has not resolved the question of how quickly margins can recover.
Key data points at a glance
What to watch on October 17
The September quarter results will likely revolve around three connected issues: the extent of NIM compression, the sustainability of underlying growth excluding FCNR(B)-linked effects, and confirmation of stable asset quality. The bank’s provisional numbers show strong balance-sheet expansion, but the slower growth in CASA relative to total deposits and the surge in term deposits suggest higher funding costs could remain a constraint. Broker estimates already factor in a 7-12 bps sequential NIM decline, so the market may respond to any indication that margins are stabilising faster or slower than expected. With the bank stating the business figures are provisional and subject to limited review, the final audited disclosures will be the definitive reference point. Axis Bank is scheduled to publish its Q2FY27 earnings on Saturday, October 17, which will provide full financials, segment details, and management commentary.