










Bagmane REIT projects sub-5% vacancy in core markets
Key highlights
- Outer Ring Road vacancy is forecast at 4.3% in 2028E, compared with 9.6% in 2023.
- Outer Ring Road leasing is projected at 13.5 msf in 2028E against 2.5 msf of supply.
- Secondary Business District City supply is projected to fall from 2.9 msf in 2026E to 0.3 msf in 2028E.
- Bagmane REIT portfolio micro-markets recorded a 5.2% rental CAGR from CY2021 to Q3 CY2026.
powered by IRIS
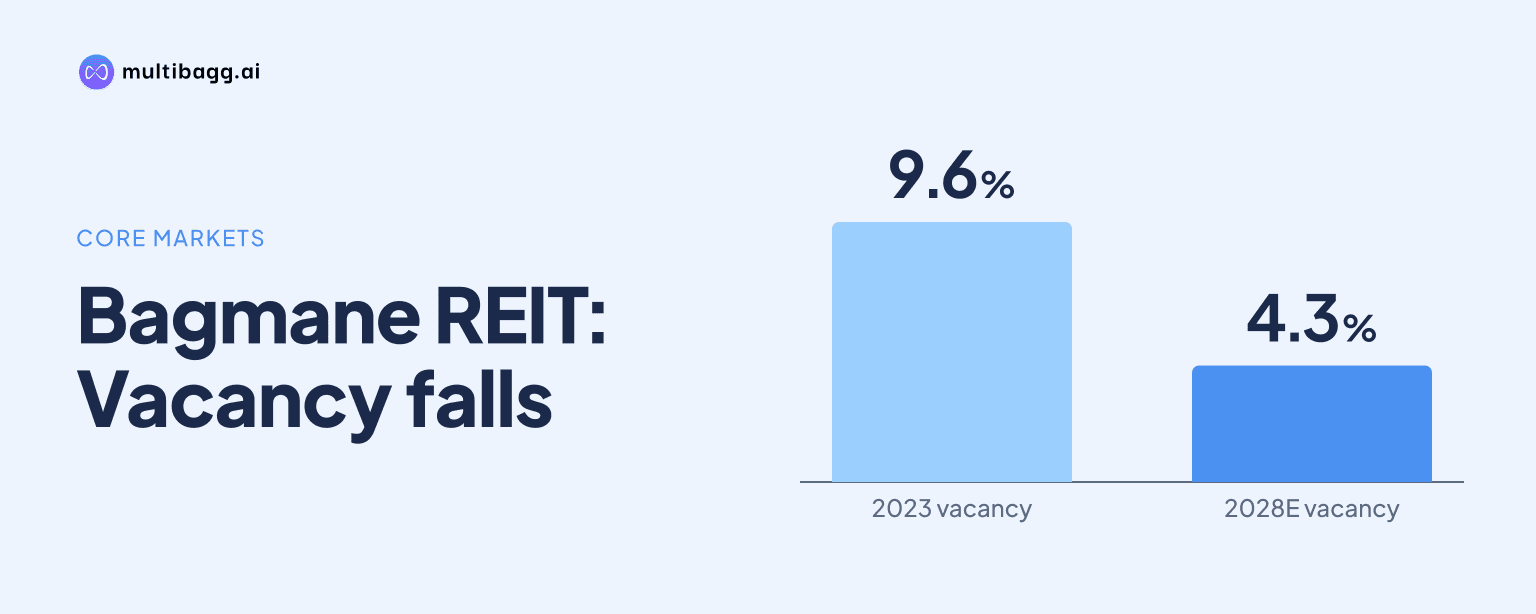
Bagmane REIT projects 2028E vacancy of 4.3% in Outer Ring Road and 4.8% in Secondary Business District City, supported by forecast leasing exceeding supply in both Bengaluru micro-markets. Outer Ring Road is projected to record 13.5 million square feet of gross leasing against 2.5 million square feet of supply in 2028E.
Know Bagmane Prime Office REIT inside out
Results, valuation, peers and who's buying, in one view.
What is Bagmane REIT forecasting for Outer Ring Road vacancy?
Bagmane REIT forecasts Outer Ring Road vacancy at 5.2% in 2026E, 4.9% in 2027E and 4.3% in 2028E. The 2028E estimate is 5.3 percentage points below the 9.6% vacancy recorded in 2023, although it is slightly above the 4.1% recorded in 2025. Vacancy declined to 6.1% in 2024 before reaching 4.1% in 2025.
The projected vacancy movement follows a supply increase in 2026E and a reduction thereafter. Gross leasing is forecast to rise from 11.0 million square feet, or msf, in 2026E to 11.6 msf in 2027E and 13.5 msf in 2028E. Supply is forecast at 7.6 msf in 2026E and 7.0 msf in 2027E before falling to 2.5 msf in 2028E.
Outer Ring Road leasing exceeded supply in each reported year from 2023 to 2025. Leasing was 7.9 msf against 5.7 msf of supply in 2023, 11.1 msf against 3.9 msf in 2024, and 10.3 msf against 4.9 msf in 2025. The leasing-supply gap narrowed from 7.2 msf in 2024 to 5.4 msf in 2025, while the 2028E forecast indicates an 11.0 msf gap.
How do leasing and supply shape the Outer Ring Road outlook?
Bagmane REIT expects forecast leasing to remain above supply in Outer Ring Road through 2028E. The surplus is projected at 3.4 msf in 2026E, 4.6 msf in 2027E and 11.0 msf in 2028E. Between 2027E and 2028E, supply is forecast to decline by 4.5 msf while gross leasing is projected to increase by 1.9 msf.
The presentation does not show a straight annual fall in vacancy. Vacancy is projected to rise from 4.1% in 2025 to 5.2% in 2026E, when supply is expected to increase from 4.9 msf to 7.6 msf. It is then projected to fall below 5% in 2027E, with leasing of 11.6 msf exceeding forecast supply of 7.0 msf.
Outer Ring Road rents rose from Rs 100 per square foot, or psf, per month in 2023 to Rs 104 psf in 2024, Rs 114 psf in 2025 and Rs 120 psf in 2026E. Bagmane REIT calculates a compound annual growth rate, or CAGR, of about 6.1% between 2023 and 2026E. The presentation provides no rent estimates for 2027E or 2028E.
Got a follow-up? Ask IRIS
What is Bagmane REIT forecasting for Secondary Business District City?
Bagmane REIT forecasts Secondary Business District City vacancy of 5.2% in 2026E, 5.0% in 2027E and 4.8% in 2028E. The 2028E estimate is 1.0 percentage point below the 5.8% level recorded in 2024. Vacancy was 3.0% in 2023 and eased from 5.8% in 2024 to 5.5% in 2025.
Supply is forecast to moderate sharply after 2026E in Secondary Business District City. Supply is projected at 2.9 msf in 2026E, followed by 0.5 msf in 2027E and 0.3 msf in 2028E. Gross leasing is expected to decline from 3.4 msf in 2026E to 2.1 msf and 1.5 msf, respectively, but it remains above supply in both forecast years.
In 2025, gross leasing of 3.1 msf was close to supply of 2.9 msf, a difference of 0.2 msf. For 2026E, Bagmane REIT projects leasing of 3.4 msf against the same 2.9 msf supply volume, widening the difference to 0.5 msf. The presentation attributes demand to broad-based occupier expansion across the micro-market.
Secondary Business District City rents increased from Rs 130 psf in 2023 to Rs 138 psf in 2024, Rs 145 psf in 2025 and Rs 155 psf in 2026E. That is a Rs 25 psf increase over three years. Vacancy, however, rose from 3.0% in 2023 to 5.8% in 2024, so the disclosed rent series did not move in line with vacancy in every year.
How do Bagmane REIT's markets compare with Bengaluru?
Bagmane REIT reports a 5.2% rental CAGR for its portfolio micro-markets, Outer Ring Road and Secondary Business District City, from CY2021 to Q3 CY2026. This compares with 5.0% for Bengaluru and 3.8% for India. The portfolio-market rate was therefore 0.2 percentage points above Bengaluru and 1.4 percentage points above India over the disclosed period.
Bengaluru accounted for 26% of India office stock as of September 30, 2026, while its vacancy was about 12%, compared with 15% for India. The city also had the highest average net absorption among the top seven cities from CY2021 to Q3 CY2026 and represented about 39% of India’s global capability centre leasing during that period.
Bengaluru gross leasing rose from 11 msf in CY2022 to 24 msf in CY2025, while supply increased from 12 msf to 15 msf. For CY2026P, Bagmane REIT presents gross leasing of 24 msf and supply of 20 msf. Leasing is projected to increase to 25 msf in CY2027P and 27 msf in CY2028P, against supply of 16 msf and 15 msf.
Conclusion
Bagmane REIT’s outlook for its two core Bengaluru micro-markets depends on leasing continuing to exceed supply. Outer Ring Road has the larger projected 2028E imbalance, with 13.5 msf of leasing against 2.5 msf of supply and 4.3% vacancy. Secondary Business District City is forecast to reach 4.8% vacancy as annual supply declines to 0.3 msf.
The key item to watch is whether the projected supply reduction occurs alongside forecast leasing volumes. Outer Ring Road supply is expected to fall from 7.0 msf in 2027E to 2.5 msf in 2028E, while Secondary Business District City supply is projected to decline from 0.5 msf to 0.3 msf. Bagmane REIT does not disclose rent forecasts beyond 2026E for either market.