










Balkrishna Industries targets Rs 23,000 crore revenue by FY30
Key highlights
- BKT reported FY26 revenue of Rs 10,656 crore and profit after tax of Rs 1,222 crore.
- BKT has set a revenue target of about Rs 23,000 crore by FY30, implying a stated five-year CAGR of about 17%.
- Off-highway tyres contributed about 91% of BKT's FY26 revenue and are expected to account for about 70% of FY30 revenue.
- BKT disclosed achievable tyre output of 360,000 MTPA and carbon black capacity of 265,000 MTPA.
powered by IRIS
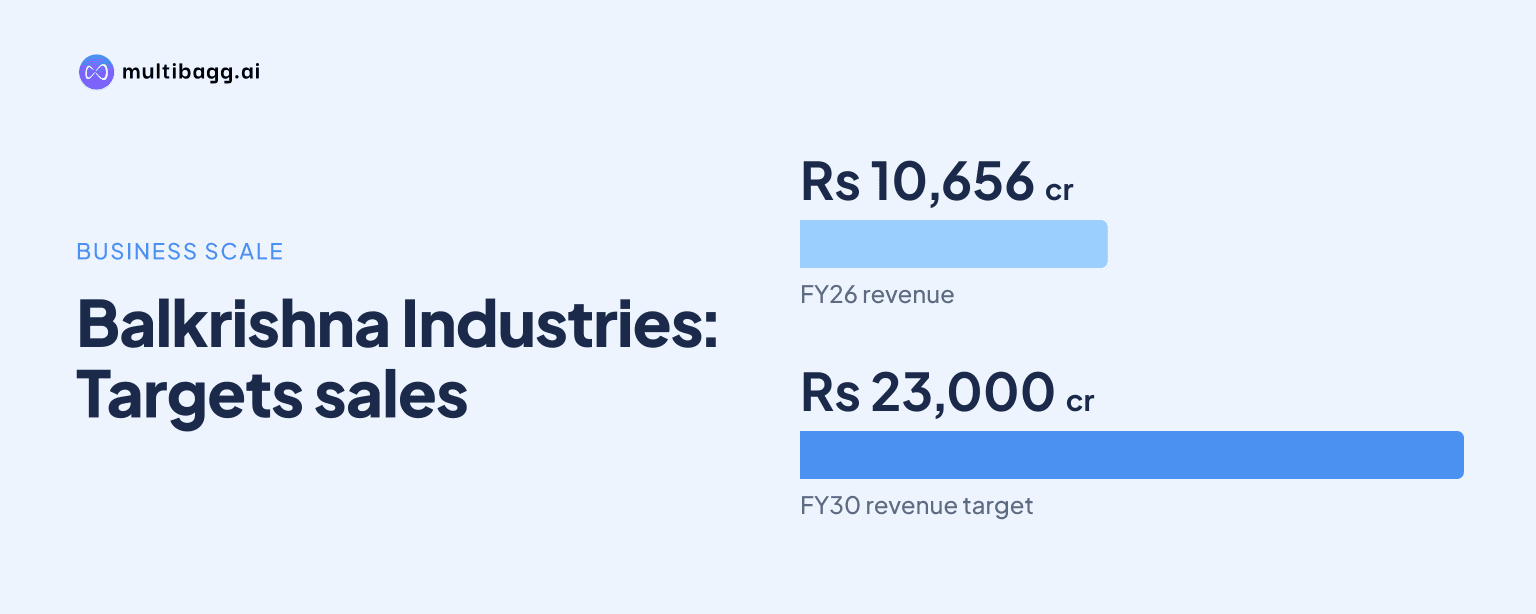
Balkrishna Industries Limited has outlined a target of about Rs 23,000 crore in revenue by FY30, compared with reported FY26 revenue of Rs 10,656 crore, supported by off-highway tyre expansion, new tyre categories for India and carbon black sales.
Know Balkrishna Industries inside out
Results, valuation, peers and who's buying, in one view.
What did Balkrishna Industries disclose in its investor presentation?
Balkrishna Industries Limited, referred to as BKT in its investor materials, disclosed its latest investor presentation under Regulation 30 of the Listing Obligations and Disclosure Requirements regulations on November 4, 2026. The supplied material describes a growth plan that combines its established off-highway tyre business with new tyre categories for the Indian market and third-party sales of carbon black.
The presentation sets out a revenue ambition of about Rs 23,000 crore by FY30. It describes this as 2.2 times the 2025 revenue base and indicates an estimated five-year compound annual growth rate of about 17%. The company has linked the plan to deeper market penetration, a broader product portfolio and strengthening its global brand presence.
The material also refers to strategic manufacturing initiatives, including a proposed greenfield plant in the United States and replacement of the old Waluj plant. The presentation says these initiatives are intended to enhance productivity. However, the supplied disclosure does not provide investment amounts, commissioning schedules or a confirmed capacity figure for the proposed US facility.
Which businesses are expected to support BKT's FY30 target?
BKT expects its core off-highway tyre, or OHT, segments to contribute about 70% of FY30 revenue, while new tyre categories for India are expected to account for about 20%. Third-party sales of carbon black are indicated at about 10% of the target revenue mix.
The company is India’s foremost exporter in the off-highway tyre segment, according to the presentation, with products used in agriculture, construction, mining and industrial applications. It sells into more than 160 countries through a distribution network spanning the Americas, Europe, India and other markets. This overseas reach remains central to the company’s stated growth strategy.
For the Indian new-tyre verticals, BKT has stated an objective of achieving about 5% market share. The presentation does not identify the individual tyre categories, their launch dates or the investment required. Therefore, the disclosed objective should be read as a strategic target rather than a reported operating outcome.
What do BKT's latest disclosed financial figures show?
The presentation reports FY26 revenue of Rs 10,656 crore and profit after tax of Rs 1,222 crore. It also states that the company achieved sales volumes of 317,356 metric tonnes during FY26. Off-highway tyres contributed about 91% of overall revenue during the year.
Management’s operating observations in the material point to a good recovery in Europe during the second half of FY26, improving traction in the Americas and sustained momentum in India. These are qualitative statements from the presentation, and the supplied material does not provide region-wise revenue or volume figures for FY26.
The supplied material also includes a July 2025 quarterly snapshot. For Q1 FY26, it reported sales volume of 80,664 MT, down 3% year on year, revenue of Rs 2,759 crore, up 1%, and EBITDA of Rs 655 crore, down 8%. EBITDA margin was 23.8%, a decline of 228 basis points year on year.
Got a follow-up? Ask IRIS
How does manufacturing capacity fit BKT's expansion plan?
BKT’s manufacturing base is in India, with locations listed at Waluj in Maharashtra; Bhiwadi and Chopanki in Rajasthan; Bhuj in Gujarat; and a mould plant at Dombivli. The presentation places achievable tyre output at 360,000 metric tonnes per annum.
The company also reports in-house achievable carbon black capacity of 265,000 metric tonnes per annum. This includes 30,000 metric tonnes per annum of high-value advanced carbon material. Carbon black is a key input in tyre production, and the company’s capacity is also relevant to its stated plan for third-party carbon black sales.
The planned replacement of the old Waluj plant is described as a productivity initiative. Along with the proposed US greenfield facility, it signals that BKT is considering both domestic manufacturing renewal and a wider international production footprint. The disclosure does not state whether the US facility has received regulatory approvals or whether construction has begun.
What does the presentation mean for investors and the tyre industry?
For investors, the principal disclosed measure is the gap between FY26 revenue of Rs 10,656 crore and the FY30 target of about Rs 23,000 crore. Meeting that target would require execution across the existing OHT business, Indian new-tyre categories and third-party carbon black sales, rather than reliance on a single product line.
The FY26 mix shows the scale of BKT’s dependence on OHT, which represented about 91% of revenue. The proposed FY30 mix indicates an intention to diversify that profile, although OHT is still expected to remain the largest contributor. The company’s business also remains exposed to demand conditions in export markets, particularly Europe and the Americas, which are specifically referenced in the presentation.
The supplied filing contains presentations from different periods, including January 2024, July 2025 and May 2026, alongside the November 2026 announcement heading. Investors should distinguish reported historical financial data from forward-looking targets. The presentation’s safe-harbor language also states that it is for information purposes and is not an offer or recommendation to buy securities.
Conclusion
BKT’s investor presentation outlines a plan to more than double revenue to about Rs 23,000 crore by FY30 from Rs 10,656 crore in FY26. Its stated approach is to retain OHT as the core business while building revenue from Indian tyre categories and external carbon black sales, supported by manufacturing investments and global distribution.
The key items to watch are the company’s progress toward the stated 5% share objective in new Indian tyre verticals, details on the US greenfield plant and Waluj replacement, and the pace of revenue, volume and margin movement in Europe, the Americas and India. The supplied presentation does not disclose timelines or capital expenditure for these projects.