










Belrise Industries Limited merger leaves shareholding unchanged
Key highlights
- Belrise approved the H-One India amalgamation on November 13, 2026.
- H-One India reported turnover of Rs 209.26 crore and net profit of Rs 15.40 crore as on March 31, 2026.
- Belrise reported turnover of Rs 7,528.33 crore and net profit of Rs 478.40 crore as on March 31, 2026.
- The scheme involves no cash consideration, no new shares and no change in Belrise’s shareholding pattern.
powered by IRIS
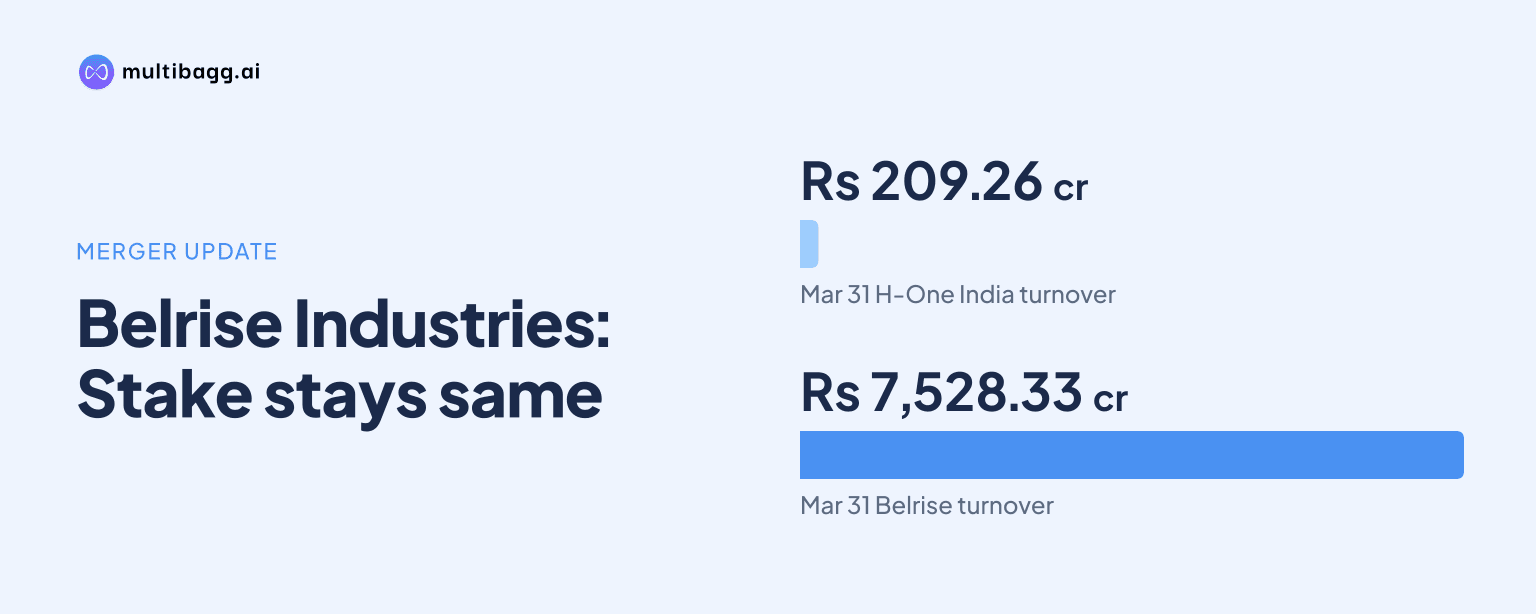
On November 13, 2026, Belrise Industries Limited approved the absorption of wholly owned H-One India Private Limited without cash consideration or new shares, leaving the listed company’s shareholding pattern unchanged; H-One India reported Rs 209.26 crore turnover as on March 31, 2026.
Know Belrise Industries inside out
Results, valuation, peers and who's buying, in one view.
What did Belrise approve on November 13, 2026?
Belrise approved a scheme to amalgamate H-One India with and into Belrise at its board meeting on November 13, 2026. The filing identifies H-One India as the transferor company and Belrise as the transferee company, and says the scheme is proposed under Sections 230 to 232 and other applicable provisions of the Companies Act, 2013.
The November 13, 2026 decision replaces an earlier scheme rather than supplementing it. Belrise’s board rescinded and cancelled the amalgamation scheme it had approved on November 11, 2025, and withdrew the related stock-exchange intimation. The latest board meeting began at 4.05 pm Indian Standard Time and concluded at 5.15 pm.
The announced structure concerns a wholly owned subsidiary, not an acquisition of an outside company. H-One India is 100% owned by Belrise, which is central to the proposed cancellation of the parent’s existing investment and the absence of a share-exchange ratio in the November 13 disclosure.
How large is H-One India compared with Belrise?
H-One India was materially smaller than Belrise on the March 31, 2026 figures disclosed in the scheme. H-One India reported turnover of Rs 209.26 crore, net worth of Rs 207.70 crore and net profit of Rs 15.40 crore, while Belrise reported turnover of Rs 7,528.33 crore, net worth of Rs 5,083.53 crore and net profit of Rs 478.40 crore.
Belrise’s reported turnover exceeded H-One India’s by Rs 7,319.07 crore, and its reported net profit exceeded that of the subsidiary by Rs 463.00 crore. The comparison describes the two legal entities in the proposed amalgamation; the filing does not provide a combined post-merger revenue, profit or net-worth estimate.
H-One India manufactures pressed and welded panels and sub-assemblies for automobiles, serving four-wheelers and two-wheelers. Belrise’s stated product scope is broader, covering safety-critical systems and other engineering solutions for two-wheelers, three-wheelers, four-wheelers, commercial vehicles and agri-vehicles.
Will Belrise pay cash or issue shares for H-One India?
Belrise will not pay cash or issue shares as consideration under the proposed scheme. Because H-One India is already wholly owned by Belrise, the filing says there will be no share exchange, issue or allotment of Belrise shares to H-One India shareholders when the scheme becomes effective.
Instead, all equity shares in H-One India held by Belrise, either directly or through its nominee, will be cancelled and extinguished upon the scheme taking effect. The investment in H-One India shares recorded in Belrise’s books will also stand cancelled without further act or deed, according to the mechanism disclosed on page 4 of the announcement.
Belrise specifically said there will be no change in the shareholding pattern of the listed transferee company. That means the proposal does not create a new equity claim on Belrise or alter the ownership proportions of its existing shareholders through the issue of merger consideration.
The company also said the amalgamation does not fall within related-party transaction requirements. It cited Ministry of Corporate Affairs General Circular No. 30/2014, dated July 17, 2014, under which transactions arising from compromises, arrangements and amalgamations dealt with under specified Companies Act provisions do not attract those requirements.
Got a follow-up? Ask IRIS
Why does Belrise want to amalgamate H-One India?
Belrise says the amalgamation is intended to consolidate businesses in similar automotive-component lines. The company cited the potential to pool financial, marketing, technical, distribution and other resources between H-One India’s automotive panels and sub-assemblies business and Belrise’s safety-critical systems and engineering operations.
Management said the consolidation could support efficient and economical cost management, cost savings, better alignment and streamlined day-to-day operations. These are stated expected benefits of the scheme, rather than quantified savings, profit targets or integration-cost estimates disclosed as of November 13, 2026.
Belrise also cited simplification of the group’s corporate structure, elimination of administrative duplication and rationalisation of administrative expenses and services. The filing says a single-entity structure could reduce multiple legal and regulatory compliances and streamline decision-making across the related operations.
The boards of H-One India and Belrise said they were of the opinion that the scheme was not prejudicial to shareholders, directors, key management personnel, creditors, lenders, employees or other stakeholders. That opinion accompanies the stated rationale for the November 13, 2026 board approval and does not include a quantified assessment of stakeholder effects.
What will change after the Belrise merger becomes effective?
When the scheme becomes effective, H-One India will be amalgamated into Belrise and the subsidiary shares held by the parent will be cancelled. The disclosed legal result is the removal of the intra-group shareholding and the associated investment recorded in Belrise’s accounts, with no cash payment or new-share allotment.
Operationally, Belrise intends to place the related automotive-component activities under one entity. Its filing refers to improved coordination, resource use and human-resource deployment, while H-One India’s pressed and welded panels and sub-assemblies would sit within the wider product coverage described for Belrise.
The November 13, 2026 announcement does not disclose plant-level changes, employee numbers, integration expenses or a date by which the amalgamation must take effect. It also does not state a quantified cost-saving objective, leaving the timing and measurable financial outcome of the consolidation unresolved in this filing.
Conclusion
The proposed amalgamation would remove Belrise’s existing investment in its wholly owned H-One India subsidiary rather than require new financing or equity issuance. The March 31, 2026 figures show that H-One India contributed Rs 209.26 crore of turnover and Rs 15.40 crore of net profit as a separate entity, compared with Belrise’s Rs 7,528.33 crore turnover and Rs 478.40 crore net profit.
The next disclosed point to watch is when the scheme becomes effective, since the cancellation of H-One India shares and Belrise’s corresponding investment occurs only at that stage. Belrise has disclosed the November 13, 2026 approval and cancellation of the November 11, 2025 scheme, but has not provided a timetable, cost-savings target or integration-cost estimate.