










Bilcare auditor flags material going-concern uncertainty
Key highlights
- Bilcare’s auditor said past operating losses create material uncertainty over going concern as of 30 September 2026.
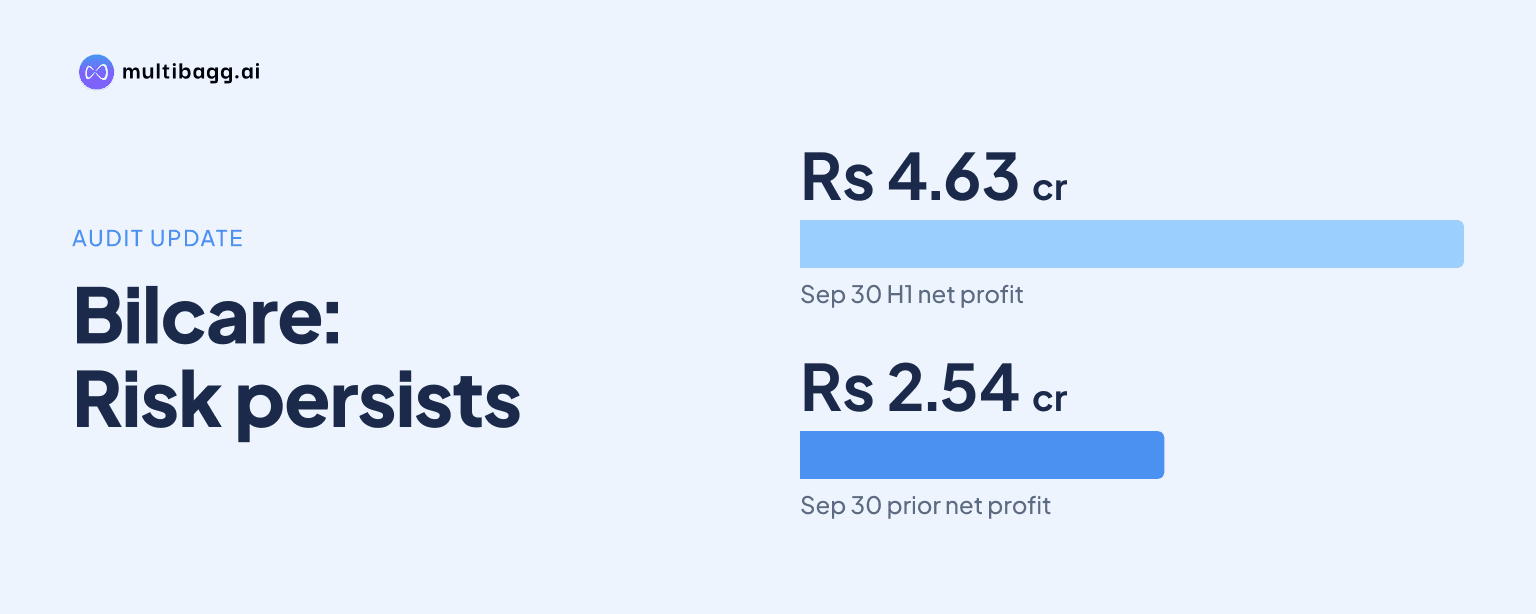
- Bilcare reported standalone net profit of Rs 2.54 crore for the half year ended 30 September 2026, versus Rs 4.63 crore a year earlier.
- Assets held for sale were Rs 64.07 crore at 30 September 2026, unchanged from 31 March 2026.
- Bilcare disclosed Rs 19.41 crore of CSIR-loan penal interest as a contingent liability.
powered by IRIS
Bilcare Limited’s auditor said past operating losses create a material uncertainty that may cast significant doubt on Bilcare’s ability to continue as a going concern, despite an unmodified review of standalone results for the half year ended 30 September 2026, which reported net profit of Rs 2.54 crore.
Know Bilcare inside out
Results, valuation, peers and who's buying, in one view.
What did Bilcare’s auditor say about going concern?
Bilcare’s auditor said operating losses in past years indicate a material uncertainty that may cast significant doubt on Bilcare’s ability to continue as a going concern. The statement was made in the independent auditor’s review report dated 3 November 2026 on Bilcare’s standalone unaudited results for the quarter and half year ended 30 September 2026.
The auditor did not quantify the historical operating losses in its report. It said Bilcare’s continued operation depends on management executing its strategic plans, achieving projected cash flows and delivering future business prospects for the GCS business. The report said management represented a positive outlook for that business when preparing the standalone statements.
Bilcare’s Note 3 says the accounts were prepared on a going-concern basis because of positive prospects, management’s strategic plan for the foreseeable future, cash-flow projections and future business prospects for the GCs Business. Bilcare disclosed one reportable segment, Pharma Packaging Research Solutions, in its 30 September 2026 standalone notes.
Why was Bilcare’s review conclusion unmodified?
Bilcare received an unmodified review conclusion because the auditor said nothing came to its attention suggesting the standalone statement failed to disclose required information or contained a material misstatement. The conclusion covered the half-yearly financial results under Regulation 33 of the Securities and Exchange Board of India, or SEBI, Listing Obligations and Disclosure Requirements Regulations, 2015.
An unmodified review conclusion does not remove the stated going-concern uncertainty. The auditor separately drew attention to the going-concern matter, public fixed deposits, assets held for sale, Rs 19.41 crore of penal interest on a Council of Scientific and Industrial Research, or CSIR, loan, warrants, an ongoing Serious Fraud Investigation Office, or SFIO, investigation and the liquidation of Bilcare Inc on 9 September 2026.
The auditor stated that its work followed Standard on Review Engagements 2410, covering interim financial information, and provided moderate assurance rather than an audit opinion. A review consists principally of inquiries and analytical procedures and is substantially narrower than an audit. The auditor said its conclusion was not modified for the matters listed in paragraph 5 of the report.
Which financial figures frame Bilcare’s going-concern risk?
Bilcare reported standalone net profit of Rs 2.54 crore for the half year ended 30 September 2026, down from Rs 4.63 crore in the corresponding half year ended 30 September 2025. Total income fell to Rs 13.11 crore from Rs 14.09 crore, while total expenses declined to Rs 7.15 crore from Rs 8.40 crore.
The lower half-year profit followed exceptional items of Rs 2.64 crore and tax expense of Rs 78 lakh, despite the increase in profit before tax and exceptional items. For the year ended 31 March 2026, Bilcare reported standalone net profit of Rs 99 lakh, compared with Rs 2.54 crore for the six months ended 30 September 2026.
Bilcare’s standalone cash and cash equivalents were Rs 1 crore at 30 September 2026, while trade receivables were Rs 4.08 crore. Trade payables to creditors other than micro and small enterprises rose to Rs 5.32 crore from Rs 1.45 crore at 31 March 2026, according to the standalone balance sheet.
Got a follow-up? Ask IRIS
What must Bilcare deliver to support its going-concern basis?
Bilcare must execute the strategic plans, projected cash flows and GCS-business prospects identified by management and the auditor as conditions underpinning the going-concern basis. The 3 November 2026 filing provides no forecast revenue, financing timetable, GCS order target or date by which those conditions are expected to be met.
Progress on asset disposal is also relevant because Rs 64.07 crore of land parcels remained classified as assets held for sale at 30 September 2026, unchanged from 31 March 2026. Bilcare said the parcels had been capitalised in financial year 2023-24, while the auditor said capital assets planned for sale in financial year 2024-25 continued to carry that classification.
Separate unresolved matters include Rs 19.41 crore of penal interest under the CSIR loan agreement, which Bilcare classified as a contingent liability because the matter is sub judice. Bilcare also remains under SFIO investigation pursuant to a Ministry of Corporate Affairs order dated 3 June 2020; the Bombay High Court disposed of an existing writ petition while allowing a fresh petition, and Bilcare said the financial impact was not ascertainable.
Bilcare transferred Rs 2.93 crore to the Investor Education and Protection Fund on 10 July 2026 following a National Company Law Tribunal, Mumbai order dated 5 June 2026. The transferred sum included Rs 2.34 crore pertaining to Caprihans India Limited, while Bilcare retained statutory-compliance responsibility for the public fixed deposits under the Business Transfer Agreement.
Conclusion
The unmodified review means the auditor did not identify a material misstatement in Bilcare’s standalone half-year results through its review procedures, but it does not negate the explicit material uncertainty over going concern. Bilcare’s Rs 2.54 crore standalone half-year profit and management’s stated positive business outlook sit alongside the auditor’s warning that continuity depends on future execution, cash flows and business prospects.
The next disclosed points to watch are evidence that Bilcare is implementing its strategic plan, generating the projected cash flows and progressing the GCS business prospects cited in the going-concern assessment. Updates on the Rs 64.07 crore assets held for sale, the Rs 19.41 crore CSIR contingent liability and the SFIO investigation would also address matters that remained unresolved at 3 November 2026.