










Biocon biosimilars margin falls to 22% on shipment timing
Key highlights
- Biocon Biosimilars revenue was Rs 2,809 crore in Q2 FY27, up 3% year on year and down 2% quarter on quarter.
- Biocon Biosimilars EBITDA was Rs 623 crore in Q2 FY27, with margin at 22% versus 25% in Q2 FY26.
- Biocon Biosimilars reported H1 FY27 revenue of Rs 5,664 crore, up 9%, and EBITDA of Rs 1,351 crore, up 2%.
- Biocon said its 10-year Brazil Pertuzumab partnership and added Malaysian insulin capacity support long-term and H2 FY27 expectations.
powered by IRIS
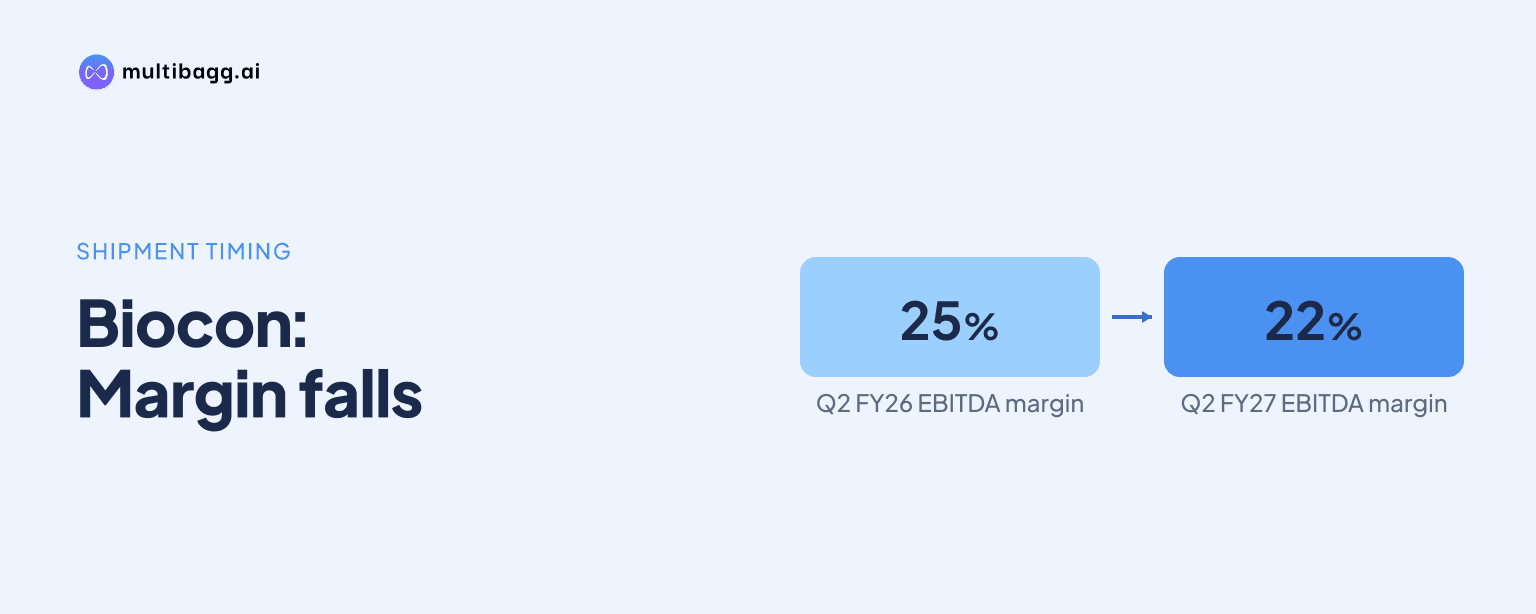
Biocon’s Biosimilars business recorded Rs 2,809 crore of Q2 FY27 revenue, up 3% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) fell 7% to Rs 623 crore and margin narrowed to 22%; Biocon said the timing of revenue recognition on certain shipments affected reported growth and margins.
Know Biocon inside out
Results, valuation, peers and who's buying, in one view.
Why did Biocon Biosimilars’ Q2 FY27 margin decline?
Biocon said the timing of revenue recognition on certain shipments affected the reported Q2 FY27 revenue growth and margins of its Biosimilars segment. The segment generated Rs 2,809 crore in revenue and Rs 623 crore in EBITDA, producing a 22% EBITDA margin in the quarter.
The reported margin was 25% in both Q2 FY26 and Q1 FY27, compared with 22% in Q2 FY27. EBITDA declined by Rs 46 crore from Rs 669 crore a year earlier and by Rs 105 crore from Rs 728 crore in the preceding quarter, while revenue was Rs 46 crore below Q1 FY27 revenue of Rs 2,855 crore.
Research and development (R&D) spending also increased within the segment. Biosimilars R&D was Rs 202 crore in Q2 FY27, 12% higher than Rs 180 crore in Q2 FY26 and 5% above Rs 192 crore in Q1 FY27; it represented 7.2% of quarterly revenue, compared with 6.6% and 6.7% in those respective periods.
How did Biocon Biosimilars perform against other businesses?
Biocon Biosimilars remained the larger of the company’s two biopharmaceutical businesses in Q2 FY27, contributing Rs 2,809 crore of the Rs 3,583 crore biopharmaceutical revenue total. Generics contributed Rs 774 crore, leaving Biosimilars as the principal source of revenue within the biopharmaceutical business during the quarter.
Biosimilars revenue increased 3% year on year but fell 2% sequentially, whereas Generics revenue grew 10% year on year and 2% quarter on quarter. Generics EBITDA increased from Rs 7 crore to Rs 64 crore year on year, while Biosimilars EBITDA decreased from Rs 669 crore to Rs 623 crore.
At the company level, revenue from operations was Rs 4,389 crore in Q2 FY27, up 2% from Rs 4,296 crore in Q2 FY26. Biocon EBITDA was Rs 865 crore, down 7% year on year, and the EBITDA margin declined to 20% from 22%, alongside the Biosimilars segment’s reported margin movement.
Which launches and capacity additions support Biocon Biosimilars?
Biocon said Yesafili delivered an encouraging US launch in Q2 FY27, while Yesintek continued to perform well. These products were the commercial launch drivers cited in the presentation alongside the shipment-recognition timing that affected the quarter’s reported revenue and margin figures.
Insulin demand remained strong, according to Biocon, supported by additional fill-finish capacity commissioned in Malaysia. The company identified this capacity addition as the operating mechanism supporting insulin supply during Q2 FY27.
Biocon also disclosed a 10-year Brazil partnership for Pertuzumab, which it said strengthens long-term revenue visibility. The presentation does not provide an exchange rate for the partnership’s disclosed US-dollar total contract value, so no rupee conversion is stated here; its 10-year duration extends beyond the Q2 FY27 reporting period.
Got a follow-up? Ask IRIS
What does the first half show beyond the Q2 timing effect?
Biocon Biosimilars reported Rs 5,664 crore of revenue in H1 FY27, a 9% increase from Rs 5,179 crore in H1 FY26. H1 EBITDA rose 2% to Rs 1,351 crore from Rs 1,331 crore, although the segment EBITDA margin declined to 24% from 26% over the same periods.
The first-half comparison differs from Q2 because revenue and EBITDA were both higher year on year across six months, despite the reported Q2 shipment-timing effect. However, R&D increased faster than revenue: H1 Biosimilars R&D rose 25% to Rs 394 crore from Rs 314 crore, increasing its share of segment revenue to 7.0% from 6.1%.
Biocon’s broader Biopharmaceuticals division, which includes Biosimilars and Generics, reported H1 FY27 revenue of Rs 7,200 crore, up 11% from Rs 6,511 crore. Biosimilars supplied Rs 5,664 crore of that total and Generics supplied Rs 1,536 crore, with the latter growing 15% year on year, faster than Biosimilars’ 9% growth.
What is Biocon management expecting in the second half of FY27?
Biocon management expects H2 FY27 to be much stronger, supported by launch momentum and additional insulin capacity. This is management’s outlook rather than a revenue or margin forecast, and the presentation does not provide a numerical H2 revenue, EBITDA or margin target.
The factors named for that expectation are Yesafili’s US launch, continued Yesintek performance, strong insulin demand and the Malaysian fill-finish addition. The 10-year Brazil Pertuzumab partnership is a separate long-term commercial arrangement, but Biocon did not state how much revenue it expects to recognise in H2 FY27 from that partnership.
Conclusion
Biocon’s Q2 FY27 Biosimilars results combine 3% reported revenue growth with a 22% EBITDA margin, versus 25% in both Q2 FY26 and Q1 FY27. The company linked the reported growth and margin outcome to revenue-recognition timing on certain shipments, while segment R&D rose to Rs 202 crore and product launches and insulin capacity additions continued.
The next result to watch is whether Biocon management’s expectation of a much stronger H2 FY27 materialises through launch momentum and the added Malaysian insulin fill-finish capacity. Yesafili’s US launch, Yesintek’s performance and the revenue recognition timing on shipments are the disclosed factors that could shape the reported second-half outcome.