










Black Rose Q2 FY27 PAT rises 137% as EBITDA margin reaches 17.9%
Key highlights
- Black Rose reported Q2 FY27 standalone PAT of Rs 10.49 crore, up 136.70% year on year.
- Black Rose's Q2 FY27 EBITDA margin rose to 17.87% from 8.98% in Q2 FY26.
- Distribution EBITDA increased to Rs 6.29 crore in Q2 FY27 from Rs 3.08 crore a year earlier.
- Black Rose said solid PAM commercialisation remains on track for the next financial year.
powered by IRIS
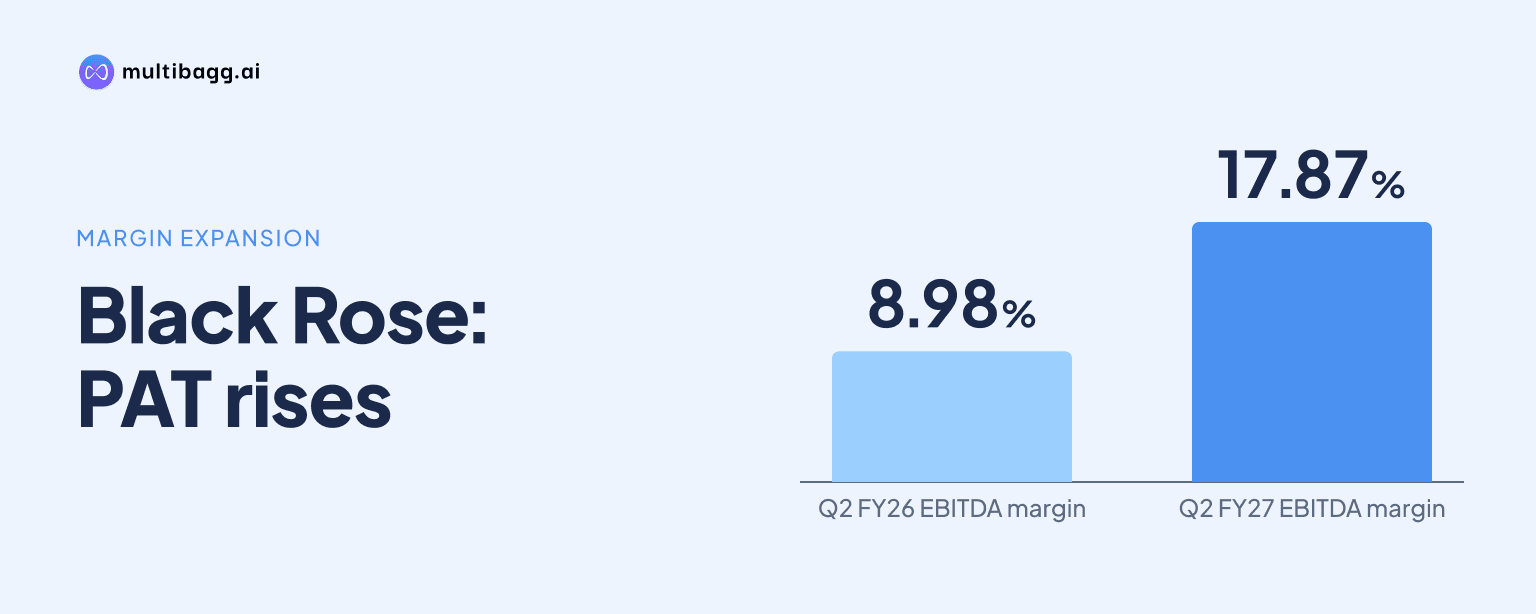
In Q2 FY27, Black Rose Industries Limited's standalone profit after tax (PAT) rose 136.70% year on year to Rs 10.49 crore as earnings before interest, tax, depreciation and amortisation (EBITDA) margin reached 17.87%, from 8.98%. Black Rose recorded 8.23% revenue growth, with improved product realisations and spreads supporting profit growth.
Know Black Rose Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Black Rose perform in Q2 FY27?
Black Rose delivered standalone revenue of Rs 91.25 crore and PAT of Rs 10.49 crore in Q2 FY27, compared with Rs 84.31 crore and Rs 4.43 crore respectively in Q2 FY26. EBITDA increased 107.74% to Rs 15.67 crore, while profit before tax (PBT) rose 134.74% to Rs 14.29 crore. Earnings therefore increased faster than revenue in the year-on-year comparison.
Black Rose's result was also broadly stable sequentially from Q1 FY27, when revenue was Rs 90.14 crore, EBITDA was Rs 15.44 crore and PAT was Rs 10.41 crore. Q2 FY27 revenue was 1.23% higher than Q1 FY27, while EBITDA increased 1.49% and PAT rose 0.78%. The larger change in profitability was therefore against Q2 FY26 rather than between the two FY27 quarters.
Why did Black Rose profit grow faster than revenue?
Black Rose attributed the Q2 FY27 improvement to better realisations and stronger spreads across key product categories, producing EBITDA of Rs 15.67 crore on revenue of Rs 91.25 crore. EBITDA margin increased by 8.89 percentage points from 8.98% in Q2 FY26 to 17.87% in Q2 FY27, while net profit margin rose from 5.28% to 11.96%. That margin movement accompanied PAT growth of 136.70%, compared with revenue growth of 8.23%.
In manufacturing, Black Rose cited better sales realisations, stronger spreads and prudent raw-material planning. Acrylamide liquid volumes were broadly stable from Q1 FY27 but lower than a year earlier, although higher realisations helped maintain revenue. Acrylonitrile, the principal raw material, was largely stable through most of Q2 FY27 before firming towards the end of the quarter and closing at approximately USD 1,560 per metric tonne.
Acrylamide solid was another stated driver, with volume more than doubling from Q1 FY27. Black Rose said elevated logistics costs increased the landed cost of Chinese supplies, while strong demand supported higher realisations and improved spreads year on year. Black Rose describes itself as the only global manufacturer of solid acrylamide outside China, a position it said contributed to the segment's Q2 FY27 performance.
Got a follow-up? Ask IRIS
Which Black Rose segments drove the Q2 FY27 improvement?
Black Rose's distribution division generated the larger share of revenue at Rs 57.78 crore in Q2 FY27, while manufacturing generated Rs 29.50 crore. Distribution EBITDA more than doubled to Rs 6.29 crore from Rs 3.08 crore in Q2 FY26, and manufacturing EBITDA increased to Rs 8.50 crore from Rs 6.01 crore. Manufacturing sales declined from Rs 31.32 crore, but its EBITDA increased by Rs 2.49 crore.
Black Rose's unallocated segment includes administrative and corporate social responsibility expenses. Its distribution-to-manufacturing revenue ratio was 1.96:1 in Q2 FY27, compared with 1.68:1 in Q2 FY26 and 2.39:1 in Q1 FY27. Distribution revenue and profitability improved year on year but moderated sequentially because of lower acrylonitrile volumes and export sales than in Q1 FY27, while N-Methylol Acrylamide volumes declined sequentially amid seasonal weakness and lower offtake from a key customer.
What is Black Rose expecting after Q2 FY27?
Black Rose management expects stable demand across manufacturing's key product segments in the coming quarter, although higher acrylonitrile prices may pressure spreads. Management said the manufacturing outlook is supported by its established market position, diversified customer base and focus on operational efficiency. The approximately USD 1,560 per metric tonne acrylonitrile closing level in Q2 FY27 is therefore a relevant input to the division's stated spread outlook.
For distribution, Black Rose management expects overall performance to improve in the coming quarter, supported by domestic demand and the US oil and gas sector. Management said profitability is expected to remain steady through disciplined execution, principal relationships and a diversified product portfolio. Distribution's Q2 FY27 revenue of Rs 57.78 crore and EBITDA of Rs 6.29 crore provide the latest base for that outlook.
Black Rose said its solid polyacrylamide (PAM) project advanced significantly through the piloting phase and remains on track for commercialisation in the next financial year. Development of downstream products based on acrylamide chemistry is progressing as planned. The proposed specialty amines project with Koei Chemical Company, Ltd. also progressed during Q2 FY27, with an investment decision expected during the year.
Conclusion
Black Rose's Q2 FY27 result combined revenue growth of 8.23% with PAT growth of 136.70%, as EBITDA margin rose to 17.87%. Distribution contributed Rs 6.29 crore of EBITDA and manufacturing added Rs 8.50 crore, despite manufacturing sales being below the Rs 31.32 crore recorded in Q2 FY26.
The next quarter will indicate whether manufacturing can maintain spreads if acrylonitrile prices rise above the approximately USD 1,560 per metric tonne Q2 FY27 closing level. Management has also said solid PAM commercialisation is on track for the next financial year, while an investment decision on the specialty amines project is expected during the year.