










Brigade expects FY27 real-estate EBITDA margin of 22%-24%
Key highlights
- Brigade reported a 24% Q2 FY27 real-estate EBITDA margin, up from 12% in Q2 FY26.
- Management said FY27 real-estate EBITDA margin should remain between 22% and 24%.
- Brigade indicated roughly Rs 5,000 crore of FY27 residential revenue recognition, subject to OCs and registrations.
- Brigade retained Rs 9,000 crore FY27 presales guidance with Rs 7,600 crore of second-half launch GDV planned.
powered by IRIS
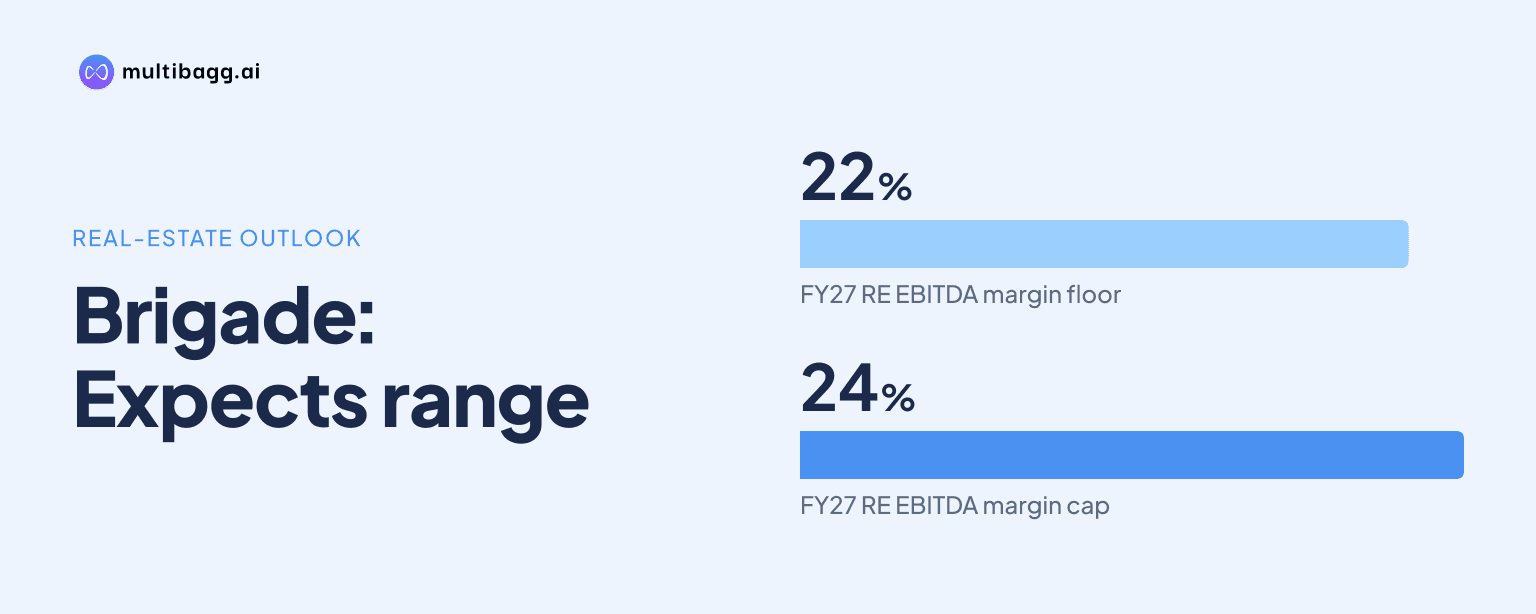
Brigade Enterprises Limited expects its FY27 real-estate EBITDA margin to remain between 22% and 24%, after the segment delivered a 24% margin in Q2 FY27, double the 12% reported a year earlier. Management attributed the improvement to revenue recognition from projects carrying better pricing and margins.
Know Brigade Enterprises inside out
Results, valuation, peers and who's buying, in one view.
What is Brigade's FY27 real-estate EBITDA margin outlook?
Brigade expects its FY27 real-estate EBITDA margin to be between 22% and 24%, according to Chief Financial Officer Yogesh Patel. EBITDA means earnings before interest, tax, depreciation and amortisation. The guidance followed a question on residential revenue recognition, although Patel described the range as the full-year real-estate segment margin profile.
The Q2 FY27 result was already within that band. Real-estate revenue was Rs 760 crore and EBITDA was Rs 178 crore, producing a 24% margin. That compared with a 12% margin in Q2 FY26, while segment EBITDA increased 62% year on year. Brigade did not provide an FY28 revenue or margin forecast, saying the outlook would depend on occupation certificates, or OCs, and registrations closer to that period.
Brigade's consolidated profitability also increased in Q2 FY27, though management identified real estate as the main contributor to the margin change. Consolidated revenue was Rs 1,250 crore and EBITDA was Rs 478 crore, producing a 38% margin versus 26% a year earlier. Leasing, including facility management, generated Rs 242 crore of EBITDA on Rs 329 crore of revenue, while hospitality delivered Rs 59 crore of EBITDA on Rs 161 crore of turnover.
Why did Brigade's real-estate margin double in Q2 FY27?
Brigade said the doubling in real-estate margin reflected the mix of projects reaching revenue recognition, rather than a newly disclosed accounting-policy change. Patel said projects now slated for recognition had secured pricing at a better margin, and that this profile was evident in both Q1 and Q2 FY27. The company said this recognition mix drove the higher real-estate margin within its consolidated performance.
Sales pricing and product mix also moved higher in Q2 FY27. Residential net sales were Rs 1,827 crore across 1.32 million square feet, although presales value was 10% lower than Q2 FY26 because of launch timing. Average realisation increased 29% year on year to Rs 13,841 per square foot, which management attributed to price increases in existing projects and a higher contribution from premium homes.
The recognition-led margin result is separate from the timing of presales. Two-thirds of Q2 residential volume came from sustenance sales in ongoing projects, with the balance from new launches. Brigade launched 2.4 million square feet in Q2 FY27 with estimated gross development value, or GDV, of about Rs 3,000 crore, including Brigade Barcelona in Hyderabad, which recorded Rs 475 crore of launch-quarter sales.
What residential revenue recognition does Brigade expect in FY27?
Brigade indicated FY27 residential revenue recognition of roughly Rs 5,000 crore, subject to OCs and registrations. Patel said full-year revenue should grow year on year, but said those project milestones determine when revenue can be recognised. The Rs 5,000 crore figure is therefore a management indication rather than a reported result or firm forecast.
Brigade retained its Rs 9,000 crore FY27 presales guidance after recording about Rs 2,900 crore in the first half. Management said it was aiming to achieve the remaining roughly Rs 7,000 crore in the second half, supported by Q3 and Q4 launches. It also disclosed Rs 9,800 crore of existing inventory and a further 7 million square feet of planned second-half launches with Rs 7,600 crore of GDV.
The planned launches span several price points and cities. Management said much of the North Bengaluru pipeline is priced at about Rs 1 crore to Rs 1.5 crore, while other Bengaluru projects are near Rs 2 crore and about 20% could be around Rs 3 crore. The two large Bengaluru township projects together have about Rs 3,800 crore of GDV, while the remaining launch plan includes 1 million square feet each in Hyderabad and Chennai, with the balance in Bengaluru.
Got a follow-up? Ask IRIS
What could determine whether Brigade delivers its margin range?
Brigade's stated margin range depends primarily on the timing of OCs and registrations because those events trigger project revenue recognition. Management did not identify a material execution risk for upcoming launches beyond obtaining approvals and starting construction under normal business plans. It also declined to give FY28 margin guidance because of the uncertainty over future OC timing.
Second-half sales and collections are another disclosed dependency. Q2 FY27 collections were Rs 1,633 crore, compared with Rs 2,003 crore in Q2 FY26, including Rs 1,115 crore from real estate. Patel said about Rs 250 crore to Rs 260 crore from a September billing milestone remained to be collected, with about Rs 200 crore reflected in higher trade receivables; management expects these inflows and sales-led collections to support higher second-half operating cash flow.
The Q3 and Q4 launch timetable may also affect the sales conversion needed to support the year. Brigade said one of two large Bengaluru township projects should launch in Q3, while the second could shift into Q4. Of two Chennai projects under consideration, management included only one in the disclosed 7 million-square-foot second-half pipeline and said the other could move into the next financial year.
How do launches support Brigade's FY27 presales target?
Brigade expects a larger share of second-half sales to come from launches than in the first half because Q1 FY27 had no launches. Management said 80% of first-half sales came from sustenance sales, whereas the remaining sales required for the second half should have a greater launch contribution. It said project launches can produce a greater share of total GDV absorption at the initial sales stage.
Brigade Barcelona illustrates the different pace of absorption across projects. The Hyderabad project generated about Rs 450 crore to Rs 475 crore in Q2 FY27 after its late-September launch, and management said it expected another Rs 300 crore to Rs 325 crore of sales in the rest of FY27. That would take full-year sales at the project to about Rs 800 crore, against total inventory of about Rs 2,700 crore.
Management expects higher absorption for some upcoming projects in the Rs 1 crore to Rs 2 crore price range, particularly in Bengaluru and Chennai. It retained the Rs 9,000 crore presales target on that basis, while noting that approvals remain necessary before projects can be launched. The disclosed second-half pipeline contains 7 million square feet and Rs 7,600 crore of GDV, compared with 2.4 million square feet launched in Q2 FY27.
Conclusion
Brigade's 22% to 24% FY27 real-estate EBITDA margin outlook is based on a 24% Q2 FY27 margin, compared with 12% a year earlier, and management's view that the projects entering revenue recognition secured better pricing. The outlook sits alongside an approximate Rs 5,000 crore indication for FY27 residential revenue recognition, which remains dependent on OCs and registrations rather than bookings alone.
The next items to watch are the planned Q3 launches of two Bengaluru township projects, although one may move to Q4, and the conversion of second-half sales into collections. Brigade has retained Rs 9,000 crore of FY27 presales guidance and plans Rs 7,600 crore of GDV from 7 million square feet of second-half launches, making approvals, launch dates and recognition milestones relevant to the remaining FY27 outcome.