










Cedaar Textile Limited auditors flag going-concern uncertainty
Key highlights
- Cedaar Textile’s scheduled loan instalment and interest defaults had continued since January 2026 and remained unpaid on September 30, 2026.
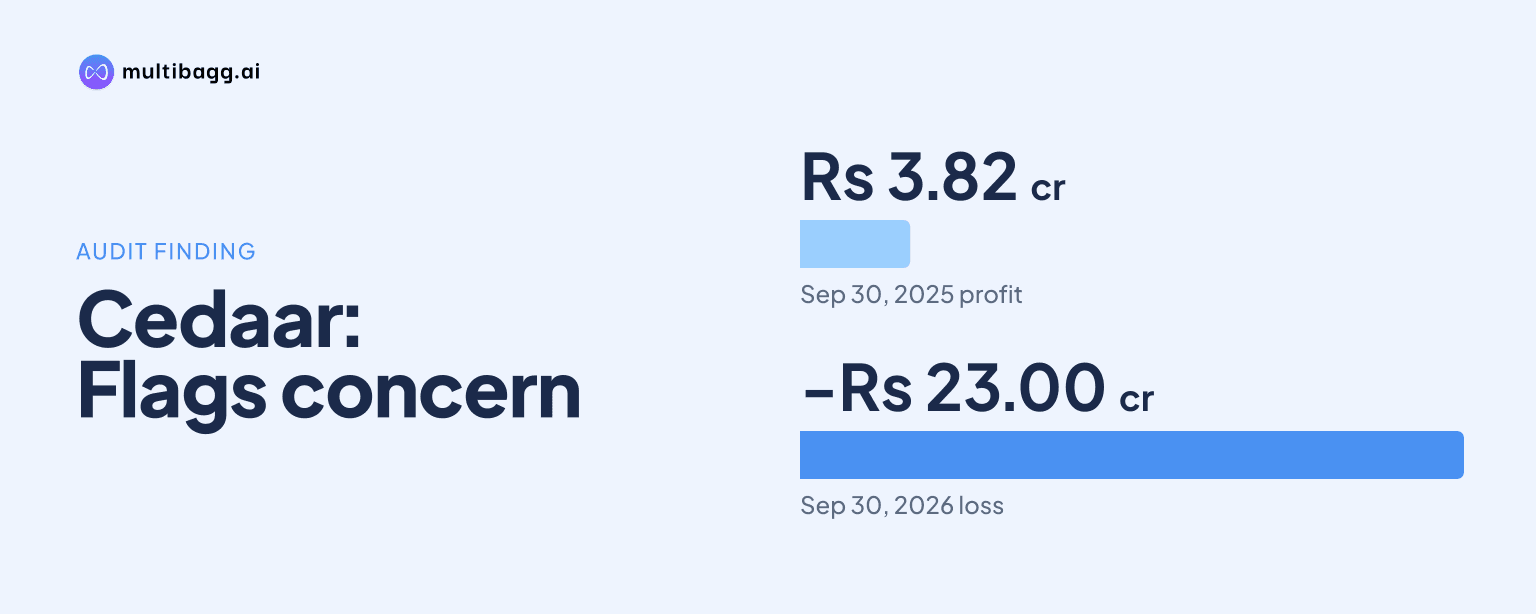
- Cedaar Textile reported a Rs 23.00 crore loss for the six months ended September 30, 2026, against a Rs 3.82 crore profit a year earlier.
- Revenue from operations fell to Rs 36.58 crore in the September 2026 half year from Rs 80.97 crore in the corresponding 2025 period.
- Cedaar Textile reported total borrowings of Rs 104.06 crore at September 30, 2026, versus Rs 107.36 crore at March 31, 2026.
powered by IRIS
Cedaar Textile Limited’s auditors identified material uncertainty over going concern for the half year ended September 30, 2026, after loan defaults continuing from January 2026 and a reported Rs 23.00 crore loss. The auditors also cited unpaid tax, professional-tax and employee-related obligations at the reporting date.
Know Cedaar Textile inside out
Results, valuation, peers and who's buying, in one view.
Why did Cedaar Textile’s auditors raise a going-concern warning?
Cedaar Textile’s auditors raised the warning because scheduled loan instalments and interest had been in default since January 2026, and the overdue principal and interest were still unpaid at September 30, 2026. H B Kalaria & Associates said those continuing defaults, combined with statutory and employee-payment arrears, indicated a material uncertainty that may cast significant doubt on Cedaar Textile’s ability to continue as a going concern.
Cedaar Textile was in discussions with its lender on restructuring its borrowings, according to the review report dated November 14, 2026. The filing does not disclose an approved restructuring, revised repayment terms, the amount covered, lender conditions or a deadline for completing discussions.
The auditors said their conclusion was not modified in respect of the going-concern matter. Their limited review of the September 2026 results stated that nothing had come to their attention to indicate that the statement failed to make disclosures required by Regulation 33 of the Securities and Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015.
Which payments were overdue at Cedaar Textile?
Cedaar Textile had not paid its self-assessment income-tax liability for financial year 2024-25 as at September 30, 2026, despite filing its income-tax return. The auditor’s report does not disclose the value of that liability, associated interest or penalties, or whether an income-tax assessment proceeding had started.
Professional-tax dues covering multiple financial years, salary and bonus payable to employees, and other employee-related liabilities were also outstanding at September 30, 2026. The auditors said these continuing arrears showed Cedaar Textile’s inability to meet statutory and employee obligations within prescribed or agreed timelines.
Other current liabilities were Rs 12.63 crore at September 30, 2026, compared with Rs 45.74 crore at March 31, 2026. That balance-sheet line is broader than the tax and employee obligations specified by the auditors, so the filing does not quantify those overdue items separately.
How did Cedaar Textile’s September 2026 results change?
Cedaar Textile reported a Rs 23.00 crore loss for the six months ended September 30, 2026, compared with a Rs 3.82 crore profit in the corresponding six months ended September 30, 2025. Revenue from operations fell to Rs 36.58 crore from Rs 80.97 crore, while total expenses decreased to Rs 68.20 crore from Rs 81.56 crore.
The September 2026 loss was narrower than the Rs 75.20 crore loss in the preceding six months ended March 31, 2026. Total revenue declined to Rs 36.98 crore from Rs 82.60 crore over those consecutive half years, while expenses declined to Rs 68.20 crore from Rs 178.62 crore.
Finance costs were Rs 4.53 crore in the latest half year, versus Rs 6.08 crore in the September 2025 half year and Rs 3.57 crore in the March 2026 half year. Basic and diluted loss per share was Rs 16.57 for the six months ended September 30, 2026, compared with earnings per share of Rs 3.00 a year earlier; the company stated that these figures were not annualised.
Got a follow-up? Ask IRIS
What do Cedaar Textile’s borrowings and cash flows show?
Cedaar Textile reported long-term borrowings of Rs 33.90 crore at September 30, 2026, up from Rs 20.85 crore at March 31, 2026. Short-term borrowings declined to Rs 70.16 crore from Rs 86.51 crore, taking total reported borrowings to Rs 104.06 crore from Rs 107.36 crore over the six months.
Net cash generated from operating activities was Rs 5.61 crore for the period ended September 30, 2026, compared with net cash used of Rs 31.69 crore for the year ended March 31, 2026. The latest operating figure included reductions in trade receivables of Rs 30.39 crore, inventories of Rs 17.85 crore and short-term loans and advances of Rs 20.96 crore.
Financing activities used Rs 9.10 crore in the six months to September 2026, including Rs 18.57 crore of long-term borrowing repayments and Rs 4.53 crore of finance costs paid. Cash and cash equivalents were Rs 12.34 lakh at September 30, 2026, down from Rs 15.25 lakh at March 31, 2026, under the cash-flow statement prepared using the indirect method under Accounting Standard 3.
What other review limitations did Cedaar Textile’s auditors identify?
The auditors said Cedaar Textile had not carried out an inspection of fixed assets, which prevented them from performing procedures required to obtain adequate assurance on their quantities and condition. Tangible assets were reported at Rs 74.08 crore at September 30, 2026, versus Rs 74.75 crore at March 31, 2026, but the auditors said they could not obtain sufficient appropriate review evidence regarding their existence.
Cedaar Textile recognised inventory write-downs where necessary from an inspection report and recorded the effect in changes in inventories of finished goods, work-in-progress and stock-in-trade. The auditors could not independently verify those write-downs; reported inventories fell to Rs 12.57 crore at September 30, 2026 from Rs 30.41 crore at March 31, 2026.
Cedaar Textile also lacked adequate records to identify and separate revenue and related information between domestic and overseas geographical segments under Accounting Standard 17, Segment Reporting. The company therefore did not provide the required secondary geographical disclosures, while the auditors said the September 2025 half-year and March 2026 comparative results had been compiled by management and had not been audited or reviewed.
Conclusion
Cedaar Textile’s September 2026 filing links a material going-concern uncertainty to loan-payment defaults from January 2026, unpaid statutory and employee obligations, and a Rs 23.00 crore half-year loss. Revenue from operations declined by Rs 44.39 crore year on year, while the review report also identified evidence limitations concerning fixed assets, inventory write-downs and geographical segment records.
The disclosed next matter to watch is Cedaar Textile’s discussion with its lender on restructuring borrowings. The November 14, 2026 filing provides no revised debt terms or completion date, and it does not set a timetable for settling the FY 2024-25 income-tax liability, professional-tax dues, salary, bonus and other employee-related obligations.