










CESC ReNew deal would lift Purvah Green contracted capacity to 4.9 GWp
Key highlights
- CESC’s proposed ReNew transaction covers 1,411 MWp of operating solar capacity at about Rs 4,859 crore enterprise value.
- Purvah Green’s contracted renewable capacity is shown at 4.9 GWp, including 1.8 GWp of operational assets.
- The acquired solar portfolio is expected to generate about Rs 600 crore of annual revenue, with more than 90% of capacity tied up with SECI.
- CESC links 4.9 GWp of contracted capacity to more than Rs 3,400 crore of annualised revenue and more than Rs 3,000 crore of annualised EBITDA.
powered by IRIS
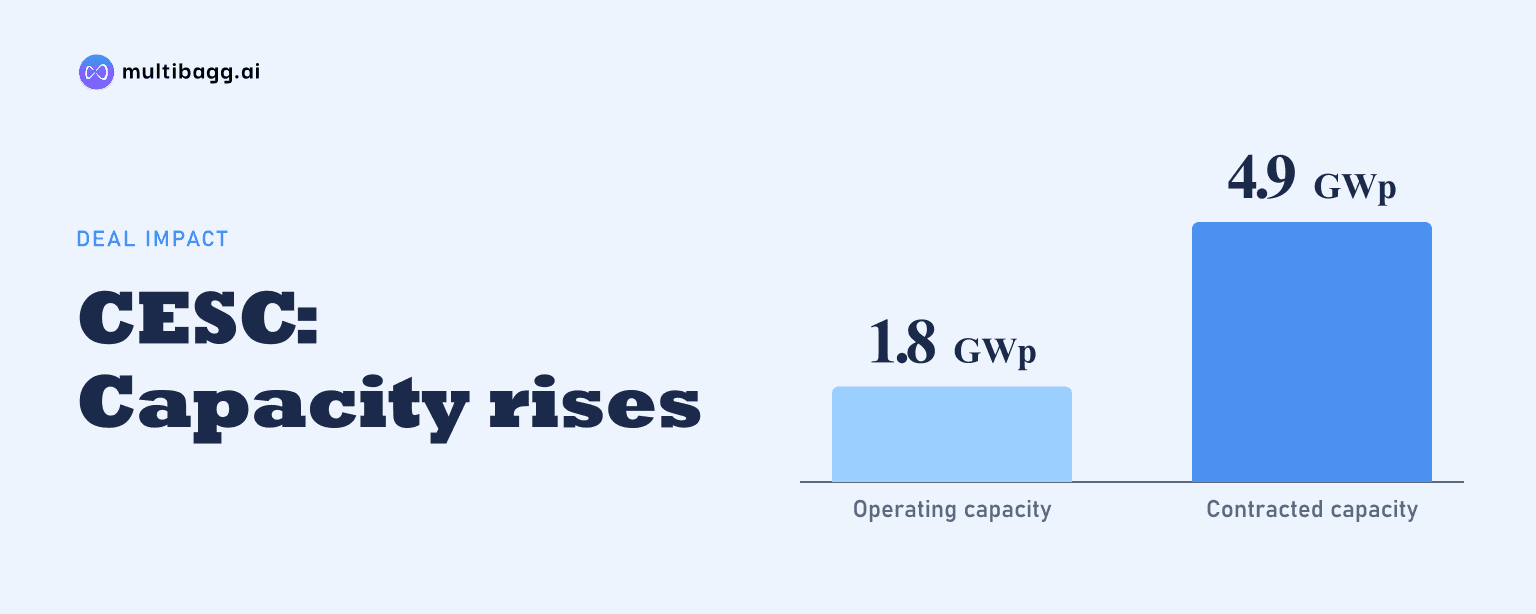
CESC Limited’s proposed acquisition of 1,411 MWp of operating solar assets from ReNew Solar Power would lift Purvah Green’s contracted renewable capacity to 4.9 GWp, including 1.8 GWp of operational assets. The transaction has an enterprise value of about Rs 4,859 crore and is expected to close before 21 November 2026.
Know CESC inside out
Results, valuation, peers and who's buying, in one view.
How does the ReNew transaction change Purvah Green?
The ReNew transaction would provide Purvah Green with operating solar capacity and estimated annual revenue of about Rs 600 crore rather than solely a development pipeline. Purvah Green has signed a share purchase agreement to acquire 100% of six special purpose vehicles from ReNew Solar Power, which together own 1,411 MWp of operating solar projects.
More than 90% of the acquired 1,411 MWp capacity is tied up with the Solar Energy Corporation of India, or SECI. The two Rajasthan projects, Pokhran I with 810 MWp and Pokhran II with 506 MWp, sell power to SECI, while the four Karnataka projects have capacities of 24.6 MWp each.
The acquired projects have different tariff and contract profiles. Pokhran I and II have tariffs of 2.18 rupees per kilowatt-hour and power purchase agreements, or PPAs, valid through FY50, whereas the Karnataka assets have tariffs ranging from 4.76 rupees to 4.86 rupees per kilowatt-hour and PPAs valid through FY42.
The assets also include 4,000 acres of acquired land, although the land and 1,411 MWp capacity remain subject to transaction closure. The portfolio spans two projects in Rajasthan and four projects in Karnataka, giving Purvah Green operating exposure across both states from the proposed closing date.
What will Purvah Green’s portfolio contain after the acquisition?
Purvah Green’s contracted renewable portfolio is shown at 4.9 GWp after the proposed acquisition, split between 1.8 GWp operational and 3.1 GWp under implementation. This combines the acquired solar assets with Purvah Green’s organic renewable development programme.
The 4.9 GWp portfolio comprises 3,515 MWp of solar capacity, 1,385 MW of wind capacity and 2,230 megawatt-hours of battery energy storage system, or BESS, capacity. The presentation separately identifies 4.7 GWp of PPAs signed within its indicative cluster view, while describing 4.9 GWp as contracted capacity.
Purvah Green has applied for connectivity for 10.4 GW, of which 3.8 GW is secured, and has land under acquisition of 15,700 acres. Of that land position, 8,900 acres are described as secured, while the proposed acquired assets would contribute 4,000 acres subject to closing.
The renewable mix includes a commissioned 300 MW CESC Kolkata solar project with 435 MWp installed capacity under a tariff of 2.69 rupees per kilowatt-hour. In comparison, 300 MW hybrid projects for Noida Power and CESC Kolkata are expected in FY27 or FY28, each combining 218 MWp of solar with 300 MW of wind.
Got a follow-up? Ask IRIS
Which projects support Purvah Green’s execution pipeline?
Purvah Green’s disclosed projects span solar, hybrid, wind, round-the-clock, or RTC, and solar-plus-storage contracts, with expected commissioning between FY27 or FY28 and FY30. The nine listed projects have contracted capacity totalling 1,924.5 MW, while installed capacity can exceed contracted capacity because of component oversizing.
The 180 MW REMCL RTC project is expected in FY29 and combines 435 MWp of solar, 250 MW of wind and 900 MWh of BESS at a tariff of 4.35 rupees per kilowatt-hour. A separate 250 MW SECI wind project, also expected in FY29, has a tariff of 3.69 rupees per kilowatt-hour.
FY30 projects include a 300 MW SECI solar-plus-BESS facility with 580 MWp of solar and 600 MWh of storage. The disclosed FY30 set also includes a 175 MW SECI wind project with 30 MWh of BESS and a 70 MW RTC project comprising 218 MWp of solar, 60 MW of wind and 700 MWh of BESS.
The 70 MW RTC project was marked as having received a letter of award, or LoA, while the other listed projects were marked as PPAs signed. CESC also said Purvah Green received LoAs for the 175 MW wind and 70 MW RTC projects in August 2026, and signed a 25-year PPA with Prism Johnson for a 49.5 MW commercial and industrial wind project.
What financial scale and targets does CESC disclose for Purvah Green?
CESC links Purvah Green’s 4.9 GWp contracted capacity to committed capital expenditure of more than Rs 26,000 crore, annualised revenue of more than Rs 3,400 crore and annualised earnings before interest, tax, depreciation and amortisation, or EBITDA, of more than Rs 3,000 crore. These are annualised run-rate indicators for the execution pipeline rather than reported financial results.
The company’s execution schedule shows 2.2 GWp in FY27, including 1.8 GWp of operational assets and 0.4 GWp under implementation. It then identifies an additional 0.7 GWp in FY28E, about 1 GWp plus in FY29E and about 1 GWp plus in FY30E, alongside future bid wins.
Purvah Green reported revenue of Rs 36 crore and EBITDA of Rs 24 crore in Q2 FY27, with a loss after tax of Rs 28 crore. In Q2 FY26, it reported revenue of Rs 62 crore, an EBITDA loss of Rs 4 crore and a loss after tax of Rs 3 crore, showing lower revenue but a positive EBITDA result in Q2 FY27.
At the group level, CESC reported consolidated Q2 FY27 revenue of Rs 5,686 crore, up 6% year on year, while profit after tax was Rs 438 crore, down 2%. The proposed renewable transaction is therefore part of a broader group that reported revenue across distribution, generation and other operations in the quarter.
Conclusion
The proposed ReNew acquisition would add 1,411 MWp of operating solar capacity and about Rs 600 crore of estimated annual revenue to Purvah Green. Combined with its disclosed solar, wind, hybrid, RTC and storage projects, CESC presents the platform as having 4.9 GWp of contracted renewable capacity and 1.8 GWp of operational assets.
The immediate event to watch is transaction closure before 21 November 2026, because the acquired assets and 4,000 acres of land are conditional on completion. Beyond that date, CESC’s disclosed plan calls for 0.7 GWp in FY28E and about 1 GWp plus in each of FY29E and FY30E, against management’s medium-term 10 GW vision.