










Chaman Metallics top-10 customer share fell to 55.91% in Fiscal 2026
Key highlights
- Chaman Metallics' top 10 customers represented 55.91% of Fiscal 2026 revenue, down from 86.71% in Fiscal 2025.
- Top-10 customer sales increased to Rs 302.6108 crore in Fiscal 2026 from Rs 149.3035 crore in Fiscal 2025.
- Rajesh Steel & Wire Industries contributed 9.64% of Fiscal 2026 revenue, down from 24.47% in Fiscal 2025.
- Chaman Metallics had no long-term or exclusive arrangements with customers.
powered by IRIS
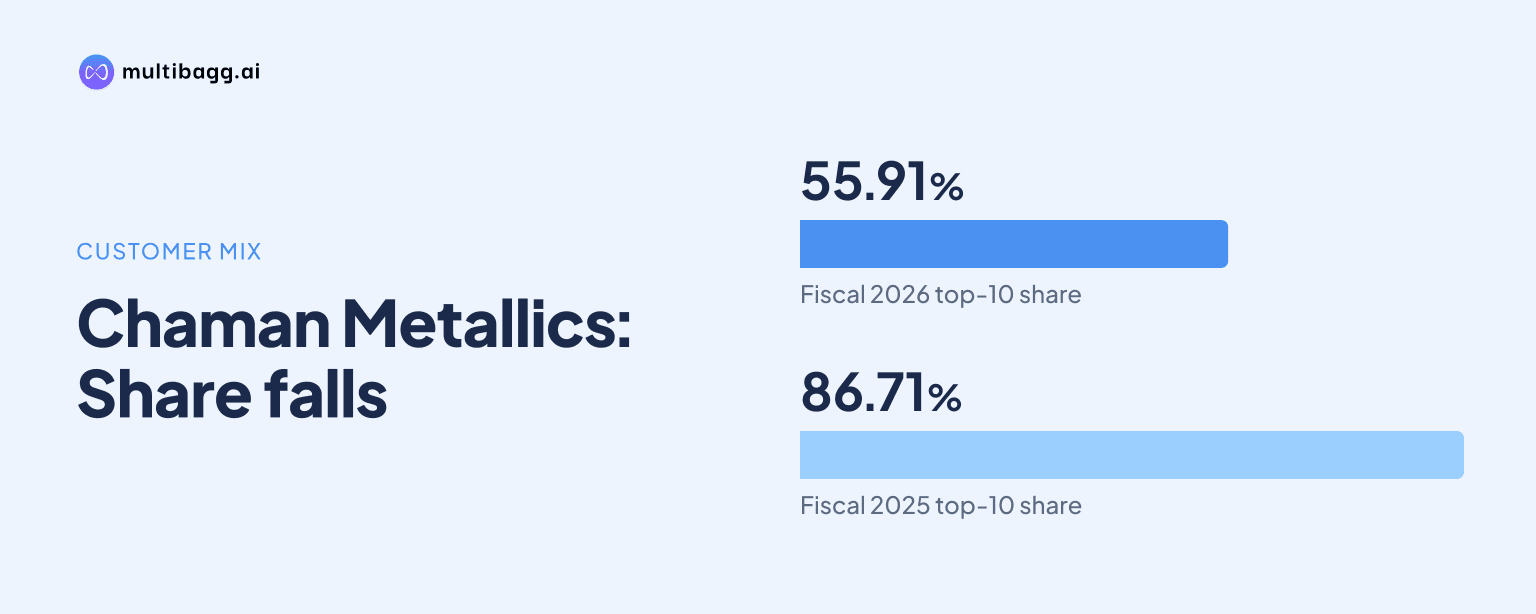
Chaman Metallics Limited reduced its 10-largest-customer share of revenue from operations to 55.91% in Fiscal 2026 from 86.71% in Fiscal 2025, although sales to those customers increased to Rs 302.6108 crore from Rs 149.3035 crore and the company had no long-term or exclusive customer arrangements.
Know Chaman Metallics inside out
Results, valuation, peers and who's buying, in one view.
How much did Chaman Metallics reduce customer concentration in Fiscal 2026?
Chaman Metallics reduced top-10 customer concentration by 30.80 percentage points in Fiscal 2026, as their contribution fell to 55.91% of revenue from operations from 86.71% in Fiscal 2025. In value terms, sales to the 10 customers increased by Rs 153.3073 crore to Rs 302.6108 crore. The lower percentage indicates that revenue outside the top 10 customers increased faster than sales to this group.
The concentration pattern also changed across smaller customer groups. The largest customer accounted for 9.64% of Fiscal 2026 revenue, compared with 24.47% in Fiscal 2025, a decline of 14.83 percentage points. The top three customers generated Rs 147.6639 crore in Fiscal 2026, the top five generated Rs 212.4850 crore, and the top 10 generated Rs 302.6108 crore. Chaman Metallics says its business operations are highly dependent on customers and that losing a major customer could affect sales and results.
Which customers accounted for Chaman Metallics' Fiscal 2026 sales?
Chaman Metallics' largest Fiscal 2026 customer was Rajesh Steel & Wire Industries, which contributed Rs 52.1612 crore, or 9.64% of revenue from operations. SRJ Peety Steels Private Limited was second at Rs 51.6402 crore, or 9.54%, and Gajkesari Steels & Alloys Private Limited was third at Rs 43.8624 crore, or 8.10%. Together, these three customers accounted for Rs 147.6639 crore of revenue.
The fourth- and fifth-largest customers were Metarolls Ispat Private Limited at Rs 39.1306 crore and SRJ Strips and Pipes Private Limited at Rs 25.6905 crore. The remaining five in the top 10 were Shri Maruti Minerals, Vibhum Metallics, G.R. Sponge and Power Limited, Kalika Steel Alloys Private Limited and Shikhara Steels Private Limited. Their individual shares ranged from 4.24% for Shri Maruti Minerals to 2.44% for Shikhara Steels Private Limited.
Rajesh Steel & Wire Industries was also the leading customer in Fiscal 2025, but its share was then 24.47%, compared with 9.64% in Fiscal 2026. SRJ Peety Steels Private Limited's share decreased to 9.54% from 17.34%. Metarolls Ispat Private Limited moved from third place and 10.40% of revenue in Fiscal 2025 to fourth place and 7.23% in Fiscal 2026, while Gajkesari Steels & Alloys Private Limited rose from seventh place and 5.06% to third place and 8.10%.
Got a follow-up? Ask IRIS
Does Chaman Metallics have committed customer contracts?
Chaman Metallics had no long-term or exclusive arrangement with any customer at the offer document disclosure date. The company says customers could place orders on different terms or not place orders at all, including if competitors offer better margins or other incentives. Its disclosure does not identify contractually committed revenue within the Rs 302.6108 crore generated by the top 10 customers in Fiscal 2026.
The company reported no material loss of key customers in Fiscal 2026 or Fiscal 2025. However, it says it cannot assure investors that it will retain these relationships, maintain current business levels, receive payments on time, or replace customers if they are lost. Chaman Metallics says it is seeking to increase its customer base and reduce dependence on particular buyers, while stating there is no assurance it can broaden that base in future periods.
The absence of formal long-term arrangements applies to both customers and suppliers. Chaman Metallics says its ability to maintain satisfactory relationships and consistently provide processing services that meet customer requirements is important to its business. In Fiscal 2026, its sales mix also changed: sponge iron represented 53.07% of revenue from operations, while MS billets and silico manganese, first manufactured in that year, represented 22.41% and 17.68%, respectively.
What does the customer mix show alongside Chaman Metallics' operating results?
Chaman Metallics' lower customer concentration coincided with a wider product mix following its expansion project, but Fiscal 2026 ended with a net loss after tax of Rs 4.1743 crore, versus a net profit after tax of Rs 9.7761 crore in Fiscal 2025. The company attributes the Rs 13.9504 crore decline in profitability primarily to lower sponge iron realisations and higher finance and depreciation costs after commissioning the expansion project.
Average sponge iron realisation fell to Rs 25,740 per metric tonne in Fiscal 2026 from Rs 29,072 per metric tonne in Fiscal 2025. Cost of materials consumed increased to Rs 415.1661 crore from Rs 131.7497 crore, which Chaman Metallics attributes primarily to higher production after the expansion project was commissioned. The disclosure therefore shows that broader customer distribution occurred in a year of different production, product and cost conditions.
Chaman Metallics also reported supplier concentration. Purchases from its top 10 suppliers were Rs 324.9004 crore in Fiscal 2026, representing about 62.38% of total purchases, versus Rs 144.2198 crore and 93.98% in Fiscal 2025. Lloyds Metals and Energy Limited was the largest supplier in both periods, at Rs 215.9022 crore in Fiscal 2026 and Rs 80.24 crore in Fiscal 2025.
Conclusion
Chaman Metallics reduced reported reliance on its 10 largest customers from 86.71% in Fiscal 2025 to 55.91% in Fiscal 2026, while revenue from that group rose from Rs 149.3035 crore to Rs 302.6108 crore. The largest individual buyer's share also declined from 24.47% to 9.64%, showing that revenue was less concentrated among the disclosed leading customers.
The next point to watch is whether management's stated effort to expand its customer base and reduce dependence on particular buyers produces further diversification without long-term or exclusive customer contracts. Chaman Metallics also identifies customer retention, order terms, competition and sponge iron realisations, which declined to Rs 25,740 per metric tonne in Fiscal 2026, as unresolved business factors.