










CIE Automotive India Q3 CY26 Sales Rise 18% YoY
Key highlights
- India sales reached INR 18.0 billion in Q3 CY26, up 18% year-on-year and 9% sequentially.
- Consolidated sales increased 11% year-on-year to INR 25.6 billion, while consolidated EBITDA rose 11% to INR 4.2 billion.
- India’s EBITDA margin declined to 16.3% from 17.3% a year earlier and 16.7% in Q2 CY26.
- India sales grew 16% in the first nine months of CY26, while EBITDA growth was lower at 9% amid cost pressures.
powered by IRIS
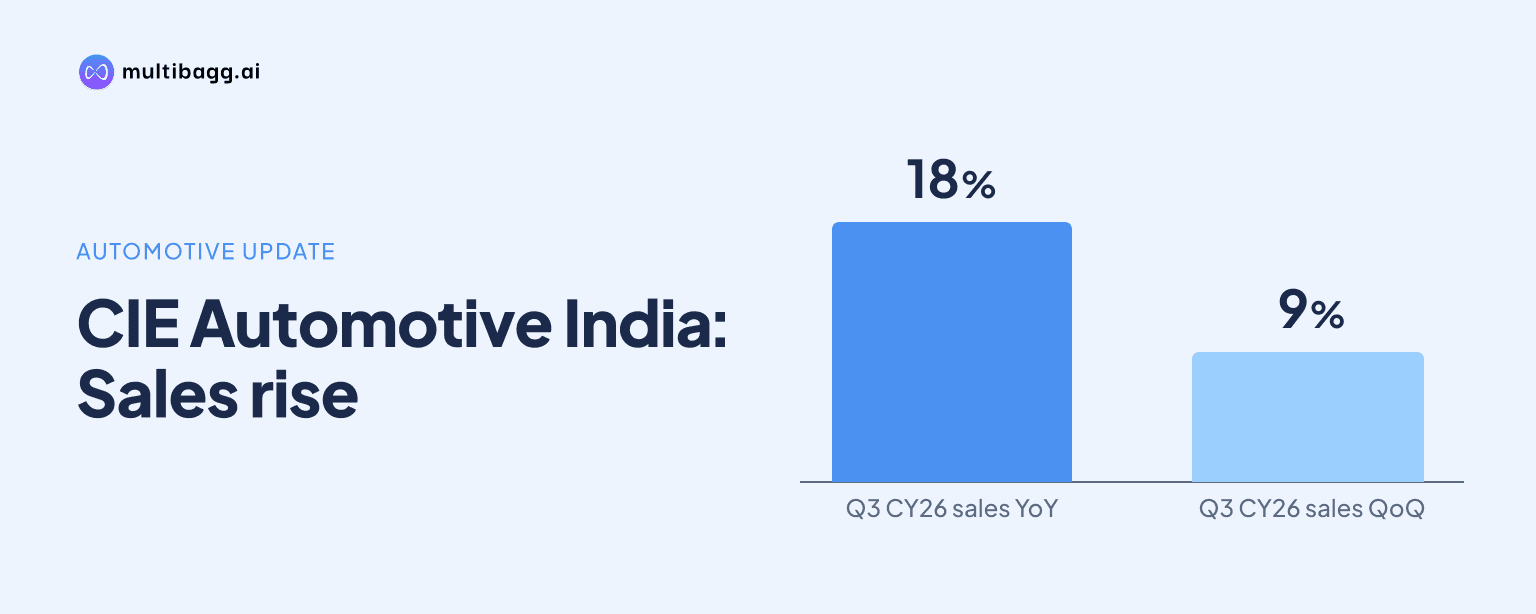
CIE Automotive India reported strong revenue growth in its India operations for the July-September 2026 quarter, supported by demand across automotive segments. India sales reached INR 18.0 billion in Q3 CY26, up 18% year-on-year and 9% sequentially from Q2 CY26. The company said market demand remained robust across segments, although tractor growth slowed appreciably from earlier quarters. Profit growth continued, but the EBITDA margin declined because of higher costs for raw materials, energy and consumables.
Know CIE Automotive India inside out
Results, valuation, peers and who's buying, in one view.
Q3 CY26 India sales performance
Chief Financial Officer K. Jayaprakash said India operations recorded sales of INR 18.0 billion during Q3 CY26. The growth was 18% over Q3 CY25 and 9% over the preceding quarter. The result reflects broad-based demand in the domestic automotive market during the quarter. The company also highlighted that the reported growth rate for the heavy-truck segment differed across data agencies, although even the lower estimate remained strong. The company did not provide a segment-wise sales breakdown in the available call extract.
Consolidated business reported growth
CIE Automotive India reported consolidated sales of INR 25.6 billion for Q3 2026, representing an 11% year-on-year increase. Consolidated EBITDA rose 11% year-on-year to INR 4.2 billion. These reported consolidated figures provide wider context alongside the India operations, where revenue grew faster at 18% year-on-year. The company’s discussion on the call focused on operational demand, margins and investment plans across its Indian business.
EBITDA margin declines to 16.3%
India operations recorded an EBITDA margin of 16.3% in Q3 CY26. This was lower than 17.3% in Q3 CY25 and 16.7% in Q2 CY26. The year-on-year decline was 100 basis points, while the sequential decline was 40 basis points. Management attributed the lower margin to price pressures linked to the conflict in West Asia. It specifically identified inflation in raw materials, energy and consumables as the key drivers.
Earnings growth remained positive
Despite margin pressure, India operations delivered year-on-year growth across key profit measures. EBITDA increased 11% in Q3 CY26, while EBIT rose 12% and EBT increased 10%. The difference between sales growth and EBITDA growth reflects the lower operating margin during the quarter. The disclosed figures indicate that higher revenue supported absolute profit growth even as input costs weighed on profitability ratios.
Key Q3 CY26 financial metrics
Got a follow-up? Ask IRIS
Nine-month performance shows margin pressure
For the first nine months of CY26, sales in the Indian operations grew 16% year-on-year. EBITDA growth over the same period was 9%, while EBIT rose 10%, EBT rose 9% and profit after tax increased 8%. The difference between revenue and profit growth during the nine-month period is consistent with the cost pressure discussed for the third quarter. Management did not disclose absolute nine-month figures in the provided conference-call extract.
Demand outlook and GST effect
Management said it expects relative slowing in market growth over the next few quarters as the effect of GST cuts diminishes. This comment followed a quarter in which demand was described as robust across automotive segments. Tractor growth had already moderated compared with earlier quarters. At the same time, the company said it sees good medium-term growth prospects across Indian market segments despite continuing geopolitical tensions. This outlook is a management assessment and not a financial forecast.
Investment plans across verticals
CIE Automotive India said it is investing in new orders and projects across all verticals. Management stated that overall capital expenditure in India in CY26 will be almost double that of the previous year. The call extract does not state the absolute amount of this planned capital expenditure or provide a project-wise allocation. The investment programme signals continued capacity and programme development activity even as the company manages higher input costs.
What the quarter means for investors
The Q3 CY26 result shows that demand supported meaningful growth in CIE Automotive India’s domestic operations. Sales growth of 18% outpaced the company’s consolidated sales growth of 11%, underscoring the importance of the India business during the quarter. However, the fall in EBITDA margin to 16.3% highlights the sensitivity of profitability to commodity, energy and consumables costs. The company’s next disclosures will be relevant for assessing whether market growth moderates as anticipated and how input-cost pressures develop.
Conclusion
CIE Automotive India closed Q3 CY26 with India sales of INR 18.0 billion, up 18% year-on-year, and positive growth in EBITDA, EBIT and EBT. Margin pressure from higher raw-material, energy and consumables costs remained the principal constraint. Management has indicated continued investment in new orders and projects, with CY26 India capital expenditure expected to be almost double the prior year.