










Coal India earnings mix shifts as ECL returns to profit
Key highlights
- CIL’s consolidated PBT rose 15% to Rs 20,448 crore in H1 26-27 from Rs 17,768 crore a year earlier.
- ECL returned to profit with PBT of Rs 655 crore, reversing a Rs 581 crore loss in H1 25-26.
- NCL’s PBT fell 19% to Rs 5,938 crore, a decline of Rs 1,352 crore year on year.
- CIL’s consolidated PAT increased 19% to Rs 15,397 crore, while EBITDA rose 11% to Rs 25,796 crore.
powered by IRIS
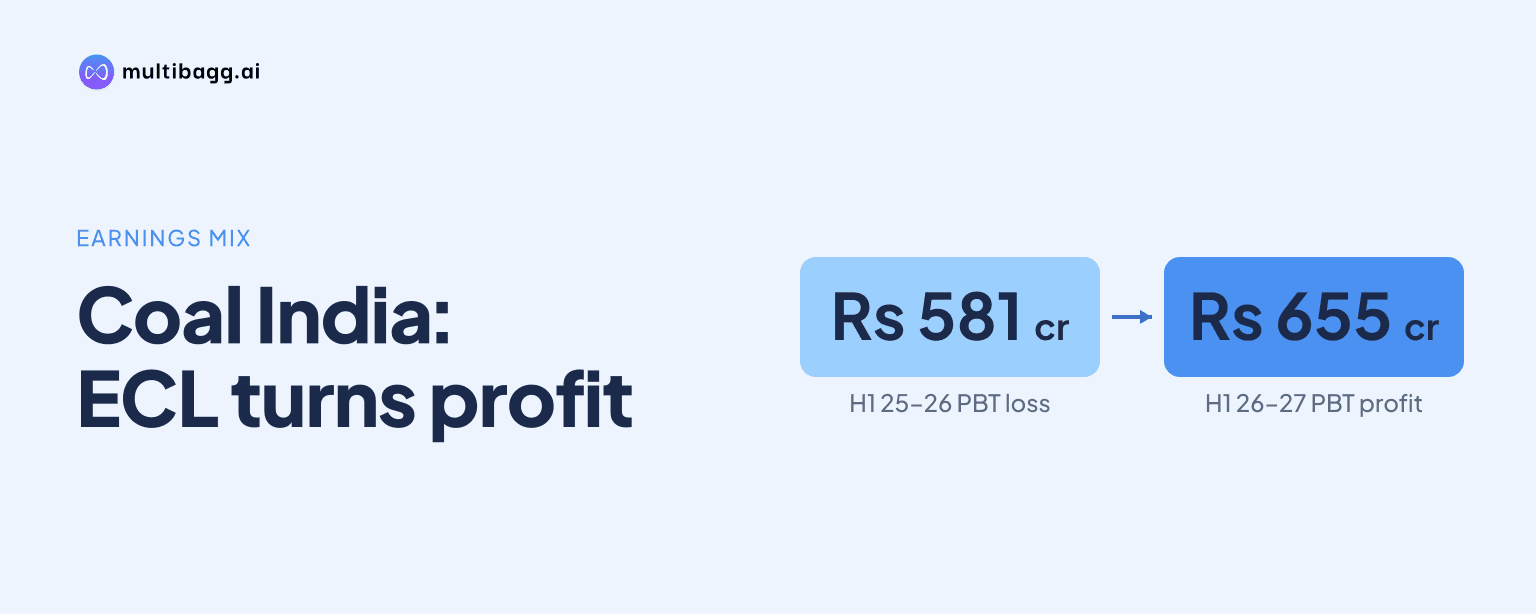
Coal India’s H1 26-27 earnings mix changed as ECL reported profit before tax (PBT) of Rs 655 crore, reversing a Rs 581 crore loss a year earlier. At the same time, NCL’s PBT fell by Rs 1,352 crore, or 19%, to Rs 5,938 crore, while MCL reported the highest subsidiary PBT at Rs 6,575 crore.
Know Coal India inside out
Results, valuation, peers and who's buying, in one view.
Which subsidiaries drove CIL’s H1 PBT change?
CIL’s consolidated PBT increased by Rs 2,680 crore, or 15%, to Rs 20,448 crore in H1 26-27, with ECL’s Rs 1,236 crore turnaround, SECL’s Rs 1,022 crore increase and CCL’s Rs 640 crore increase among the largest positive movements. NCL’s Rs 1,352 crore decline was the largest reduction among the disclosed subsidiaries.
Six operating subsidiaries reported higher PBT, while BCCL and NCL reported lower PBT. MCL delivered the highest PBT among the listed subsidiaries at Rs 6,575 crore, compared with Rs 5,938 crore at NCL, although MCL’s year-on-year increase was Rs 449 crore, or 7%.
The comparison changes the distribution of incremental earnings. ECL’s move from a negative Rs 581 crore to a positive Rs 655 crore was larger than WCL’s Rs 585 crore PBT increase and MCL’s Rs 449 crore increase, whereas NCL moved in the opposite direction despite reporting Rs 5,938 crore of PBT.
How did ECL return to profit in H1 26-27?
ECL returned to profit before tax in H1 26-27, recording PBT of Rs 655 crore after a loss of Rs 581 crore in H1 25-26. The reported improvement was Rs 1,236 crore and the presentation classifies it as a move from loss to profit rather than a percentage increase.
ECL also returned to profit after tax (PAT), reporting Rs 493 crore in H1 26-27 against a Rs 415 crore loss in H1 25-26. Its PAT movement was Rs 908 crore, making ECL the only listed subsidiary with a negative prior-year PAT figure in the disclosed comparison.
The presentation does not identify an operating, pricing, cost or accounting reason for ECL’s reversal. It shows group-level revenue from operations rising 14% to Rs 90,434 crore and expenditure also rising 14% to Rs 75,215 crore, but it does not separate the ECL turnaround from those consolidated movements.
Got a follow-up? Ask IRIS
How large was NCL’s profit decline in H1 26-27?
NCL’s PBT fell 19% to Rs 5,938 crore in H1 26-27 from Rs 7,290 crore in H1 25-26. The Rs 1,352 crore reduction was larger in absolute value than the PBT improvement reported by any individual subsidiary, including ECL’s Rs 1,236 crore turnaround.
NCL’s PAT declined 16% to Rs 4,506 crore from Rs 5,382 crore, a reduction of Rs 876 crore. MCL reported the highest PAT among the named subsidiaries at Rs 4,881 crore, following a 7% increase from Rs 4,574 crore in H1 25-26.
The presentation provides no explanation for NCL’s lower PBT or PAT. NCL’s gross trade receivables were Rs 1,359 crore as of September 30, 2026, compared with Rs 1,128 crore as of March 31, 2026, an increase of Rs 231 crore before adjustments for unbilled incentive and coal quality variance.
Did CIL’s group profit grow despite NCL’s decline?
CIL’s consolidated PAT grew despite NCL’s decline, increasing 19% to Rs 15,397 crore in H1 26-27 from Rs 12,955 crore in H1 25-26. Consolidated PBT rose 15% to Rs 20,448 crore from Rs 17,768 crore as the reported gains at ECL, SECL, CCL, WCL, MCL and CMPDIL exceeded reductions at NCL and BCCL.
Revenue from operations rose 14% to Rs 90,434 crore from Rs 79,473 crore, while sale of product increased 14% to Rs 88,859 crore from Rs 78,155 crore. Other income increased 25% to Rs 4,694 crore, and CIL’s share of joint-venture profit rose 51% to Rs 534 crore from Rs 354 crore.
Earnings before interest, tax, depreciation and amortisation (EBITDA) increased 11% to Rs 25,796 crore from Rs 23,291 crore. EBITDA as a share of revenue from operations remained 29% in both H1 26-27 and H1 25-26, while tax expense rose 5% to Rs 5,050 crore from Rs 4,813 crore.
Conclusion
CIL’s H1 26-27 performance shows a changed subsidiary earnings mix rather than uniform profit growth. ECL’s shift to Rs 655 crore of PBT from a Rs 581 crore loss, together with increases at SECL and CCL, helped raise consolidated PBT by Rs 2,680 crore, while NCL’s Rs 1,352 crore reduction was the principal offset.
What remains unresolved in the presentation is the reason for both ECL’s turnaround and NCL’s lower profit. NCL’s receivables increased by Rs 231 crore between March 31, 2026 and September 30, 2026, while CIL discloses no subsidiary-specific plan, target or scheduled event addressing either movement.