










Concord Enviro Systems restores EBITDA, yet Q2 loss remains
Key highlights
- Concord Enviro reported Q2FY27 revenue of Rs 134.46 crore, up 7.7% year on year.
- Concord Enviro's Q2FY27 EBITDA was Rs 7.78 crore, reversing a Rs 14.94 crore EBITDA loss in Q1FY27.
- Concord Enviro's gross profit margin increased to 57.5% in Q2FY27 from 50.5% in Q2FY26.
- Concord Enviro reported an order book of Rs 716.40 crore as of 30 September 2026.
powered by IRIS
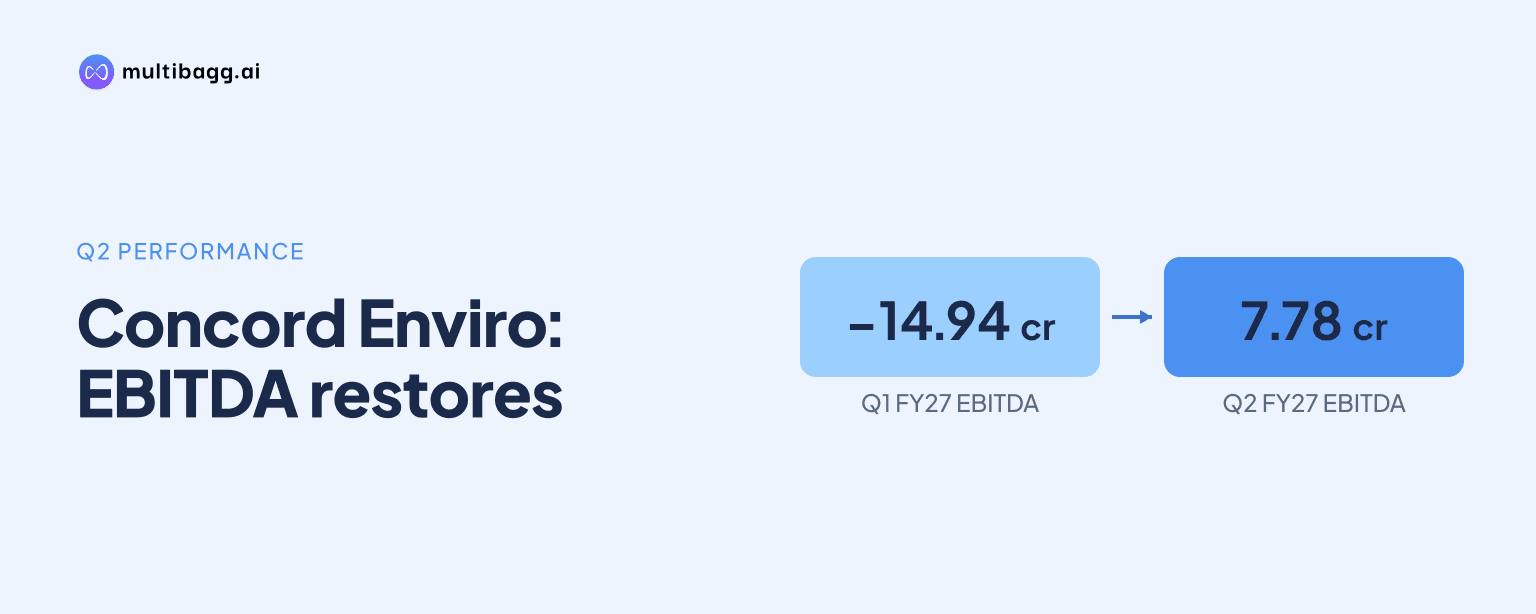
Concord Enviro Systems restored earnings before interest, tax, depreciation and amortisation (EBITDA) to Rs 7.78 crore in Q2FY27 from a Rs 14.94 crore loss in Q1FY27, but recorded a profit after tax (PAT) loss of Rs 4.10 crore despite revenue from operations rising 7.7% year on year to Rs 134.46 crore.
Know Concord Enviro Systems inside out
Results, valuation, peers and who's buying, in one view.
Why did Concord Enviro return to positive EBITDA in Q2FY27?
Concord Enviro returned to positive EBITDA because second-quarter execution improved after supply-chain and logistics disruptions in Q1FY27, according to management. It reported EBITDA of Rs 7.78 crore in Q2FY27, compared with a Rs 14.94 crore EBITDA loss in Q1FY27, and management attributed the turnaround to stronger domestic execution and improved operating leverage.
Revenue from operations reached Rs 134.46 crore in Q2FY27, up from Rs 124.85 crore in Q2FY26. Management said strong domestic demand and execution drove the 7.7% year-on-year increase, while identifying steel, solar manufacturing, chemicals and pharmaceuticals as sectors where underlying demand remained healthy.
Positive EBITDA did not result in a profit for the quarter. Concord Enviro reported a PAT loss of Rs 4.10 crore, with a negative 3.1% PAT margin in Q2FY27; the presentation says PAT and PAT margin include other income, but does not provide a line-item reconciliation from EBITDA to PAT.
How did Concord Enviro's Q2FY27 performance compare with Q1FY27?
Concord Enviro's Q2FY27 revenue was Rs 49.11 crore above Q1FY27 revenue as execution recovered during the second quarter. Revenue from operations rose from Rs 85.35 crore in Q1FY27 to Rs 134.46 crore in Q2FY27, while gross profit increased from Rs 45.63 crore to Rs 77.27 crore.
Gross profit margin increased by 4 percentage points, to 57.5% in Q2FY27 from 53.5% in Q1FY27. EBITDA margin improved by 23.3 percentage points from negative 17.5% to 5.8%, while the PAT loss narrowed by Rs 13.47 crore from Rs 17.57 crore in Q1FY27.
The presentation reports a PAT margin of 20.6% for Q1FY27 alongside the Rs 17.57 crore PAT loss, followed by a negative 3.1% PAT margin for Q2FY27. Concord Enviro does not explain this apparent sign inconsistency in its quarterly comparison, but it states that PAT and the related margin include other income.
How did Concord Enviro's Q2FY27 result compare with Q2FY26?
Concord Enviro delivered higher revenue, gross profit and EBITDA than in Q2FY26, but PAT changed from profit to loss. EBITDA increased 1.6% to Rs 7.78 crore from Rs 7.66 crore, while its EBITDA margin declined to 5.8% from 6.1%, meaning operating earnings rose more slowly than revenue.
Gross profit rose by Rs 14.28 crore year on year and gross profit margin expanded by 7 percentage points to 57.5%. In contrast, PAT moved from a Rs 4.49 crore profit with a 3.6% margin in Q2FY26 to a Rs 4.10 crore loss with a negative 3.1% margin in Q2FY27.
The year-on-year comparison shows that the revenue and gross-profit gains did not carry through to a higher EBITDA margin or positive PAT. Concord Enviro's Q2FY27 presentation reports the operating and net-profit figures, but does not disclose a segment-wise profit split or a detailed explanation for the move in PAT between Q2FY26 and Q2FY27.
Got a follow-up? Ask IRIS
What business activity supported Concord Enviro's second-quarter execution?
Concord Enviro's model combines engineering, procurement and construction projects and system sales with recurring revenue from consumables, membranes, replacement demand and operations and maintenance contracts. The company started a third-party operations and maintenance division in 2024, adding another stated route for service revenue after an initial system installation.
Management linked Q2FY27 revenue of Rs 134.46 crore to domestic execution, while saying international deliveries were being gradually normalised. The presentation does not quantify domestic and international revenue, but it identifies India-led opportunities alongside the need to improve overseas delivery execution after the Q1FY27 disruption.
Concord Enviro also said its H-Xtreme heat exchanger and compressed biogas platform secured their first order milestones during the period. Its dehumidification initiative was operational in Q2FY27 and targets pharmaceuticals, food and beverages, batteries, solar manufacturing and semiconductors.
What should readers watch after Concord Enviro's Q2FY27 results?
Concord Enviro reported an order book of Rs 716.40 crore as of 30 September 2026, which management identified alongside its focus on converting India-led opportunities. The presentation does not disclose the order book's expected delivery schedule, geographic composition, revenue timing or expected margin.
Management said H-Xtreme, industrial compressed biogas, membrane technologies and Reserve were progressing towards commercial scale-up. The company's 2026 milestones also include the H-Xtreme launch, an acquired stake in a membrane technology company and licensed technology in Waha Inc., a US clean-technology company focused on atmospheric water generation and energy-efficient cooling.
India is described by Concord Enviro as its principal growth market over coming years, citing water scarcity, environmental compliance and water-recycling adoption. In the naval market, the company says it is one of four companies selected for green channel certification and estimates it accounts for about 95% of India's naval water-treatment orders; this is a company estimate.
Conclusion
Concord Enviro's Q2FY27 results show a sequential operating recovery, with revenue rising to Rs 134.46 crore, gross profit margin reaching 57.5% and EBITDA returning to Rs 7.78 crore after the Q1FY27 operating loss. The year-on-year picture remains mixed because EBITDA increased only 1.6%, EBITDA margin declined by 0.3 percentage points and PAT shifted from a Rs 4.49 crore profit to a Rs 4.10 crore loss.
The next disclosed markers are execution against the Rs 716.40 crore order book reported on 30 September 2026, the gradual normalisation of international deliveries and commercial progress in H-Xtreme, compressed biogas, dehumidification and membrane technologies. Management's stated plan is to convert India-led opportunities, improve operational efficiency and ramp project deliveries.