










CSU H1 FY27 sales exceed its full-year FY26 sales total in six months
Key highlights
- CSU said H1 FY27 sales exceeded its full-year FY26 sales total.
- CSU average daily sales increased to $61,330 from $32,936 in FY26.
- More than 5,600 unique customers purchased CSU products, 20% more than in FY26.
- USA segment revenue rose to Rs 264.01 crore in H1 FY27 from Rs 213.65 crore in H1 FY26.
powered by IRIS
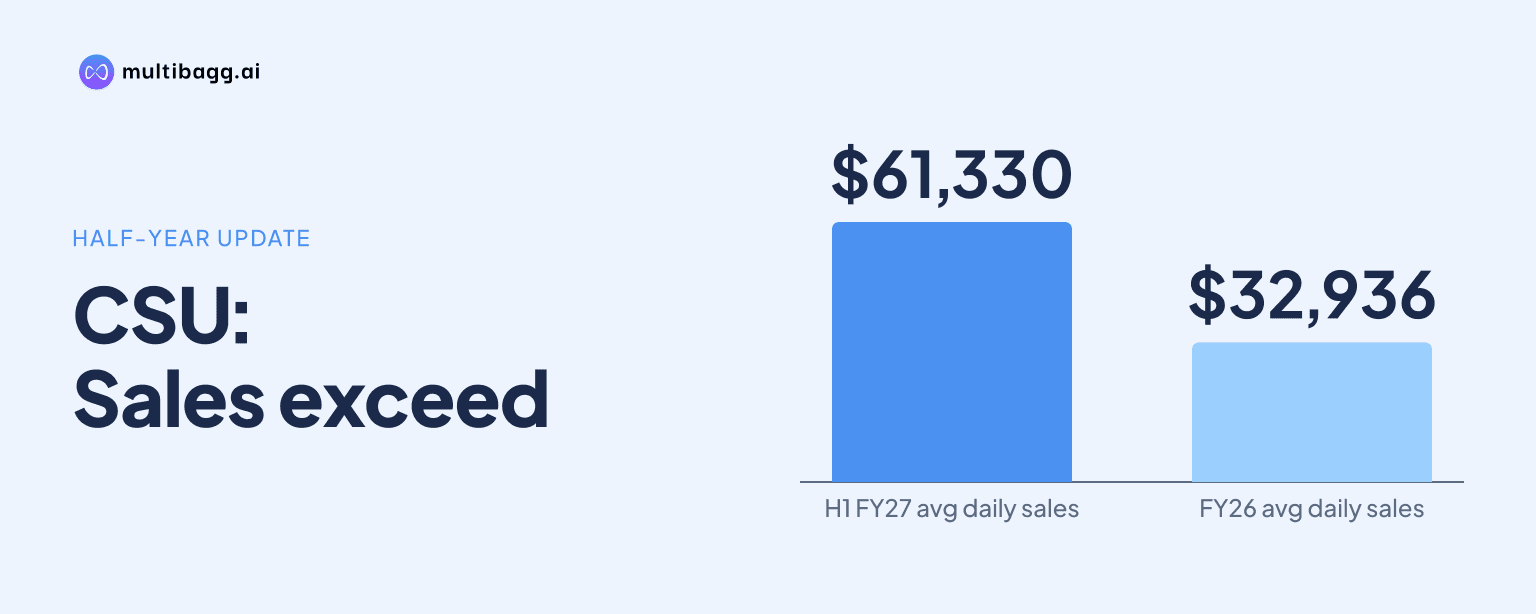
For the six months ended 30 September 2026, Caplin Steriles USA Inc (CSU) reported sales above its full FY26 total, alongside average daily sales of $61,330 and purchases by more than 5,600 unique customers. The own-label US business achieved the milestone in its second full year of operations.
Know Caplin Point Laboratories inside out
Results, valuation, peers and who's buying, in one view.
What did CSU report for H1 FY27 sales?
CSU reported that its H1 FY27 sales exceeded its sales for all of FY26, although Caplin Point Laboratories Limited did not disclose a dollar or rupee sales figure for either period. The comparison covers the six months ended 30 September 2026 against the full financial year ended 31 March 2026, making the reported milestone a sales-run-rate indicator rather than a separately quantified revenue disclosure.
CSU’s average sales per day rose to $61,330 as of the 12 November 2026 announcement, from $32,936 in FY26. This daily-sales measure was nearly double the FY26 level and was disclosed alongside the statement that H1 FY27 sales had outpaced the preceding full year’s sales.
Management said CSU expects to double its revenue and profit over FY26. This is an expectation rather than a reported result, and the filing does not provide CSU’s FY26 revenue, FY26 profit, H1 FY27 profit or a separate margin for the US own-label operation.
What drove CSU’s customer growth in the US?
CSU attributed its progress to a larger customer base and additional direct sales contracts, reporting more than 5,600 unique purchasing customers in its second full year of operations. That customer count was 20% higher than in FY26, though the announcement did not disclose the FY26 customer number, order volumes or average revenue per customer.
CSU added multiple direct sales contracts with large and small integrated delivery networks, or IDNs, in addition to the major US wholesalers. The filing does not state the number of contracts or their duration, but it identifies direct contracts and wholesaler relationships as routes through which CSU reaches US buyers.
Caplin Point said its wider Caplin Steriles Limited (CSL) business had a current revenue mix of 60% business-to-business and 40% business-to-consumer in Q2 FY27. CSU is described as Caplin Point’s own label in the US, but the 60:40 split was not reported as CSU-only data and should not be used as a separate CSU revenue breakdown.
How does CSU fit into Caplin Point’s US operations?
CSU is Caplin Point’s own-label US business within the broader regulated-markets platform that includes CSL. Caplin Point reported US-market total revenue of Rs 271 crore in H1 FY27, up 22.8% year on year, but it did not identify how much of that figure came from CSU.
The consolidated geographical segment table provides a related, but differently reported, view of US activity. USA segment revenue increased by Rs 50.36 crore to Rs 264.01 crore in H1 FY27, while segment result increased by Rs 25.20 crore to Rs 49.59 crore. These figures are for the USA geographical segment, not a CSU financial statement.
Caplin Point’s H1 FY27 geographical revenue mix was about 21% US and 79% emerging markets, comprising Latin America and Africa. The difference between the presentation’s Rs 271 crore US-market revenue figure and the Rs 264.01 crore geographical segment figure means neither should be treated as CSU-only sales.
Got a follow-up? Ask IRIS
What products and capacity plans could support CSU growth?
CSL had launched 40 products in the US as of the Q2 FY27 update and plans to launch 10 further products in FY28. Caplin Point did not state how many of the 40 launched products are sold by CSU, their launch dates, or the sales contribution from each product.
CSL completed exhibit batches for two pre-filled syringe products and had another 12 pre-filled syringe products under active development for FY28 filings. The filing did not give expected approval dates, launch dates or revenues for the two completed batches or the 12 products under development.
Construction of the COL-II facility is scheduled to be completed by August 2027, with capacity for five injectable, ophthalmic and blow-fill-seal lines and provision for three more lines. Caplin Point also said electronic batch manufacturing and packing records were expected within the next few months, after completing a move from physical to electronic logbooks.
The wider capital programme has an approximately Rs 1,000 crore-plus budget, with around 50% of the investments nearing completion as of the November 2026 update. Caplin Point said the projects would be financed through internal accruals and are expected to be completed over the next two years, with full commercialisation expected within one year of each investment’s completion.
Conclusion
CSU’s disclosed H1 FY27 milestone combines sales above the FY26 total with a daily sales rate of $61,330 and more than 5,600 purchasing customers, 20% above FY26. The available data show increased US segment revenue of Rs 264.01 crore, but CSU’s own revenue, profit and margin remain undisclosed, preventing a direct measure of its contribution to the US segment.
The next reported markers include management’s expectation that CSU will double FY26 revenue and profit, 10 planned US product launches in FY28, and completion of the COL-II facility by August 2027. Investors will also be able to assess whether the 12 pre-filled syringe products planned for FY28 filings translate into approvals, launches or separately disclosed US sales.