










Cubical Financial Services stake reaches 34.46% after SPA
Key highlights
- Cubical Financial Services’ combined promoter-acquirer holding rose to 34.46% from 27.55% on 9 November 2026.
- The filing states that 1,00,37,568 equity shares were transferred under a Share Purchase Agreement dated 15 May 2026.
- Cubical Financial Services’ share capital remained Rs 29.034 crore, comprising 14,51,70,000 equity shares, before and after the transfer.
- The detailed table reports a post-transfer holding of 5,00,37,569 shares, creating a one-share difference from the stated acquired quantity.
powered by IRIS
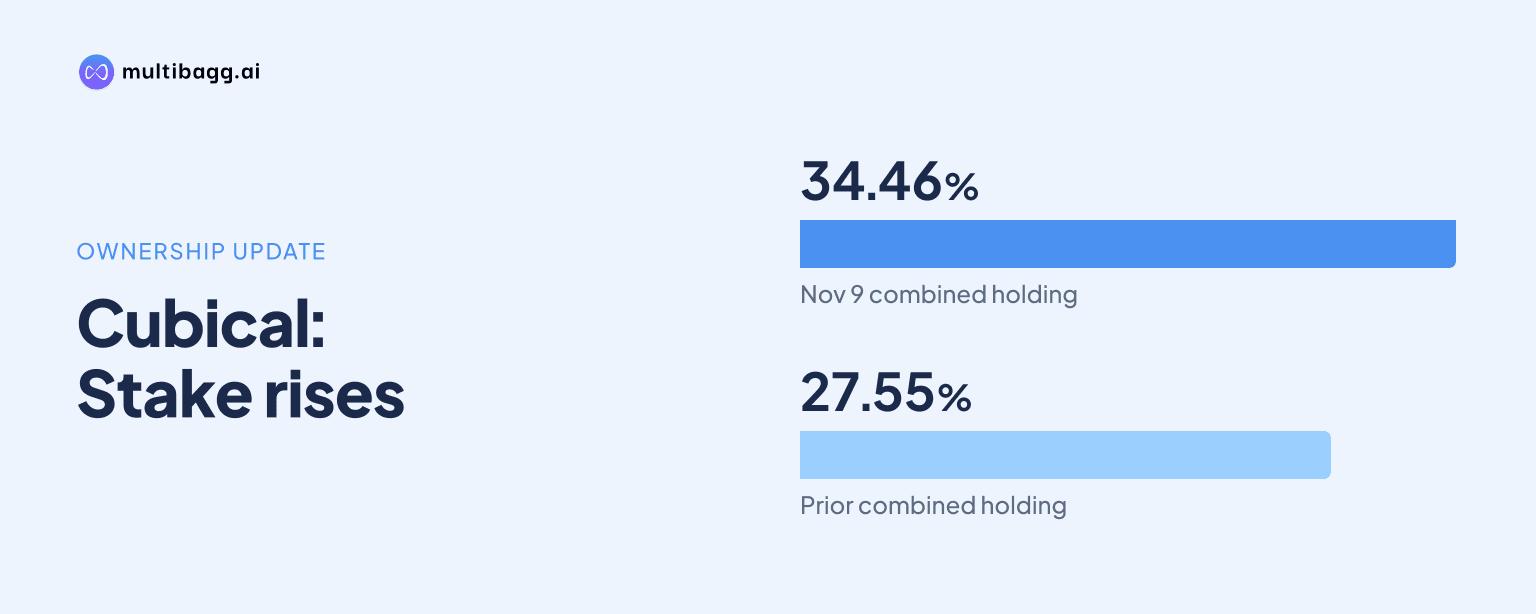
Cubical Financial Services Limited reported that Amit Saraogi and Mrs. Kanchan Saraogi, acting together, increased their voting stake to 34.46% from 27.55% on 9 November 2026 through a Share Purchase Agreement transfer of 1,00,37,568 equity shares. The company’s paid-up share capital remained Rs 29.034 crore before and after the transaction.
Know Cubical Financial Services inside out
Results, valuation, peers and who's buying, in one view.
How did Cubical Financial Services’ ownership change?
Cubical Financial Services’ combined promoter and person acting in concert holding increased by 6.91 percentage points, from 4,00,00,000 shares or 27.55% to 5,00,37,569 shares or 34.46%. Amit Saraogi made the disclosure dated 9 November 2026 under Regulation 29(2) of the Securities and Exchange Board of India (Substantial Acquisition of Shares and Takeovers) Regulations, 2011.
Cubical Financial Services identifies Amit Saraogi and Mrs. Kanchan Saraogi as the acquirer group, with Mrs. Kanchan Saraogi named as a person acting in concert, or PAC. The filing states that the acquirer belongs to the promoter or promoter group. Its 34.46% post-acquisition figure is the same against both total voting capital and total diluted voting capital.
The disclosed increase is based on equity shares carrying voting rights rather than rights attached to other instruments. The pre-acquisition position was 27.55%, while the post-acquisition figure was 34.46%, and both were calculated against 14,51,70,000 equity shares. The form reports no separate voting rights other than through equity shares.
Did Cubical Financial Services issue new shares in the transaction?
No, Cubical Financial Services reported unchanged equity share capital of Rs 29.034 crore, comprising 14,51,70,000 equity shares of Rs 2 each, before and after the 9 November 2026 acquisition. The unchanged capital means the disclosed stake increase resulted from a transfer of existing shares, not from a fresh share issuance reported in this filing.
Cubical Financial Services also reported total diluted share and voting capital of Rs 29.034 crore, or 14,51,70,000 equity shares, after the acquisition. The form defines diluted voting capital as the total shares that would result from full conversion of outstanding convertible securities or warrants. However, no such instruments were reported for the acquirer group before, during or after the transfer.
The acquisition added a reported 6.91% of voting capital while leaving the number of issued equity shares at 14,51,70,000. The comparative figures show that the change was in ownership distribution: the group’s holding rose from 4,00,00,000 shares to 5,00,37,569 shares, whereas Cubical Financial Services’ stated capital did not change.
What was the route and timing of the Cubical Financial Services transfer?
Cubical Financial Services’ acquirer group obtained the shares through a transfer pursuant to a Share Purchase Agreement dated 15 May 2026, with 9 November 2026 recorded as the acquisition date. The filing does not describe the transaction as an open-market purchase, public issue, rights issue or preferential allotment.
The disclosure was addressed to BSE Limited and copied to Cubical Financial Services on 9 November 2026. Its covering letter says the transfer of 1,00,37,568 equity shares represented a change of more than 2% of the company’s total issued and paid-up share capital. The cited Regulation 29(2) concerns disclosure of substantial acquisitions of shares and takeovers.
Cubical Financial Services’ filing does not disclose the purchase consideration, per-share price or seller identity. It also does not specify how the acquired shares were divided between Amit Saraogi and Mrs. Kanchan Saraogi. Therefore, the document establishes the group’s combined 34.46% holding but does not permit calculation of the transfer’s cash value or each individual’s holding.
The acquisition date of 9 November 2026 came nearly six months after the Share Purchase Agreement date of 15 May 2026. The filing records the agreement as the mechanism for the transfer, but gives no further terms of that agreement beyond the acquisition route and dates. It also does not state whether any further transfers under the agreement remain pending.
Got a follow-up? Ask IRIS
What does Cubical Financial Services report on voting rights and encumbrances?
Cubical Financial Services reports that the 34.46% post-acquisition holding consists of equity shares carrying voting rights, with no other voting rights disclosed. The group held 4,00,00,000 voting shares before the transfer and 5,00,37,569 shares afterwards, producing the reported 6.91 percentage-point increase.
Cubical Financial Services reports no encumbered shares before or after the transfer, including no pledge, lien, non-disposal undertaking or other stated encumbrance. The blank categories in the Regulation 29(2) form also show no warrants, convertible securities or other instruments entitling the group to receive voting shares.
The filing presents the 34.46% figure on both an issued-capital and diluted-capital basis. Since both measures use the same 14,51,70,000-share base in the form, the disclosed percentage does not change after considering potential conversion instruments. No quantity or category of conversion rights is listed for the acquirer group.
Why do Cubical Financial Services’ acquired-share figures differ by one share?
Cubical Financial Services’ covering letter and its line for voting shares acquired state 1,00,37,568 shares, while the detailed table’s total acquisition line states 1,00,37,569 shares. The reported post-acquisition holding of 5,00,37,569 shares is arithmetically consistent with adding 1,00,37,569 shares to the pre-acquisition holding of 4,00,00,000 shares.
The one-share difference does not change the percentages shown in the filing. Both acquisition figures are shown as 6.91%, and the post-acquisition position is shown as 34.46%. Cubical Financial Services does not explain whether the difference is a typographical error or a corrected total used in the closing holding figure.
The discrepancy matters because the source records 1,00,37,568 shares in its signed covering letter but uses 1,00,37,569 shares in the acquisition total and after-acquisition holding. The capital base remains 14,51,70,000 shares in both cases, so the difference is too small to change the displayed percentage. It nevertheless leaves the exact transferred quantity unresolved in the disclosure.
Conclusion
Cubical Financial Services’ filing records an SPA-based transfer that increased Amit Saraogi and Mrs. Kanchan Saraogi’s combined promoter-group voting position from 27.55% to 34.46%. The reported increase occurred without a change in Cubical Financial Services’ Rs 29.034 crore equity capital or its 14,51,70,000 issued equity shares.
The next item to watch is any clarification of the one-share inconsistency between the 1,00,37,568 shares stated in the covering letter and the 1,00,37,569 shares used in the detailed acquisition total. The filing does not resolve that difference, although its post-acquisition holding of 5,00,37,569 shares relies on the higher figure.