










Desco Infratech Limited H1 revenue rose 79%, margins narrowed
Key highlights
- H1 FY27 revenue was approximately Rs 75 crore, up 78.52% from Rs 42 crore in H1 FY26.
- EBITDA rose 62.43% to Rs 14.60 crore, while EBITDA margin declined to 19.45% from 21.38%.
- PAT increased about 54% to Rs 9.50 crore, while PAT margin declined to 12.66% from 14.68%.
- City gas distribution generated Rs 49.67 crore of H1 FY27 revenue, and the order book was more than Rs 370 crore.
powered by IRIS
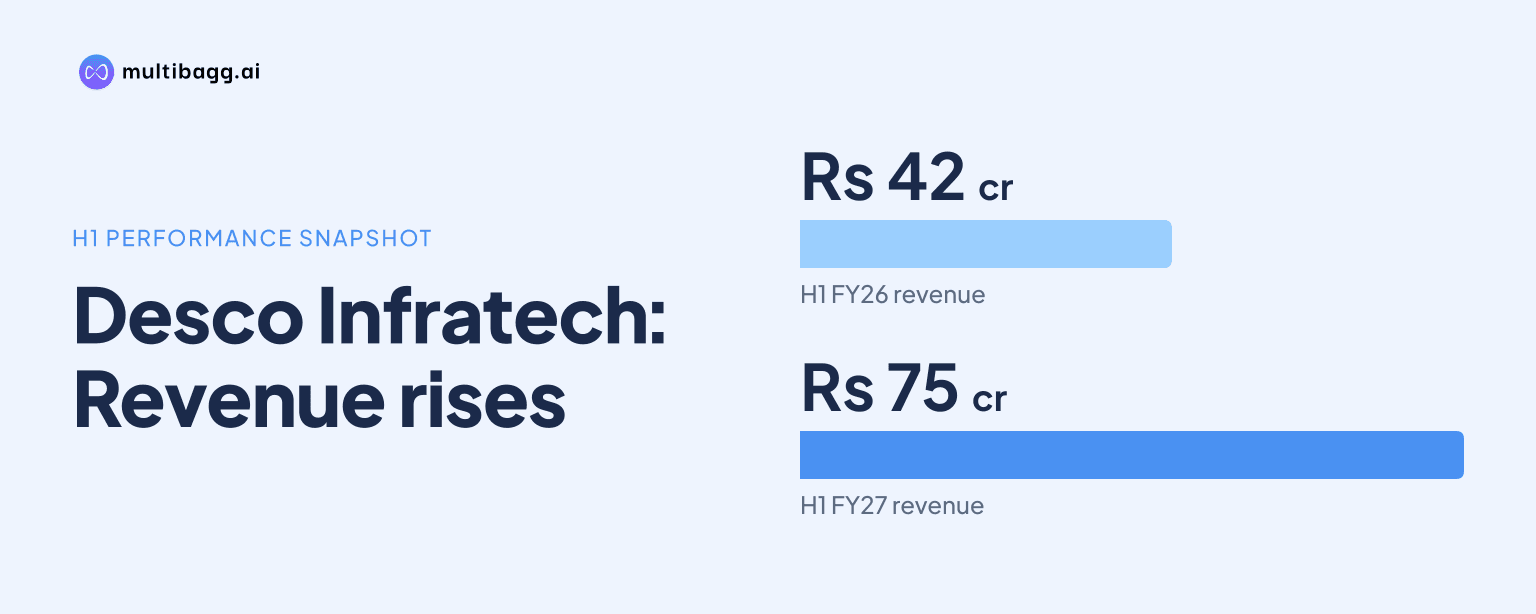
Desco Infratech reported approximately Rs 75 crore of revenue in H1 FY27, up 78.52% from H1 FY26, but EBITDA margin fell to 19.45% from 21.38%. Profit after tax rose about 54% to Rs 9.50 crore, while management identified working-capital efficiency and cash-flow conversion as priorities during project expansion.
Know Desco Infratech inside out
Results, valuation, peers and who's buying, in one view.
How did Desco Infratech perform in H1 FY27?
Desco Infratech increased revenue, EBITDA and profit after tax in H1 FY27, although profit growth did not match the 78.52% revenue increase. Revenue from operations was approximately Rs 75 crore against Rs 42 crore in H1 FY26, while EBITDA rose 62.43% to Rs 14.60 crore and profit after tax rose about 54% to Rs 9.50 crore.
Desco Infratech reported earnings per share of Rs 12.38 in H1 FY27, compared with Rs 8.04 in H1 FY26, also an increase of about 54%. Its debt-to-equity ratio was 0.45 times as of September 30, 2026, providing the balance-sheet measure disclosed alongside the half-year profit figures.
Why did Desco Infratech’s margins narrow despite higher profit?
Desco Infratech’s EBITDA margin declined by 193 basis points and its PAT margin by 202 basis points even as EBITDA and PAT rose in absolute rupee terms. The call transcript does not identify one specific cost or project behind the H1 FY27 decline, but management said margins can vary with project mix, execution schedules, material requirements and other operating factors.
Management said it evaluates projects for commercial viability, execution requirements, customer profiles and expected returns rather than pursuing growth at any cost. That approach matters because H1 FY27 revenue increased by approximately Rs 33 crore year on year, while EBITDA increased by Rs 5.62 crore, resulting in the lower 19.45% EBITDA margin.
Which segments generated Desco Infratech’s H1 FY27 revenue?
Desco Infratech’s city gas distribution business was its largest reported segment in H1 FY27, generating Rs 49.67 crore of revenue and Rs 10.15 crore of segment result. General civil construction services contributed Rs 21.47 crore of revenue and Rs 3.52 crore of segment result, while power distribution contributed Rs 3.89 crore of revenue and Rs 48.72 lakh of segment result.
The compressed biogas segment was at an early stage of development and recorded a loss of Rs 5.09 lakh during H1 FY27. Management described city gas distribution as a key contributor, while power distribution and solar engineering, procurement and construction, or EPC, projects are intended to diversify the revenue base beyond pipeline infrastructure.
Got a follow-up? Ask IRIS
How is Desco Infratech addressing working capital and cash conversion?
Desco Infratech said working-capital management is a priority because infrastructure projects require spending during execution, while billing, certification and collection occur under contractual milestones. Management’s stated measures include timely billing, follow-up on certification of completed work, collection efficiency, and use of available finance and invoice-discounting facilities.
Management said revenue growth alone is insufficient and that it wants to improve conversion of operating performance into cash flow while retaining financial flexibility for projects. On the November 5, 2026 call, it cited an order book of more than Rs 370 crore and a tender pipeline of more than Rs 740 crore, both of which could require execution-related working capital.
What is Desco Infratech targeting for FY27 and beyond?
Desco Infratech management said it remains focused on approximately Rs 190 crore to Rs 200 crore of FY27 revenue, with a significant part of project activity expected in the October-to-March second half. During the question session, management cited an executable order book of approximately Rs 384 crore at different stages of execution as support for that outlook.
For the longer term, management reiterated an ambition to reach Rs 1,000 crore of revenue by FY2030, subject to order inflows, market conditions, execution capability and financial health. Its plans include strengthening city gas distribution, expanding power distribution and solar EPC, developing compressed-biogas initiatives, and exploring oil and gas pipeline opportunities through UAE subsidiary Desco Global FZ-LLC.
Conclusion
Desco Infratech’s H1 FY27 results show rapid expansion, with approximately Rs 75 crore of revenue and Rs 9.50 crore of PAT, but the decline in EBITDA and PAT margins makes the composition and cash realisation of growth central to the result. City gas distribution supplied Rs 49.67 crore of segment revenue, while general civil construction services added Rs 21.47 crore and broadened the operating base.
Next, investors can watch whether the October-to-March execution cycle supports management’s approximately Rs 190 crore to Rs 200 crore FY27 revenue objective, and whether billing and collection measures improve cash conversion. Management also identified the more than Rs 740 crore tender pipeline, more than Rs 370 crore order book and Rs 1,000 crore FY2030 ambition as milestones dependent on disciplined execution and financial health.