










digitide Restores 10.4% EBITDA Margin as PAT Rises 204%
Key highlights
- digitide’s Q2 FY27 EBITDA margin rose to 10.4% from 9.9% in Q1 FY27.
- digitide reported Q2 FY27 PAT of Rs 8.9 crore, up 204.0% quarter on quarter.
- Tech & Digital revenue rose 6.6% year on year to Rs 243.6 crore in Q2 FY27.
- International revenue reached Rs 323 crore, or 42.5% of Q2 FY27 revenue.
powered by IRIS
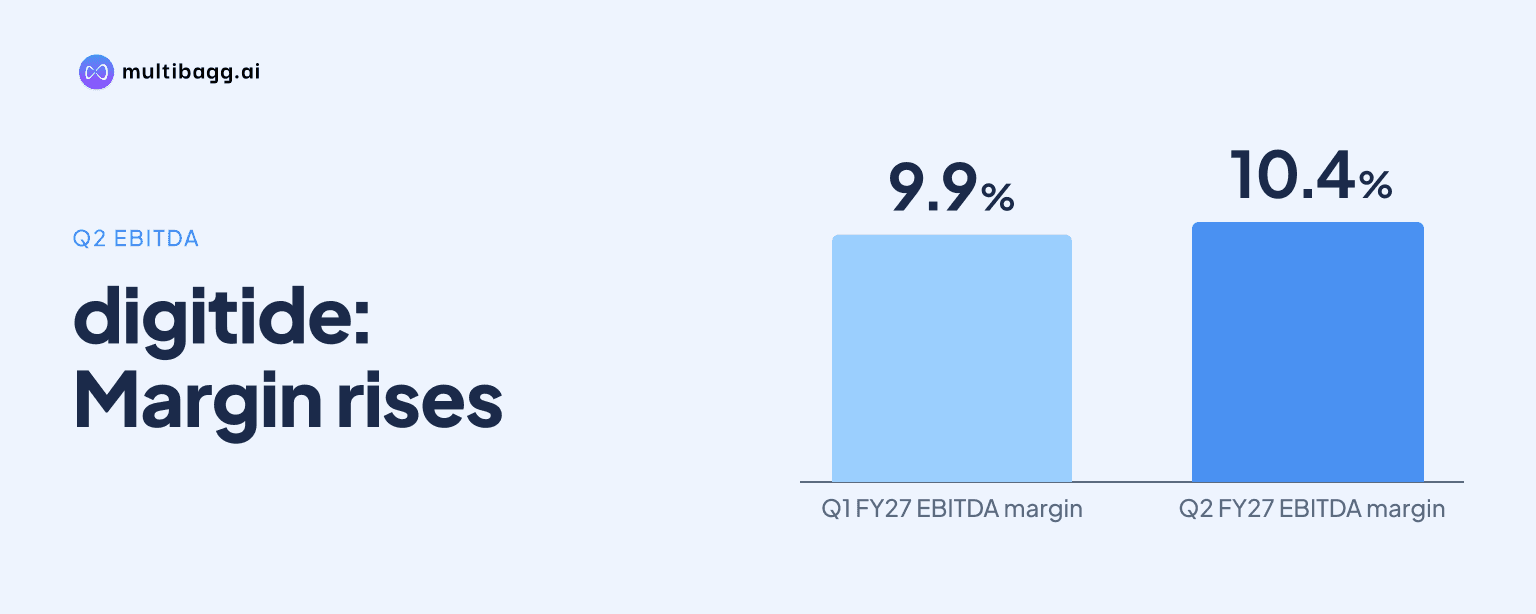
digitide restored its EBITDA margin to 10.4% in Q2 FY27 from 9.9% in Q1 FY27, while reported profit after tax rose 204.0% sequentially to Rs 8.9 crore despite revenue declining 2.0% quarter on quarter to Rs 759.6 crore. The presentation attributes the revenue decline to selective deal-making and renegotiation of low-margin contracts.
Know Digitide Solutions inside out
Results, valuation, peers and who's buying, in one view.
How did digitide’s Q2 FY27 earnings change?
digitide’s Q2 FY27 profitability improved sequentially even though revenue fell, with EBITDA rising 2.5% to Rs 78.8 crore and reported PAT rising 204.0% to Rs 8.9 crore. EBITDA means earnings before interest, tax, depreciation and amortisation, while PAT means profit after tax. The EBITDA margin rose 45 basis points, or bps, from 9.9% in Q1 FY27 to 10.4% in Q2 FY27, while PAT margin increased from 0.4% to 1.2%.
The sequential recovery did not return profitability to the prior-year quarter’s level. Revenue of Rs 759.6 crore was 0.6% lower than Rs 764.2 crore in Q2 FY26, and EBITDA of Rs 78.8 crore was 7.5% lower than Rs 85.2 crore. EBITDA margin was 78 bps below Q2 FY26’s 11.1%, while adjusted PAT of Rs 8.9 crore was 46.4% below Rs 16.7 crore a year earlier, excluding exceptional items such as demerger-related expenses.
Why did digitide’s revenue decline while margin increased?
digitide says Q2 FY27 revenue declined because it followed disciplined deal selection and renegotiated low-margin contracts, reducing revenue by 2.0% from Q1 FY27 and 0.6% from Q2 FY26. Employee benefits expense fell to Rs 569 crore from Rs 583 crore in Q1 FY27, while other expenses declined to Rs 112 crore from Rs 115 crore. Those sequential cost movements accompanied the Rs 1.9 crore increase in EBITDA.
The year-on-year comparison shows why the margin remained below the earlier level. The presentation says the EBITDA decline versus Q2 FY26 reflected wage revisions and provisions for older receivables. Employee benefits expense was Rs 569 crore in Q2 FY27, compared with Rs 555 crore a year earlier, while EBITDA was Rs 6.4 crore lower. Depreciation and amortisation stayed at Rs 55 crore sequentially, finance cost remained Rs 15 crore, and tax expense fell to Rs 5 crore from Rs 8 crore, supporting the increase in PAT.
Which digitide segments drove the changing revenue mix?
digitide’s Tech & Digital segment drove growth within a declining company revenue base, increasing 2.6% quarter on quarter and 6.6% year on year to Rs 243.6 crore in Q2 FY27. Its revenue share increased to 32.1% from 30.6% in Q1 FY27 and 29.9% in Q2 FY26. Segment EBITDA increased to Rs 27.1 crore from Rs 18.9 crore sequentially, and its margin rose 315 bps to 11.1%.
Business process management, or BPM, moved in the opposite direction. BPM revenue fell 4.0% sequentially to Rs 516.1 crore and 3.7% year on year, bringing its share down to 67.9% from 69.4% in Q1 FY27. BPM segment EBITDA declined to Rs 70.2 crore from Rs 76.0 crore, and its margin fell 54 bps sequentially to 13.6%. These segment EBITDA figures exclude unallocated corporate costs, and the presentation says historical margins were restated for like-for-like comparison.
International revenue added another shift in the mix, rising 13.5% year on year to Rs 323 crore and accounting for 42.5% of Q2 FY27 revenue, compared with 38.1% in Q1 FY27. Domestic revenue was Rs 437 crore, or 57.5% of the total. Banking, financial services and insurance represented 51.7% of revenue, while manufacturing, energy and utilities accounted for 16.5%, healthcare for 4.1%, and fast-growth technology for 6.9%.
Got a follow-up? Ask IRIS
What do digitide’s operating indicators show?
digitide reduced its employee count to 49.8 thousand in Q2 FY27 from 53.6 thousand in Q1 FY27 and 56.3 thousand in Q2 FY26. This 3.8-thousand sequential reduction occurred alongside the fall in employee benefits expense from Rs 583 crore to Rs 569 crore. The presentation does not specify the causes of the workforce change, but the reported figures coincide with the quarter’s 45-bps EBITDA-margin increase.
Receivables moved in the other direction. Days sales outstanding, or DSO, including billed and unbilled receivables, increased to 84 days in Q2 FY27 from 82 days in Q1 FY27 and 75 days in Q4 FY26. At 30 September 2026, billed DSO was 53 days and unbilled DSO was 31 days. Trade receivables and unbilled revenue were Rs 695 crore, compared with Rs 659 crore at 31 March 2026.
How did digitide perform in the first half of FY27?
digitide delivered 2.3% revenue growth in H1 FY27, but its first-half margins and profits were below H1 FY26. Revenue rose to Rs 1,534.7 crore from Rs 1,500.0 crore, while EBITDA fell 7.2% to Rs 155.7 crore. EBITDA margin declined 104 bps to 10.1%, showing that the Q2 sequential recovery did not offset the lower Q1 FY27 margin for the half year.
Reported PAT for H1 FY27 was Rs 11.9 crore, down 4.8% from Rs 12.5 crore, while adjusted PAT declined 66.3% to Rs 11.9 crore from Rs 35.3 crore. Total equity was Rs 923 crore at 30 September 2026, compared with Rs 916 crore at 31 March 2026. The presentation reported net cash of Rs 76 crore and debt to equity of 0.08:1 at the September date.
Conclusion
digitide’s Q2 FY27 result shows a sequential improvement in reported profitability: EBITDA margin recovered to 10.4%, PAT reached Rs 8.9 crore, and Tech & Digital delivered higher revenue and segment margin. However, total revenue declined to Rs 759.6 crore, BPM revenue and margin fell, and both company EBITDA margin and adjusted PAT remained below Q2 FY26 levels.
The next indicators to watch are whether the stated selective deal approach and low-margin contract renegotiations allow revenue to stabilise after the 2.0% sequential decline, and whether Tech & Digital can maintain its 32.1% revenue share. Receivable collection is also unresolved in the disclosed data, as DSO reached 84 days at 30 September 2026 despite Rs 51 crore of net operating cash flow for the first half.