










DOMS Industries Limited says flooding cut Q2 sales 350 bps
Key highlights
- DOMS reported Q2'FY27 revenue growth of 17.6% to ₹667.8 crore.
- Flooding reduced Q2'FY27 sales growth by an estimated 300–350 basis points.
- A ₹10.4 crore exceptional expense for flood damage contributed to PAT falling 37.0% to ₹38.3 crore.
- DOMS retained FY27 consolidated sales-growth guidance of 18–20%.
powered by IRIS
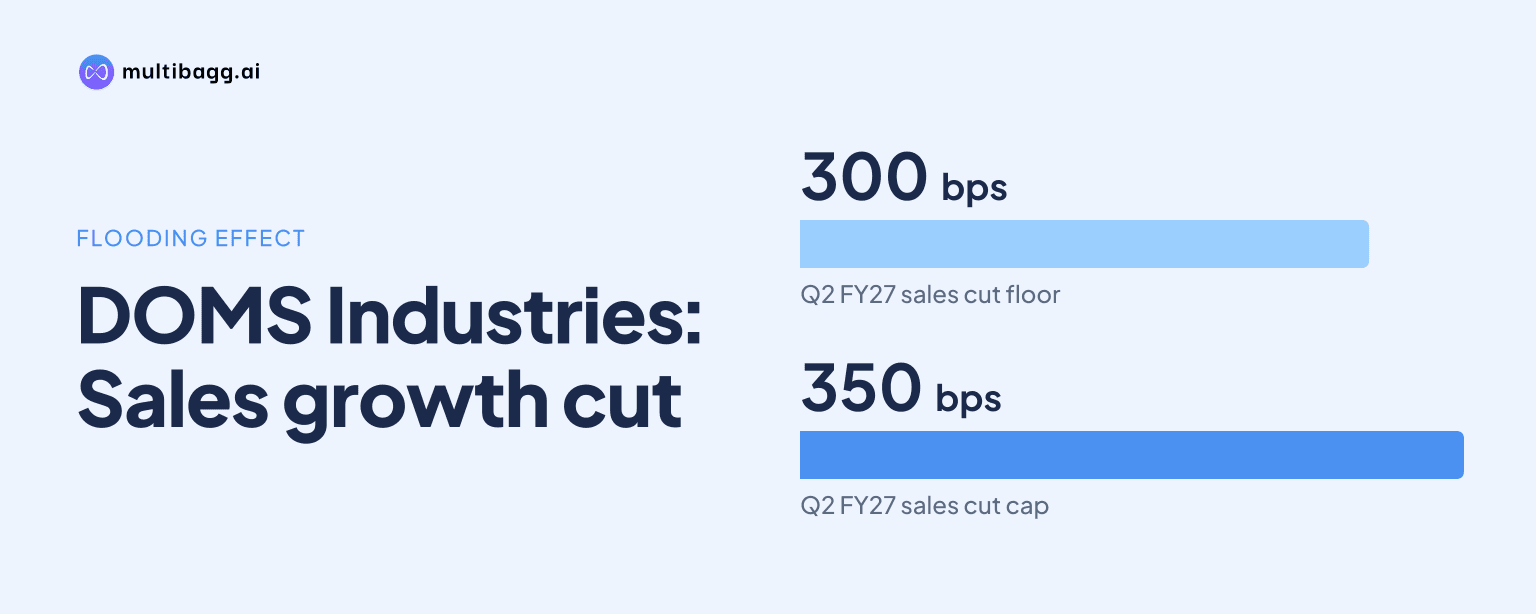
In the second quarter of financial year 2027 (Q2'FY27), DOMS Industries Limited said flooding cut sales growth by an estimated 300–350 basis points. The inventory damage also resulted in a ₹10.4 crore exceptional expense, while consolidated revenue rose 17.6% year on year to ₹667.8 crore and profit after tax fell 37.0% to ₹38.3 crore.
Know Doms Industries inside out
Results, valuation, peers and who's buying, in one view.
How did flooding affect DOMS sales growth in Q2'FY27?
Flooding reduced DOMS's Q2'FY27 sales growth by an estimated 300–350 basis points, or 3.0–3.5 percentage points. The company said exceptionally heavy rainfall and flooding caused inventory damage, disrupting sales in a quarter when revenue from operations nevertheless increased 17.6% to ₹667.8 crore from ₹567.9 crore in Q2'FY26.
DOMS attributed the reported revenue increase to volume growth in domestic and export markets, year-on-year capacity additions, new product launches and marginally higher average selling prices (ASPs) from calibrated pricing actions. The company did not disclose a flood-adjusted revenue amount or a growth rate excluding the estimated 300–350 basis-point effect.
Q2'FY27 revenue was ₹2.7 crore below the ₹670.5 crore reported in Q1'FY27, despite its year-on-year increase. For the first half of FY27 (H1'FY27), revenue grew 18.4% to ₹1,338.3 crore from ₹1,130.2 crore in H1'FY26, which DOMS said was in line with its yearly guided range.
What was DOMS's direct financial loss from flooding?
DOMS recorded a one-time exceptional expense of ₹10.4 crore in Q2'FY27 for damage caused by heavy rainfall and flooding. The company said the charge primarily affected profit after tax (PAT), which declined to ₹38.3 crore from ₹60.9 crore in Q2'FY26, a 37.0% reduction.
Profit before tax (PBT) before exceptional expense was ₹61.3 crore in Q2'FY27, compared with reported PBT of ₹51.0 crore after the charge. The ₹10.3 crore difference reflects rounding in the release, which identifies the underlying flood-related exceptional expense as ₹10.4 crore.
DOMS said it had lodged relevant insurance claims and expected the related recovery to substantially offset the profit-and-loss impact in due course. The November 2, 2026 release did not disclose the value of the claims, the expected recovery amount, an insurer decision date or the accounting period in which any recovery could be recognised.
Got a follow-up? Ask IRIS
How did operating profitability compare with earlier periods?
DOMS's earnings before interest, tax, depreciation and amortisation (EBITDA) fell 16.8% year on year to ₹82.8 crore in Q2'FY27 from ₹99.5 crore, while EBITDA margin declined to 12.4% from 17.5%. The flooding-related exceptional expense was below EBITDA, but the company also reported a lower operating margin than in the prior-year quarter.
The company said consumption margins improved sequentially as raw-material prices were softer in the early part of Q2'FY27, before input costs rose sharply in the latter half. It also cited higher employee expenses arising from temporary under-absorption of fixed overheads by the Reynolds team, linked to a transitory impact in the commencement of production.
Sequentially, Q2'FY27 EBITDA margin improved slightly to 12.4% from 12.3% in Q1'FY27. EBITDA was nearly unchanged at ₹82.8 crore versus ₹82.6 crore in Q1'FY27, but PAT declined from ₹45.3 crore to ₹38.3 crore as the quarter included the ₹10.4 crore exceptional expense.
For H1'FY27, EBITDA decreased 16.6% to ₹165.3 crore from ₹198.3 crore in H1'FY26, and EBITDA margin was 12.4% compared with 17.5%. H1'FY27 PAT declined 30.3% to ₹83.6 crore from ₹120.0 crore, while PAT margin fell to 6.2% from 10.6%, including the second-quarter weather-related loss.
What is DOMS's plan after the weather disruption?
DOMS management retained its consolidated sales-growth guidance of 18–20% for FY27, despite the estimated 300–350 basis-point sales-growth loss in Q2'FY27. Management cited positive demand across key categories and markets, while saying Q2 growth was broad-based across Scholastic Stationery, Scholastic Art Material, Office Supplies, Hobby & Craft and Back-to-School.
The company said the first building at its new 50-acre manufacturing facility had been commissioned. Dedicated to export pen production, the building is expected by management to begin contributing to revenue from Q3'FY27 onwards as part of DOMS's capacity-expansion roadmap.
DOMS sells products across eight core Stationery and Art categories, including Paper Stationery, Kits and Combos and Fine Art Products. Its distribution network covers 28 states and eight Union Territories in India, as well as more than 55 countries, and the company said both domestic and export volumes supported Q2'FY27 revenue growth.
Conclusion
The Q2'FY27 results identify two separate effects from flooding: an estimated 300–350 basis-point reduction in sales growth and a ₹10.4 crore exceptional expense for damaged inventory. Revenue still increased 17.6% to ₹667.8 crore, but PAT fell 37.0% to ₹38.3 crore as the exceptional charge accompanied lower year-on-year operating profitability.
The next disclosed markers are the expected Q3'FY27 revenue contribution from the export-pen building at the 50-acre facility and progress on insurance claims intended to substantially offset the flooding-related profit-and-loss impact. Management has retained FY27 consolidated sales-growth guidance of 18–20%, while the release gives no recovery amount or settlement timeline for the insurance claims.