










Dr. Agarwal's sees premium cataract mix stabilising at 30%-35%
Key highlights
- Dr. Agarwal's expects high-end cataract procedures to stabilise at 30%-35% of volume, rather than reach 50%-60%.
- Dr. Agarwal's high-end procedure mix rose from around 18% in FY24 to close to 30% by November 2026.
- Lenticular procedures grew close to 41% and Femto cataract procedures grew close to 26%.
- Dr. Agarwal's raised its annual facility target to 65 centres and capital expenditure guidance to Rs 500 crore.
powered by IRIS
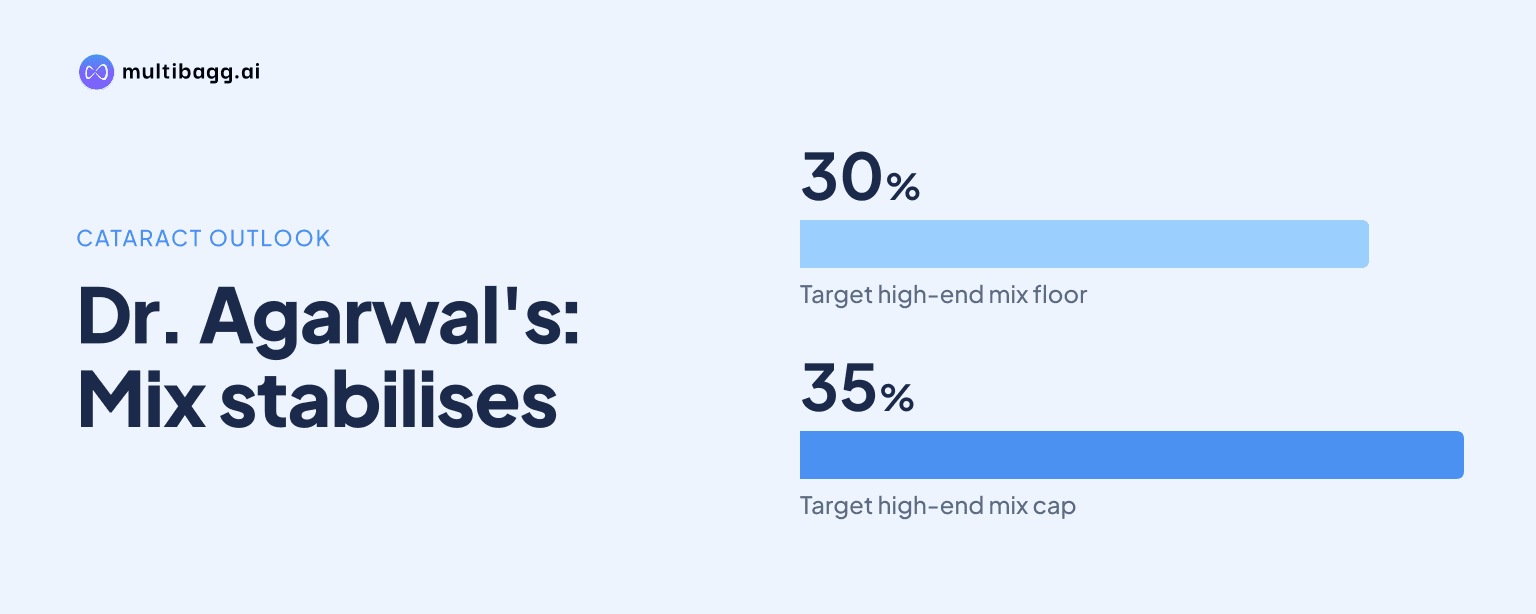
Dr. Agarwal's Health Care Limited said on November 5, 2026, that high-end cataract procedures should stabilise at 30%-35% of cataract volumes over the next few years, rather than rise to 50%-60%, after the mix increased from around 18% in FY24 to close to 30%.
Know Dr Agarwals Health Care inside out
Results, valuation, peers and who's buying, in one view.
What premium cataract mix does Dr. Agarwal's expect?
Dr. Agarwal's expects its high-end cataract procedure mix to settle in the 30%-35% range for at least the next few years. Management said high-end cataract procedures already account for about 30% of total cataract volumes, and that the proportion has effectively stayed at that level. It does not expect the mix to advance materially to 50% or 60% because a long tail of patients may find certain advanced procedures expensive.
The stated range is a ceiling for the network-wide case mix, not a forecast that demand for advanced procedures will stop growing. Management said additional machines and network expansion could still shift more individual locations towards roughly 30% high-end procedure penetration. The distinction matters because a location with a lower current mix can move towards the group's target range without raising the overall mix far beyond 35%.
Management described 30%-35% as the range where it sees the appropriate balance between advanced-procedure uptake and affordability constraints for patients. That assessment was made during the November 5, 2026 earnings call and is management's outlook rather than a formal financial target. It applies specifically to the high-end share of cataract volumes, rather than to all eye-care procedures or revenue.
How much has Dr. Agarwal's high-end procedure mix changed?
Dr. Agarwal's said the high-end procedure share rose from around 18% in FY24 to close to 30% by the November 2026 call. This is a rise of about 12 percentage points over the period, showing that the company has already captured a substantial part of the mix shift it expects. Management linked the increase partly to the introduction of Femto cataract procedures and a gradually increasing market requirement for higher-end treatment.
The newer mix profile has been accompanied by faster growth in selected advanced procedures. Management said lenticular procedures grew by close to 41%, while Femto cataract procedures grew by close to 26%. Lenticular procedures are refractive surgeries that management said are gaining acceptance as patients move away from older traditional LASIK procedures towards SMILE procedures.
Dr. Agarwal's has added lenticular machines in Naranpura, Cochin and Coimbatore to support that shift in refractive demand. Management said last year's refractive surgery growth had slowed, but volumes have increased as lenticular offerings expanded and patients observed better results. Those refractive trends support procedure yield, but they do not change management's separate 30%-35% expectation for high-end cataract volumes.
Got a follow-up? Ask IRIS
How is premiumisation affecting Dr. Agarwal's growth?
Dr. Agarwal's said premiumisation contributed close to 8 percentage points of its 17.7% same-store sales growth, or SSSG, while price contributed about 1.5 percentage points. Management estimated that outpatient department, or OPD, growth added about 7.5 percentage points and conversion added another 0.5 percentage points, taking volume-related growth to roughly 8%. The remaining approximately 9.5 percentage points came from value growth, primarily premiumisation.
This breakdown indicates that the recent growth mix included both greater patient throughput and higher-value procedures. However, management's 30%-35% mix outlook means premiumisation is not expected to remain an unlimited source of case-mix expansion once more centres reach that range. Further revenue growth would still depend on patient volumes, conversions, new-centre additions, local adoption of advanced procedures and any price changes.
Management attributed increasing high-end procedure demand to rising disposable income, broader insurance penetration and higher coverage for procedures. It said patients' ability to pay for higher-end procedures increases as insurance premiums and coverage rise. These are management's demand observations, not quantified forecasts for procedure volumes, reimbursement or pricing.
What expansion plan could support advanced procedure adoption?
Dr. Agarwal's raised its annual facility-addition plan to 65 centres from 60 and increased its surgical-centre target to 55 from 40. Management said it had launched 39 centres in the first half and planned about 26 more in the second half, including 10 primary centres within the 55 surgical-centre guidance. It also revised annual capital expenditure guidance to Rs 500 crore from approximately Rs 400 crore.
The emphasis on surgical facilities is relevant because management said such centres generate average monthly revenue of Rs 75 lakh to Rs 80 lakh. It said the company is seeing quicker ramp-ups and breakeven at many centres in core markets, supporting additional rollouts in existing regions and newer markets. New facilities can create more access points for Femto cataract and lenticular procedures where the relevant equipment is installed.
In Delhi National Capital Region, Dr. Agarwal's said it had added about 15 centres over the prior 15 months and planned another eight to 12 centres over the next nine to 12 months. Management said this expansion, alongside deeper presence in Chennai, Bangalore and Hyderabad, has increased confidence in the revised guidance. It also said the growth engine remains predominantly Greenfield expansion, while bolt-on acquisitions will be considered only when they fit strategy and valuation requirements.
Conclusion
Dr. Agarwal's has identified a more defined endpoint for premium cataract penetration: management expects high-end procedures to stabilise at 30%-35% of cataract volumes after the share rose from around 18% in FY24 to close to 30%. Advanced procedures remain important to current performance, with close to 41% lenticular growth, close to 26% Femto cataract growth and premiumisation contributing close to 8 percentage points of 17.7% SSSG.
The next point to watch is execution of the expanded annual plan of 65 facilities, including 55 surgical centres, backed by Rs 500 crore of planned capital expenditure. Management's key operational test is whether newer centres and newly equipped locations can move towards the roughly 30% high-end procedure range while delivering the ramp-up and breakeven trends it cited in core and newer markets.