










Euro Pratik Q2 revenue rises 20% but EBITDA margin falls
Key highlights
- Euro Pratik Q2FY27 revenue from operations rose 19.8% year on year to Rs 115.7 crore.
- Euro Pratik Q2FY27 consolidated EBITDA margin was 31.4%, versus 32.5% in Q2FY26.
- Euro Pratik H1FY27 PAT rose 43.9% to Rs 46.2 crore, while EBITDA margin declined to 29.6% from 33.8%.
- Euro Pratik’s wall-panel revenue share declined to 57.3% in FY26 from 66.1% in FY25.
powered by IRIS
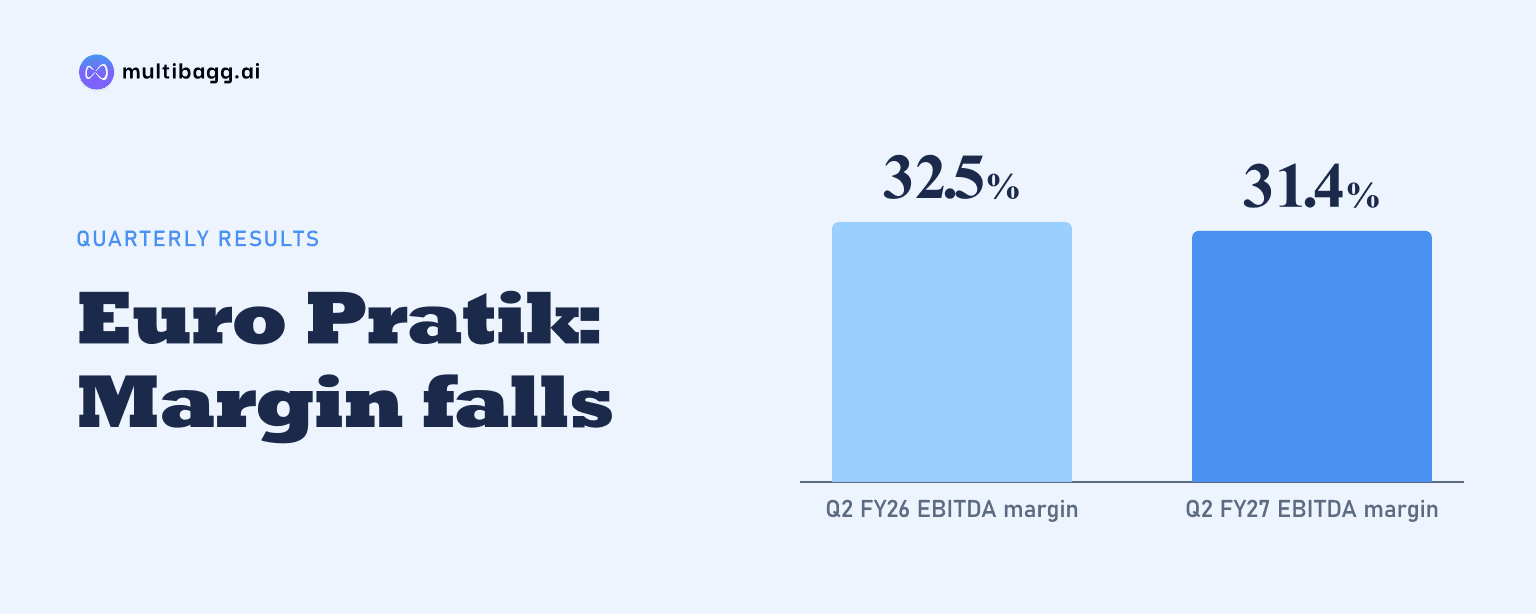
Euro Pratik Sales Ltd reported Q2FY27 revenue from operations of Rs 115.7 crore, up 19.8% year on year, but consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin declined to 31.4% from 32.5%. Euro Pratik’s profit after tax (PAT) increased 14.9% to Rs 26.2 crore as EBITDA rose 18.0%, slower than total revenue’s 22.2% increase.
Know Euro Pratik Sales inside out
Results, valuation, peers and who's buying, in one view.
Why did Euro Pratik’s Q2FY27 profit grow more slowly than revenue?
Euro Pratik’s Q2FY27 PAT grew more slowly than revenue because gross profit and EBITDA each increased 18.0%, below the 22.2% increase in total revenue. Revenue from operations rose by Rs 19.1 crore from Rs 96.6 crore in Q2FY26, while other income increased to Rs 3.3 crore from Rs 0.8 crore, taking total revenue to Rs 119.0 crore.
Cost of goods sold (COGS) increased to Rs 64.6 crore from Rs 53.3 crore, employee expenses rose to Rs 6.2 crore from Rs 3.8 crore, and other expenses reached Rs 10.8 crore from Rs 8.6 crore. Gross-profit margin, calculated on revenue from operations, was 44.2% against 44.8% a year earlier. EBITDA margin declined 110 basis points, or 1.1 percentage points, to 31.4%, while PAT margin fell to 22.0% from 23.4%.
Euro Pratik’s Q2FY27 earnings improved sequentially from Q1FY27, when EBITDA was Rs 29.1 crore and PAT was Rs 20.0 crore. Q2FY27 EBITDA rose 28.5% quarter on quarter and PAT rose 31.0%, while EBITDA margin increased from 27.5% and PAT margin from 18.9%. The sequential increase did not reverse the year-on-year margin decline in the consolidated results.
How did Euro Pratik’s H1FY27 performance compare with H1FY26?
Euro Pratik reported higher H1FY27 revenue and PAT, but gross-profit, EBITDA and earnings before interest and tax (EBIT) margins were below H1FY26 levels. Revenue from operations increased 35.9% to Rs 219.0 crore from Rs 161.1 crore, while total revenue rose 37.7% to Rs 224.8 crore, including Rs 5.8 crore of other income.
Euro Pratik’s H1FY27 gross-profit margin was 41.7%, down from 46.5%, and EBITDA margin was 29.6%, down from 33.8%. COGS rose to Rs 127.6 crore from Rs 86.2 crore, employee expenses increased to Rs 11.8 crore from Rs 7.1 crore, and other expenses rose to Rs 18.9 crore from Rs 14.8 crore. EBIT margin declined to 28.1% from 32.0%.
Euro Pratik’s H1FY27 PAT margin nevertheless increased to 20.6% from 19.7%, while PAT rose to Rs 46.2 crore from Rs 32.1 crore. The two half years included different exceptional-items amounts: H1FY26 recorded Rs 7.9 crore, while H1FY27 recorded none. Profit before tax was Rs 60.9 crore in H1FY27 compared with Rs 43.2 crore in H1FY26.
Got a follow-up? Ask IRIS
What changed in Euro Pratik’s product mix and balance sheet?
Euro Pratik’s FY26 revenue mix had a lower wall-panel share and higher laminates and other-product shares than FY25. Wall panels accounted for 57.3% of FY26 revenue, down from 66.1% in FY25; laminates represented 31.4%, up from 25.6%; and others represented 11.3%, up from 8.3%. The presentation defines others as interior fittings, adhesives and other miscellaneous products.
Euro Pratik’s revenue from operations rose to Rs 335.0 crore in FY26 from Rs 284.2 crore in FY25, and EBITDA increased to Rs 121.2 crore from Rs 107.8 crore. EBITDA margin, however, declined to 35.3% from 36.9%. FY26 PAT was Rs 77.2 crore compared with Rs 75.7 crore, and PAT margin declined to 22.5% from 25.9%.
Euro Pratik’s total assets were Rs 449.1 crore at September 2026, compared with Rs 396.7 crore at March 2026. Inventories increased to Rs 143.9 crore from Rs 122.4 crore, and trade receivables rose to Rs 105.8 crore from Rs 97.6 crore. Cash and cash equivalents declined to Rs 8.4 crore from Rs 16.4 crore over the same period.
Euro Pratik’s total equity increased to Rs 371.6 crore at September 2026 from Rs 320.6 crore at March 2026, while total liabilities were Rs 77.5 crore compared with Rs 76.1 crore. Non-current borrowings increased to Rs 9.8 crore from Rs 3.1 crore, while current borrowings declined to Rs 3.7 crore from Rs 8.5 crore. Total current assets rose to Rs 324.4 crore from Rs 300.9 crore.
How do Euro Pratik’s core-business margins compare with consolidated margins?
Euro Pratik’s separately calculated core-business margins improved sequentially in Q2FY27, but they cover a different scope from the consolidated income statement. The core-business ratios include Euro Pratik Sales Ltd and wholly owned subsidiary Glorio Decor Private Ltd, whereas the consolidated Q2FY27 EBITDA margin was 31.4%.
Euro Pratik’s core-business gross-profit margin was 45.6% in Q2FY27, compared with 43.7% in Q1FY27. Core-business EBITDA margin increased to 36.7% from 35.2%, while net-profit margin rose to 27.0% from 25.9%. For H1FY27, the respective core-business margins were 44.8%, 36.0% and 26.5%.
Euro Pratik’s consolidated Q2FY27 gross-profit margin of 44.2% was 0.6 percentage points below Q2FY26, while EBITDA margin was 31.4% versus 32.5%. The presentation states that EBITDA includes other income because foreign-exchange gains are operational in nature. Other income was Rs 3.3 crore in Q2FY27, compared with Rs 0.8 crore in Q2FY26.
Euro Pratik’s consolidated Q2FY27 EBIT was Rs 35.7 crore, up from Rs 30.2 crore in Q2FY26, but EBIT margin declined to 30.0% from 31.0%. Finance cost increased to Rs 1.0 crore from Rs 0.6 crore, while tax rose to Rs 8.5 crore from Rs 6.8 crore. These line items preceded the 14.9% increase in quarterly PAT.
Conclusion
Euro Pratik’s Q2FY27 results combined 19.8% growth in revenue from operations to Rs 115.7 crore with slower 18.0% EBITDA growth and a 110-basis-point decline in consolidated EBITDA margin. The H1FY27 result showed the same operating pattern: total revenue rose 37.7% to Rs 224.8 crore, while EBITDA increased 20.7% to Rs 66.5 crore and its margin declined 4.2 percentage points.
The next developments to watch are Euro Pratik’s stated expansion into the USA and Croatia and further changes in its product mix, after wall panels’ FY26 revenue share fell to 57.3%. The presentation also cites Technopak estimates that the Indian wall-panel market could reach Rs 5,507 crore by FY29E and that the organised market could account for 75% by FY2029; these are market estimates, not Euro Pratik targets.