










GEE Limited targets 25-30% revenue CAGR and 91% utilisation by FY29
Key highlights
- GEE targets 25-30% revenue CAGR through FY29 and an EBITDA margin above 13%.
- GEE targets about 91% capacity utilisation by FY29, compared with 57% in FY26.
- GEE targets 71,339 MTPA of installed capacity by FY27, versus approximately 59,075 MTPA in its utilisation disclosure.
- H1FY27 revenue rose 24.0% year on year to Rs 204.20 crore, while EBITDA margin was 7.8%.
powered by IRIS
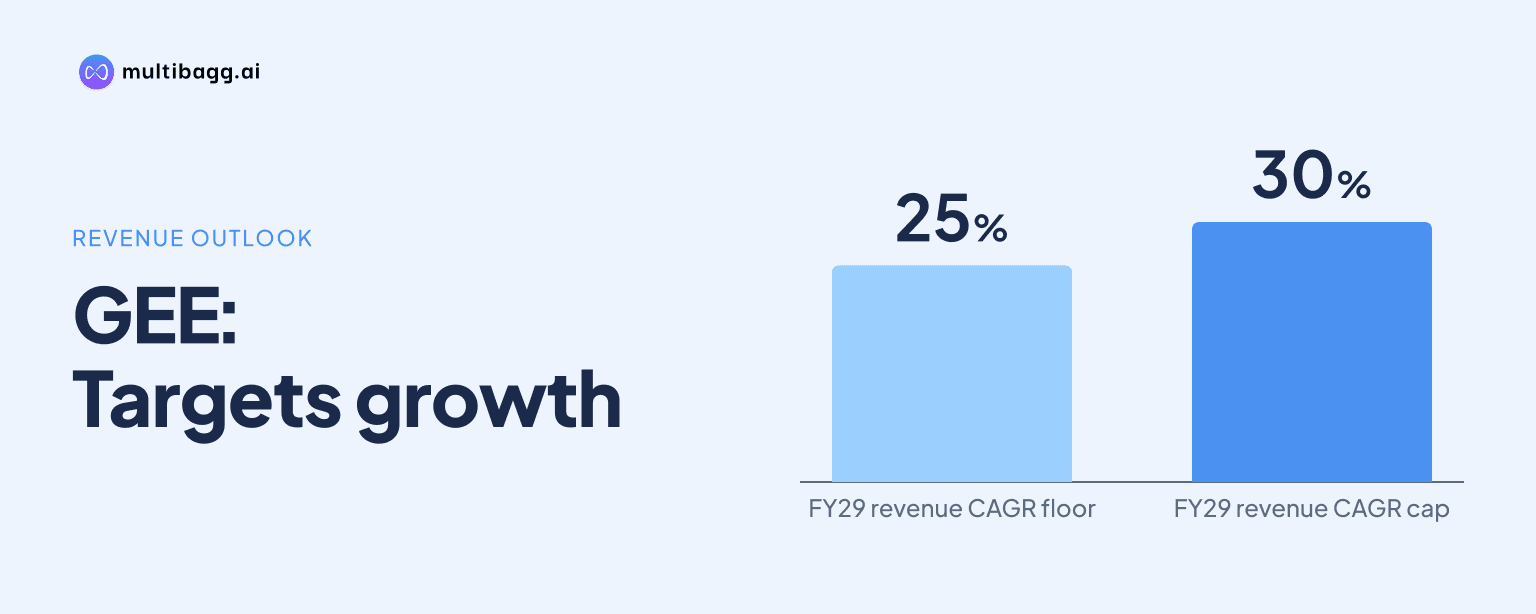
GEE Limited targets revenue compound annual growth of 25-30% through FY29 and capacity utilisation of about 91%, compared with 57% in FY26, while targeting 71,339 metric tonnes per annum of installed capacity by FY27. Management also sets an earnings before interest, tax, depreciation and amortisation margin target above 13%.
Know GEE inside out
Results, valuation, peers and who's buying, in one view.
What are GEE's FY29 growth and margin targets?
GEE targets revenue compound annual growth rate, or CAGR, of 25-30% through FY29, EBITDA margin above 13%, and capacity utilisation of about 91% by FY29. Management presents these as targets alongside priorities including strengthening the core business, improving product mix, expanding specialised offerings, working-capital discipline, cash generation and capital efficiency.
The revenue-growth objective exceeds the 6-6.4% CAGR cited in the presentation for the Indian welding consumables market between 2024 and 2033-35. GEE therefore plans to grow faster than that market estimate through specialised products, manufacturing efficiency, domestic distribution and export expansion.
GEE reported revenue from operations of Rs 204.20 crore in H1FY27, up 24.0% from Rs 164.63 crore in H1FY26. EBITDA rose 17.6% to Rs 15.91 crore, but the EBITDA margin declined to 7.8% from 8.2%, placing the reported half-year margin 5.2 percentage points below management's 13%+ target.
How much must GEE raise capacity utilisation?
GEE must raise utilisation by about 34 percentage points from 57% in FY26 to about 91% in FY29. The presentation measures utilisation as a share of approximately 59,075 metric tonnes per annum, or MTPA, of installed capacity across its Kalyan and Kolkata facilities.
The FY26 result was higher than 48% in FY25, marking a recovery after utilisation fell from 53% in FY23 to 50% in FY24 and then 48% in FY25. The FY29 target requires a substantially larger increase in plant loading than the nine-percentage-point improvement recorded between FY25 and FY26.
GEE operates two manufacturing sites, with the Kalyan plant carrying about 21,000 MT of capacity and the Kolkata plant about 38,000 MT. The presentation does not disclose the production volumes behind the annual utilisation percentages, but identifies manufacturing efficiency and utilisation as one of five growth opportunities.
What capacity expansion does GEE target by FY27?
GEE targets installed capacity of 71,339 MTPA by FY27, compared with approximately 59,075 MTPA in its utilisation disclosure. This represents a planned increase of 12,264 MTPA, or about 21%, before the FY29 utilisation target of roughly 91% is due.
The capacity target raises the scale of the operating plan because GEE seeks higher utilisation after expanding the installed base. Management does not provide a plant-by-plant expansion schedule, capital expenditure amount, production forecast or funding plan for the FY27 capacity target in the presentation.
At H1FY27, fixed assets stood at Rs 62.78 crore, compared with Rs 57.84 crore at FY26, while capital work in progress was Rs 2.30 crore, up from Rs 1.61 crore. These balance-sheet items provide a reporting-date snapshot, but do not identify expenditure specifically related to the 71,339 MTPA target.
Got a follow-up? Ask IRIS
Which growth drivers does GEE identify?
GEE identifies specialised welding products, defence and shipbuilding, energy and infrastructure projects, manufacturing efficiency, and domestic and export expansion as its five growth drivers. Its welding consumables portfolio includes electrodes, wires and fluxes for shielded metal arc welding, submerged arc welding, metal inert gas or metal active gas welding, tungsten inert gas welding, flux-cored wire, brazing wire and flux applications.
The specialised-products programme names flux-cored wires following Bureau of Indian Standards requirements, together with stainless-steel electrodes and wires. GEE also identifies low-heat-input, creep-resistant and stainless variants supported by proprietary flux formulations, linking product mix with its stated operating-margin objective.
Defence and shipbuilding opportunities include Defence Research and Development Organisation and naval approvals, according to the presentation. GEE cites an USD 8.0 billion shipbuilding market by 2033 and serves infrastructure, defence, energy, oil and gas, railways and shipbuilding applications.
GEE has more than 500 dealers in India and exports to more than 20 countries, with Africa, the Middle East and Southeast Asia identified as focus regions. Its business has an approximately 50:50 business-to-business and business-to-consumer revenue mix, more than 500 products and more than 50 research and development professionals.
What do GEE's latest results show about the starting point?
GEE's H1FY27 revenue growth was 24.0%, while EBITDA margin fell 0.4 percentage points year on year to 7.8%. The combination shows reported revenue expansion, while management's financial outlook specifically addresses product mix, operating margins, working capital and manufacturing efficiency.
In Q2FY27, revenue from operations was Rs 101.34 crore, compared with Rs 85.45 crore in Q2FY26 and Rs 102.86 crore in Q1FY27. Q2FY27 EBITDA was Rs 7.91 crore, below Rs 8.94 crore a year earlier, while the margin was 7.8% versus 10.5% in Q2FY26.
Reported profit after tax was Rs 10.78 crore in H1FY27, compared with Rs 5.18 crore in H1FY26, although H1FY27 included Rs 3.70 crore of exceptional items recorded in Q1FY27. Adjusted profit after tax was Rs 7.09 crore, up 36.7% from Rs 5.18 crore, and adjusted profit margin increased to 3.5% from 3.1%.
Total borrowings were Rs 81.04 crore at H1FY27, comprising Rs 24.47 crore of borrowings and Rs 56.57 crore of short-term borrowings. Trade receivables rose to Rs 65.49 crore from Rs 55.04 crore at FY26, while inventories declined to Rs 87.24 crore from Rs 89.72 crore, providing context for management's working-capital focus.
Conclusion
GEE's plan combines 25-30% revenue CAGR through FY29, EBITDA margin above 13%, capacity expansion to 71,339 MTPA by FY27 and utilisation of about 91% by FY29. The reported starting point includes 57% utilisation in FY26, Rs 204.20 crore of H1FY27 revenue and a 7.8% EBITDA margin.
The disclosed milestones to watch are progress toward the FY27 capacity target and whether subsequent results move utilisation from 57% toward 91% by FY29. Management's 13%+ EBITDA-margin target also makes product mix, specialised-product sales, manufacturing efficiency and working-capital execution relevant measures in future reporting.