










GPT Infraprojects Limited targets Rs 150 crore Alcon revenue
Key highlights
- Alcon’s order book reached a record Rs 480 crore after about Rs 428 crore of new signalling contracts.
- Management expects Alcon to generate about Rs 150 crore of revenue and about Rs 30 crore of EBITDA in FY27.
- Alcon reported about Rs 36 crore of revenue in H1 FY27 and is expected to maintain EBITDA margin close to 20%.
- GPT’s consolidated EBITDA margin rose to 15% in H1 FY27 from 12.9% in H1 FY26.
powered by IRIS
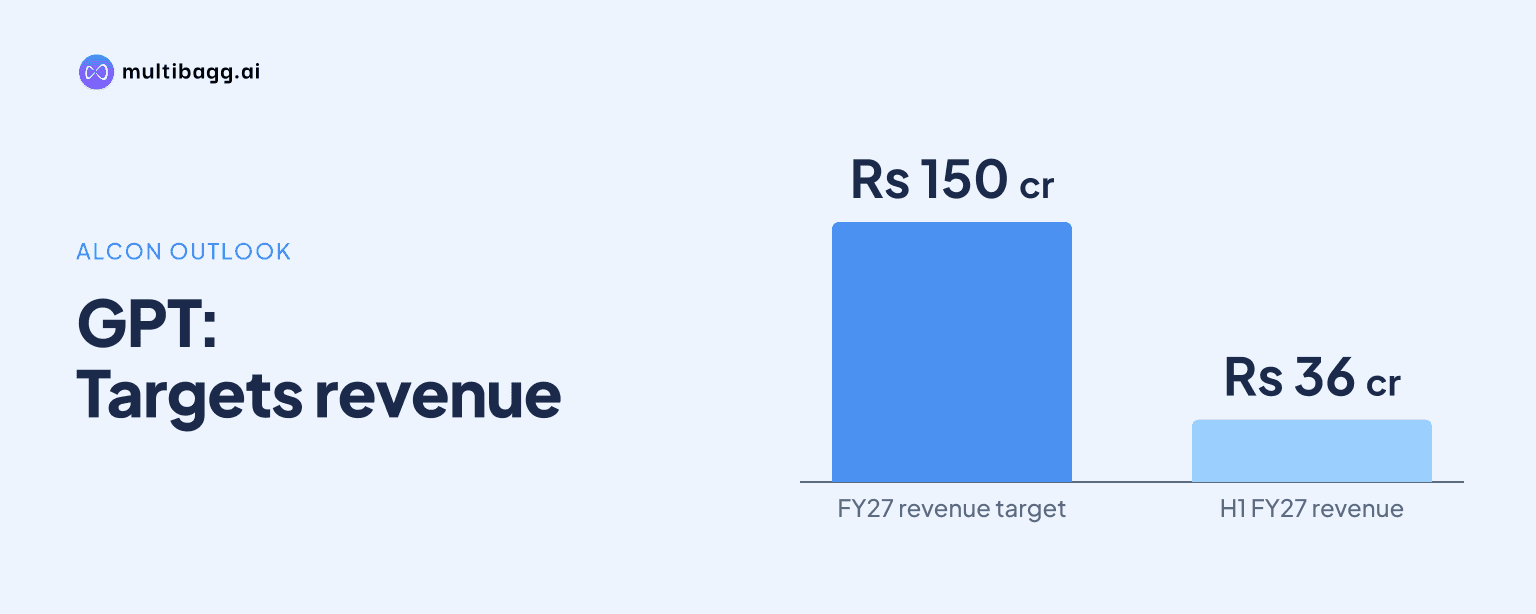
GPT Infraprojects Limited expects acquired railway-signalling subsidiary Alcon to generate about Rs 150 crore of revenue and about Rs 30 crore of EBITDA in FY27, supported by a record Rs 480 crore outstanding order book after Rs 428 crore of signalling contract wins. Management expects Alcon revenue to reach Rs 200 crore or more next year.
Know GPT Infraprojects inside out
Results, valuation, peers and who's buying, in one view.
What is Alcon’s FY27 revenue and EBITDA target?
Alcon is targeted to generate about Rs 150 crore of revenue and about Rs 30 crore of earnings before interest, tax, depreciation and amortisation, or EBITDA, in FY27. Management said this would represent an EBITDA margin close to 20%, and it expects that margin level to continue going forward.
GPT acquired Alcon Builders & Engineers in February 2026, adding signalling capabilities to its railway-infrastructure operations. Alcon generated about Rs 36 crore of revenue in H1 FY27, so management’s Rs 150 crore full-year expectation implies a substantially larger revenue contribution during H2 FY27 than in the first six months.
The FY27 revenue expectation is above the Rs 120 crore to Rs 130 crore outlook referred to by an analyst during the November 5, 2026 earnings call. Management attributed the higher expectation to recent order wins and said next-year revenue could be close to Rs 200 crore or more.
Management did not disclose Alcon’s absolute H1 FY27 EBITDA, but said its margin was close to 20%. The revenue and EBITDA expectations are management targets based on the order wins rather than reported full-year results.
Which contracts support Alcon’s revenue plan?
Alcon’s outstanding order book was about Rs 480 crore at the date of the call, its highest-ever level, following multiple signalling orders worth about Rs 428 crore. This backlog is the principal disclosed basis for the FY27 revenue target and the next-year revenue expectation.
The largest named contract is worth Rs 134 crore from Western Railway’s Ratlam Division. It covers survey, design, supply, installation, testing and commissioning of four-aspect automatic block signalling, electronic interlocking and associated works on various Ratlam Division sections.
A second order, worth Rs 114.82 crore from Northeast Frontier Railway’s Katihar Division, covers electronic interlocking at 10 stations on the HDN-HUN route. A third contract worth Rs 85.53 crore from Eastern Railway’s Asansol Division covers automatic signalling using multi-section digital axle counter electronic interlocking at New Mugma and Mugma Yard, across about 25 kilometres of the dedicated freight corridor section.
The three named contracts total Rs 334.35 crore, leaving about Rs 93.65 crore of the Rs 428 crore aggregate in other signalling contracts not detailed in the call. Management did not provide project-by-project execution dates, billing milestones or revenue-recognition schedules for the Alcon orders.
Got a follow-up? Ask IRIS
How does Alcon affect GPT’s earnings mix?
Alcon is expected to add a signalling business with EBITDA margin close to 20% to GPT’s existing Infrastructure and Concrete Sleeper operations. Management said the addition of signalling and a pickup in African operations support its expectation for a 14% to 15% consolidated EBITDA margin.
GPT’s consolidated EBITDA in H1 FY27 rose 16.1% year on year to Rs 89 crore from Rs 77 crore, while the EBITDA margin increased to 15% from 12.9%. Consolidated revenue was Rs 594 crore in H1 FY27 versus Rs 591 crore in H1 FY26, showing that profit growth exceeded revenue growth during the period.
Infrastructure remained the larger operating segment in Q2 FY27, reporting revenue of Rs 262 crore and earnings before interest and tax, or EBIT, of Rs 33 crore. The Concrete Sleeper segment reported Rs 30 crore of revenue and Rs 2.5 crore of EBIT, while its order book stood at Rs 852 crore.
The acquisition also resulted in an additional Rs 8 crore goodwill-amortisation charge in H1 FY27, which management described as non-cash. GPT reported consolidated profit after tax of Rs 43 crore in H1 FY27, with a 7.2% margin, and management said profitability would have been higher without the amortisation charge.
What is GPT’s wider railway and execution plan?
GPT plans to use Alcon to expand its role in railway signalling and said Alcon can bid for contracts above Rs 200 crore in its own name. Management said this bidding capacity could increase after the proposed merger because the combined entity’s net worth would rise, although it did not give a merger timetable or a revised threshold.
The group’s total outstanding order book was about Rs 5,373 crore at the call date, equivalent to 4.3 times FY26 revenue, according to management. This includes an Infrastructure order book of Rs 4,521 crore and a Concrete Sleeper order book of Rs 852 crore, alongside Alcon’s Rs 480 crore signalling backlog.
Management expects GPT’s FY27 revenue to exceed Rs 1,600 crore, requiring about Rs 1,000 crore in H2 FY27. It said October billing had improved after workforce availability normalised, following disruption from West Bengal elections in April and May and an extended monsoon during H1.
GPT had received about Rs 1,490 crore of FY27 order inflows by the call date against its minimum Rs 3,000 crore target for the full year. Management said it expects at least Rs 2,000 crore of order inflows in H2 FY27 and expects to exceed the annual target, while continuing to bid for new contracts.
Conclusion
Alcon’s Rs 480 crore record order book gives GPT a disclosed work base for management’s Rs 150 crore FY27 revenue and about Rs 30 crore EBITDA target. The subsidiary’s expected margin close to 20% is part of management’s plan to maintain a 14% to 15% consolidated EBITDA margin while broadening the group beyond conventional infrastructure execution.
The next measures to watch are Alcon’s H2 FY27 conversion after Rs 36 crore of H1 revenue, its progress toward the Rs 200 crore-or-more next-year expectation, and further signalling wins. Management also plans to secure at least Rs 2,000 crore of H2 FY27 group order inflows and has said the proposed merger could expand Alcon’s bidding capacity.