










Greenpanel Industries Revenue Rises 4.6% in Q2 FY27
Key highlights
- Greenpanel Industries reported Q2 FY27 revenue of ₹407.3 crore, up 4.6% year-on-year and 16.4% sequentially.
- Operating EBITDA margin declined to 7.5% in Q2 FY27 from 10.2% in Q2 FY26.
- Greenpanel Industries narrowed its Q2 FY27 net loss to ₹0.6 crore from ₹6.1 crore a year earlier.
- Retail sales rose 17% year-on-year, while total volume declined 3.4% year-on-year and increased 23% sequentially.
powered by IRIS
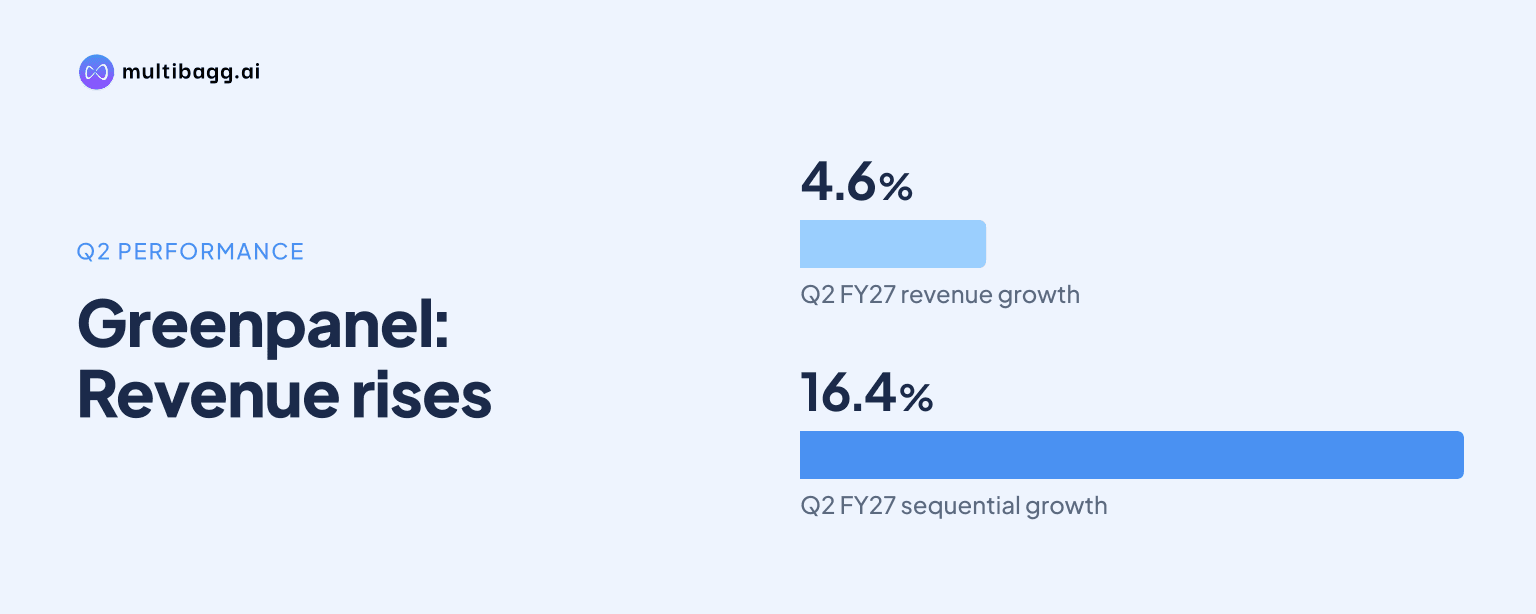
Greenpanel Industries Limited reported Q2 FY27 revenue of ₹407.3 crore, up 4.6% year-on-year and 16.4% sequentially, but its operating EBITDA margin declined to 7.5% as price reductions and higher-cost opening inventory weighed on profitability. The quarter showed stronger retail demand, while OEM and export sales recovered later than expected.
Know Greenpanel Industries inside out
Results, valuation, peers and who's buying, in one view.
What did Greenpanel Industries report for Q2 FY27?
Greenpanel reported total revenue of ₹407.3 crore for the quarter ended September 30, 2026. Revenue increased 4.6% from the corresponding quarter a year earlier and 16.4% from Q1 FY27. For the first half of FY27, revenue stood at ₹757 crore, representing year-on-year growth of 6.3%.
Operating EBITDA was ₹30.3 crore in Q2 FY27, compared with ₹27.8 crore in Q2 FY26. However, operating EBITDA margin fell to 7.5% from 9.6% in Q1 FY27 and 10.2% a year earlier. The company reported a net loss of ₹0.6 crore, substantially narrower than the ₹6.1 crore loss reported in the year-ago quarter.
Why did Greenpanel Industries' margin decline despite revenue growth?
Greenpanel said margin contraction resulted from lower product prices while cost of goods remained elevated because of higher-cost opening inventory carried from Q1 FY27. Management said the full benefit of reduced input costs was not yet reflected in Q2 results, creating an unfavourable timing gap between selling prices and costs.
Higher sales volumes helped improve fixed-cost absorption sequentially and partly offset the pressure. Still, the effect was insufficient to prevent the quarterly operating EBITDA margin from falling to 7.5%. For the first half of FY27, operating EBITDA margin improved by 100 basis points to 8.4%, according to management.
How did retail, OEM and export sales perform in Q2 FY27?
Greenpanel's retail business remained the main source of demand growth during the quarter. Retail sales grew 17% year-on-year, and retail MDF sales reached the company's highest-ever quarterly level. Plywood sales rose 8.4% year-on-year and increased 16.5% from Q1 FY27.
Total volume nevertheless declined 3.4% year-on-year because OEM sales recovered late and export sales remained flat. Management attributed the export performance to geopolitical conditions and sea-freight challenges. On a sequential basis, total volume increased 23%, indicating a stronger sales run rate than in the preceding quarter.
Greenpanel said it continued to focus on expanding sales volumes across MDF and plywood. The company is India's largest MDF manufacturer and also sells plywood through more than 1,750 dealers, with exports to seven countries. Its third production line at the Andhra facility has commenced operations, providing additional capacity for future sales growth.
Got a follow-up? Ask IRIS
What are the competitive and balance-sheet factors for Greenpanel?
Management expects MDF margins to return towards normalised levels of 20% to 25% as pricing is realigned. But Shobhan Mittal, Managing Director and Chief Executive Officer, said fresh capacity additions in South India have increased competition in the commoditised OEM segment, making the timing of any margin recovery uncertain.
The competitive environment matters because pricing pressure can persist even when volumes improve. Greenpanel's Q2 performance showed that retail sales can support revenue and capacity utilisation, but the company needs better OEM and export demand, as well as lower-cost inventory, for profitability metrics to recover more fully.
The company also reported progress on working capital and leverage. Its working-capital cycle improved by five days compared with June 30, 2026, while net debt declined to ₹133 crore. These measures indicate that the company maintained focus on balance-sheet management while navigating softer margins.
How did Greenpanel Industries communicate the Q2 FY27 update?
Greenpanel held its investor and analyst conference call on November 2, 2026, to discuss unaudited results for the quarter and half year ended September 30, 2026. The company subsequently made the audio recording of the call available through its investor-relations website, following a regulatory disclosure to BSE and the National Stock Exchange of India.
The call highlighted a mixed operating picture. Revenue and retail volumes improved, the quarterly net loss narrowed materially, and debt reduced. At the same time, lower pricing, delayed OEM recovery, flat exports and competition from additional South Indian capacity continued to restrain operating margins.
Conclusion
Greenpanel's Q2 FY27 results showed a recovery in revenue momentum, led by retail sales and sequential volume growth, while profitability remained constrained by pricing and inventory costs. Revenue reached ₹407.3 crore and the net loss narrowed to ₹0.6 crore, but the 7.5% operating EBITDA margin remained below both Q1 FY27 and the year-ago level.
Investors will watch whether reduced-cost inventory begins supporting margins, whether OEM and export demand improves, and how intensified competition affects MDF pricing. Management has indicated an expectation of mid-teen MDF volume growth in FY27 and sees a stronger third quarter and second half, but the pace of margin recovery remains dependent on market conditions.