










Gujarat Fluorochemicals restates FY26 profit to Rs 534 crore
Key highlights
- GFCL restated FY26 consolidated profit after tax to Rs 534 crore from Rs 574 crore.
- The restatement removed Rs 24 crore of deferred-tax assets and reduced CWIP by Rs 22 crore.
- FY26 basic and diluted earnings per share were revised to Rs 48.99 from Rs 52.56.
- GFCL restated September 2025 quarter profit after tax to Rs 169 crore from Rs 179 crore.
powered by IRIS
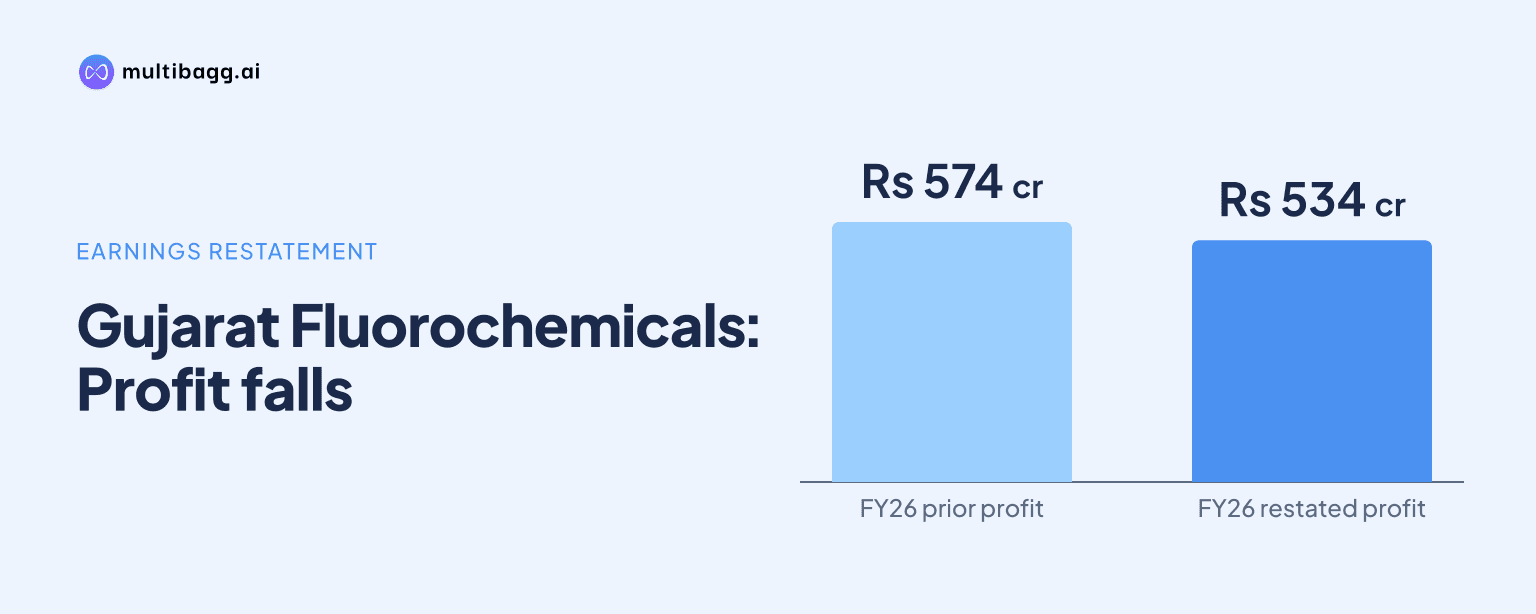
Gujarat Fluorochemicals Limited (GFCL) restated FY26 consolidated profit after tax to Rs 534 crore from Rs 574 crore, a Rs 40 crore reduction, after its EV Products subsidiary derecognised Rs 24 crore of deferred-tax assets and corrected Rs 22 crore of capital work-in-progress. The board approved the results on 3 November 2026.
Know Gujarat Fluorochemicals inside out
Results, valuation, peers and who's buying, in one view.
Why did GFCL restate its FY26 consolidated earnings?
GFCL restated the earlier consolidated figures after GFCL EV Products Limited reassessed the recoverability of a Rs 24 crore deferred-tax asset and reviewed capital work-in-progress, or CWIP. The subsidiary derecognised the asset recorded in earlier years after re-estimating future taxable profits and its ability to use unabsorbed losses under Indian Accounting Standard 12, or Ind AS 12, on income taxes.
The subsidiary also identified Rs 22 crore of expenditure included in CWIP that required correction during the current period. GFCL revised comparative financial information for the year ended 31 March 2026 under Ind AS 8, covering accounting policies, changes in estimates and errors, and Ind AS 1 on financial-statement presentation.
GFCL said the Rs 24 crore accounting derecognition does not remove the subsidiary's statutory entitlement to carry forward and set off unabsorbed tax losses against future taxable income. That entitlement remains subject to applicable Income-tax Act provisions and specified time limits, while the deferred-tax asset depends on management's estimate of future taxable profits.
How much did the restatement change GFCL's reported profit?
GFCL reduced FY26 consolidated profit after tax by Rs 40 crore to Rs 534 crore from Rs 574 crore previously reported. Profit before tax fell by Rs 22 crore to Rs 785 crore, while total comprehensive income was restated to Rs 595 crore from Rs 635 crore.
The changes also affected the comparative quarter and six months ended 30 September 2025. Profit after tax for that quarter was restated to Rs 169 crore from Rs 179 crore, while the six-month figure became Rs 346 crore from Rs 363 crore; these reductions were Rs 10 crore and Rs 17 crore respectively.
GFCL restated basic and diluted FY26 earnings per equity share to Rs 48.99 from Rs 52.56, a decline of Rs 3.57 per share. The quarter ended 30 September 2025 was revised to Rs 15.38 from Rs 16.31, and the six-month result to Rs 31.50 from Rs 33.06; GFCL said both interim per-share figures were not annualised.
Got a follow-up? Ask IRIS
Which balance-sheet accounts did GFCL revise?
GFCL reduced CWIP at 31 March 2026 by Rs 22 crore to Rs 1,868 crore from Rs 1,890 crore. It also reduced net deferred-tax assets by Rs 24 crore, taking the reported Rs 24 crore balance to nil in the restated consolidated statement of assets and liabilities.
Other equity was restated to Rs 7,760 crore from Rs 7,805 crore, a Rs 45 crore reduction. Non-controlling interest, representing subsidiary ownership not held by the group, was revised to Rs 46 crore from Rs 47 crore, explaining the total Rs 46 crore reduction across the two identified asset balances.
At 30 September 2026, GFCL reported other equity of Rs 8,381 crore and non-controlling interest of Rs 60 crore. Total equity and liabilities were Rs 12,841 crore at that date, compared with Rs 11,837 crore at 31 March 2026, whose comparative other-equity and non-controlling-interest balances reflect the restatement.
Which GFCL business was involved in the corrections?
GFCL identified GFCL EV Products Limited as the subsidiary responsible for both the deferred-tax reassessment and the CWIP review. The group reports two business segments, Chemicals and EV Products, and the filing does not attribute any part of the Rs 24 crore or Rs 22 crore adjustments to the Chemicals segment.
GFCL EV Products Limited has step-down subsidiaries in the US, Oman, Germany and Singapore. During the six months ended 30 September 2026, the group incorporated GFCL EV New Age Materials SAOC in Oman for manufacturing and trading battery chemicals, while GFCL Semiconductor and Advanced Materials Limited was incorporated in India on 26 June 2026.
What other disclosed matters should readers watch?
GFCL recorded a Rs 20 crore exceptional item for the year ended 31 March 2026 relating to the New Labour Codes, which became effective on 21 November 2025. The company said the legislative changes required immediate recognition of past-service cost under Ind AS 19 on employee benefits, separately from the EV Products tax and CWIP restatement.
GFCL also received Rs 11 crore on 24 April 2026 as the full and final property, plant and equipment claim arising from the December 2021 Ranjitnagar plant fire. A Rs 28 crore balance of the insurance claim remains under the insurer's determination for loss of profit, and management said any difference would be recognised on final determination.
Conclusion
GFCL's restatement reduces FY26 consolidated profit after tax by Rs 40 crore to Rs 534 crore, while reducing CWIP by Rs 22 crore and eliminating Rs 24 crore of net deferred-tax assets at 31 March 2026. The correction also lowered FY26 earnings per share by Rs 3.57 to Rs 48.99 and revised the September 2025 comparative profit figures.
Readers can next watch whether GFCL EV Products Limited generates taxable income against which its unabsorbed tax losses may be used, subject to tax-law conditions and time limits. Further disclosed items to monitor are the insurer's decision on the remaining Rs 28 crore loss-of-profit claim and regulatory approvals for the proposed arrangement announced after the 9 July 2026 exchange no-objection letters.