










Hexagon Nutrition Limited H1 FY27 Revenue Rises 27.3% to ₹214 Crore
Key highlights
- Hexagon Nutrition reported H1 FY27 revenue of ₹214.0 crore, up 27.3% year-on-year from ₹168.0 crore.
- H1 FY27 EBITDA was ₹22.7 crore, while EBITDA margin declined 270 basis points to 10.6%.
- Q2 FY27 revenue was ₹109.7 crore, up 15.2% year-on-year, and PAT was ₹8.2 crore.
- Q2 FY27 included a ₹1.13 crore exceptional expense for Nashik premix facility restructuring.
powered by IRIS
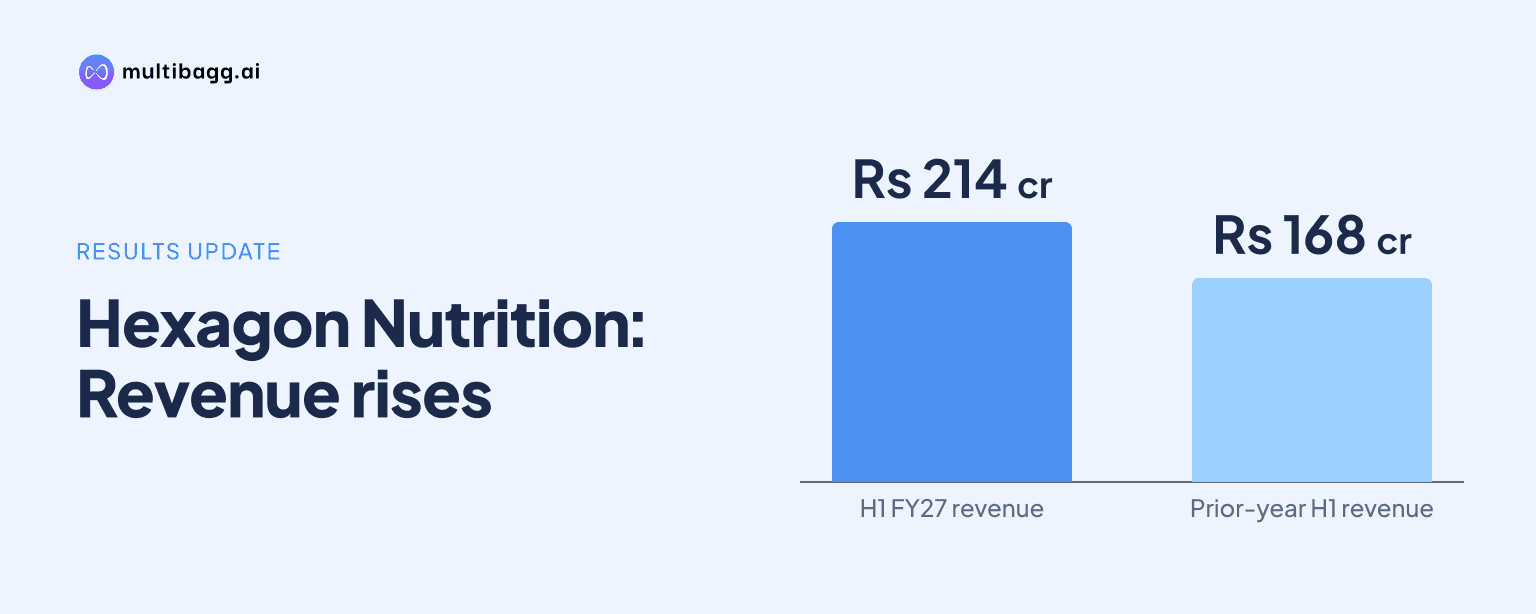
Hexagon Nutrition Limited reported revenue from operations of ₹214.0 crore in H1 FY27, a 27.3% year-on-year increase from ₹168.0 crore, while profit after tax stood at ₹16.2 crore and the PAT margin declined to 7.6% from 9.9% a year earlier.
Know Hexagon Nutrition inside out
Results, valuation, peers and who's buying, in one view.
What did Hexagon Nutrition report for H1 FY27?
Hexagon Nutrition Limited, which manufactures and markets micronutrient premixes, therapeutic nutrition, clinical nutrition, food fortification solutions and consumer nutrition products, announced its financial results for the quarter and half year ended September 30, 2026. The company reported higher revenue for the first half of FY27, although profit growth and margins did not keep pace with sales growth.
Revenue from operations rose to ₹214.0 crore in H1 FY27 from ₹168.0 crore in H1 FY26. Gross profit increased 15.0% year-on-year to ₹97.4 crore from ₹84.7 crore. EBITDA rose 1.6% to ₹22.7 crore, compared with the previous corresponding half year.
The difference between revenue growth and EBITDA growth resulted in a lower operating margin. EBITDA margin was 10.6% in H1 FY27, compared with 13.3% in H1 FY26. Profit after tax was ₹16.2 crore, translating into a PAT margin of 7.6%, against 9.9% in the year-earlier period.
The H1 performance combines a strong first-quarter revenue comparison, as referred to in the company-related update, and a slower growth rate in the September quarter. The reported figures show that the company expanded its sales base during the half year while profitability ratios moved lower.
How did Hexagon Nutrition perform in Q2 FY27?
Hexagon Nutrition reported Q2 FY27 revenue from operations of ₹109.7 crore, up 15.2% year-on-year from ₹95.2 crore in Q2 FY26. The quarterly revenue figure was also higher than the preceding quarter, according to the reported sequential comparison.
Gross profit for the September quarter was ₹51.6 crore, up 2.1% from ₹50.5 crore a year earlier. EBITDA stood at ₹10.9 crore and the EBITDA margin was 9.9%. The quarterly margin was below the H1 margin of 10.6% and below the 13.3% margin reported for H1 FY26.
Profit before tax in Q2 FY27 was ₹10.1 crore. Profit after tax was ₹8.2 crore, with a PAT margin of 7.4%. The supplied results summary described the quarterly net-profit comparison as lower year-on-year, but the company figures provided do not specify the prior-year Q2 PAT amount.
The consolidated Q2 results cited revenue of ₹109.66 crore and net profit of ₹8.17 crore, which round to the ₹109.7 crore and ₹8.2 crore figures in the earnings release. Standalone Q2 revenue was ₹103.83 crore and standalone net profit was ₹9.82 crore.
What do the revenue and margin figures show?
The results show that Hexagon Nutrition's revenue increased faster than its gross profit, EBITDA and profit after tax during H1 FY27. Revenue rose 27.3%, gross profit increased 15.0%, and EBITDA increased 1.6%, resulting in a 270-basis-point decline in EBITDA margin from 13.3% to 10.6%.
The PAT margin declined by 230 basis points, from 9.9% in H1 FY26 to 7.6% in H1 FY27. In Q2 FY27, the EBITDA margin was 9.9% and the PAT margin was 7.4%, indicating that the September-quarter profitability ratios remained below the H1 FY26 comparison level.
For investors, the figures separate growth in sales from the earnings retained after operating and tax costs. The company has reported a medium-term target to improve EBITDA margin to a range of 13-14%, making the movement in margins a key point in future disclosures.
Got a follow-up? Ask IRIS
What operational and exceptional items were disclosed?
Hexagon Nutrition's reported Q2 results included a ₹1.13 crore exceptional expense relating to restructuring at its Nashik premix facility. This item was identified in the results update alongside the consolidated quarterly financial performance.
The auditors also highlighted material uncertainty related to going concern at two overseas subsidiaries. The disclosed update said the parent had committed support to those subsidiaries. No further financial impact from this matter was specified in the information provided.
The company is involved in nutrition categories that include premixes, therapeutic nutrition, clinical nutrition, food fortification and consumer nutrition. Its financial reporting therefore covers operations across product areas serving nutrition and health-related applications, although the supplied earnings material does not provide a segment-wise revenue split.
The Board of Directors approved the unaudited standalone and consolidated results at its meeting on November 14, 2026. The company also published extracts of newspaper advertisements relating to the quarter and half-year results.
When will investors hear more from Hexagon Nutrition?
Hexagon Nutrition rescheduled its analyst and institutional investor conference call to November 17, 2026, at 4:00 PM IST, from the previously announced date of November 18. The stated purpose of the call is to discuss operational and financial performance for Q2 and H1 FY27.
The company-related disclosures also refer to investor events in November, including the CITIC CLSA India Forum in Mumbai on November 16 and the Morgan Stanley Asia Pacific Summit in Singapore on November 18-19. Representatives may discuss the investor presentation for the period ended September 30, 2026, which was made available on the company website and stock exchanges.
Investors will be able to assess management's discussion of the revenue increase, the lower operating margin and the stated medium-term EBITDA margin range of 13-14%. The supplied material does not provide revised financial guidance, a detailed capex schedule or a timeline for the Nashik facility restructuring.
Conclusion
Hexagon Nutrition delivered a 27.3% increase in H1 FY27 revenue to ₹214.0 crore, supported by quarterly revenue of ₹109.7 crore in Q2. However, EBITDA rose only 1.6% in the half year, and both EBITDA and PAT margins declined from the corresponding prior-year period. The result places the focus on profitability alongside revenue growth.
The November 17 analyst call is the next disclosed event for investors seeking management commentary on margin movement, the Nashik restructuring expense and support for overseas subsidiaries. The company's stated medium-term EBITDA margin target of 13-14% provides a benchmark for tracking subsequent results.